
Emerald Clinical Trials Appoints Michael Stibilj as Chief Executive Officer to Lead Next Phase of Global Growth
Source: PR Newswire
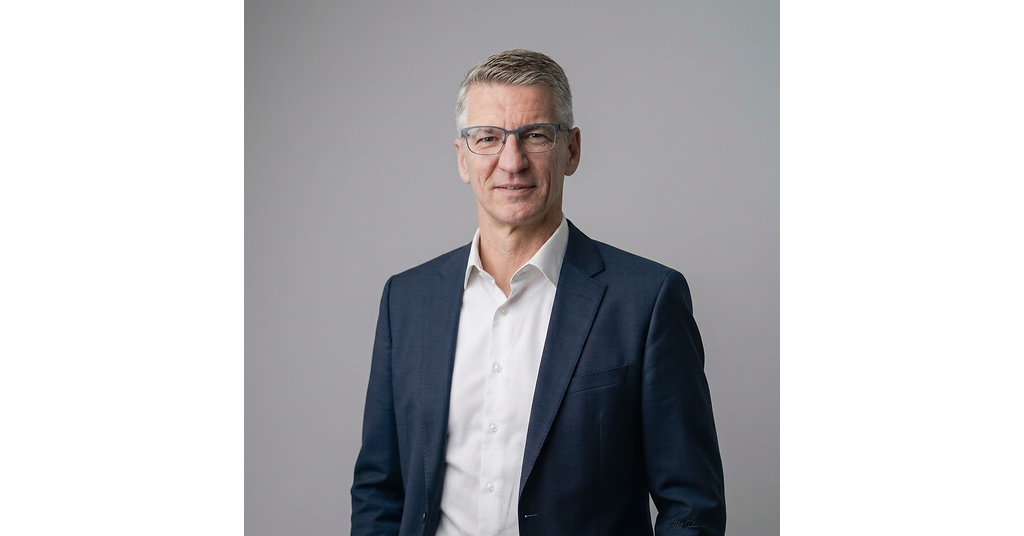
Emerald Clinical Trials appointed CRO veteran Michael Stibilj as CEO effective October 1, 2026, following a transformative year that included its acquisition of Hongyi Clinical Development Services. The combined platform has more than 1,000 professionals across 40+ countries and 70+ locations, positioning the Singapore-based CRO to pursue faster clinical-development growth in Asia-Pacific. The company cited expanding innovation pipelines, technological advances and demand for high-quality, rapid clinical trial delivery as growth drivers.
Analysis
This is not a direct catalyst for IQVIA (IQV): executive turnover several layers below its current operating structure is unlikely to alter IQV's bookings, utilization, or pricing. The more relevant read-through is competitive: a scaled Asia-focused CRO with leadership experienced in multinational execution could compete more effectively for mid-cap biotech trials that require China/APAC enrollment and Western-quality regulatory processes. That pressure would be concentrated in smaller regional CROs and could modestly constrain IQV's share only in faster-growing APAC programs over a 6-18 month horizon, not near-term earnings.
The stated growth opportunity requires proof through measurable operating outcomes rather than management credentials. Watch for incremental trial wins, site activation times, China cross-border study approvals, backlog conversion, and post-acquisition employee retention over the next two reporting cycles; failure on any of these would imply integration costs without the intended scale benefits. The ticker "PPC" appears to be an unreliable public-market mapping for the executive's prior employer rather than a financially connected listed security, so it should not be traded on this item.
Contrarian view: public CRO valuations are presently driven more by biotech funding, large-pharma R&D budgets, cancellation rates, and FCF conversion than by isolated private-competitor leadership changes. Unless Emerald begins taking disclosed programs from listed incumbents or uses its regional footprint to reset APAC pricing, this is a weak signal and does not warrant an immediate sector position.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No directional trade in IQV on this announcement; treat it as a 6-18 month competitive-intelligence item rather than an earnings catalyst.
- Add an alert for IQV quarterly disclosures showing APAC book-to-bill deterioration, lower backlog conversion, or margin pressure attributed to regional pricing; only then evaluate a relative short versus a diversified healthcare-services basket.
- Do not trade PPC based on this news until ticker/entity mapping is independently verified; the referenced prior employer may not correspond to the listed PPC security.
- For CRO exposure, wait for biotech financing and sponsor R&D-budget data before adding risk: a broad improvement in those inputs would be more actionable for IQV than this management appointment, while a bookings or guidance cut would falsify a constructive sector view.
More News
- Can Trump Oust Powell From the Fed Board? What to Know
- Europe’s winter energy crunch may already be underway. Two U.S. stocks that may benefit
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company