
Agthia Reports Revenue Growth Amid Challenging Cost Environment
Source: PR Newswire
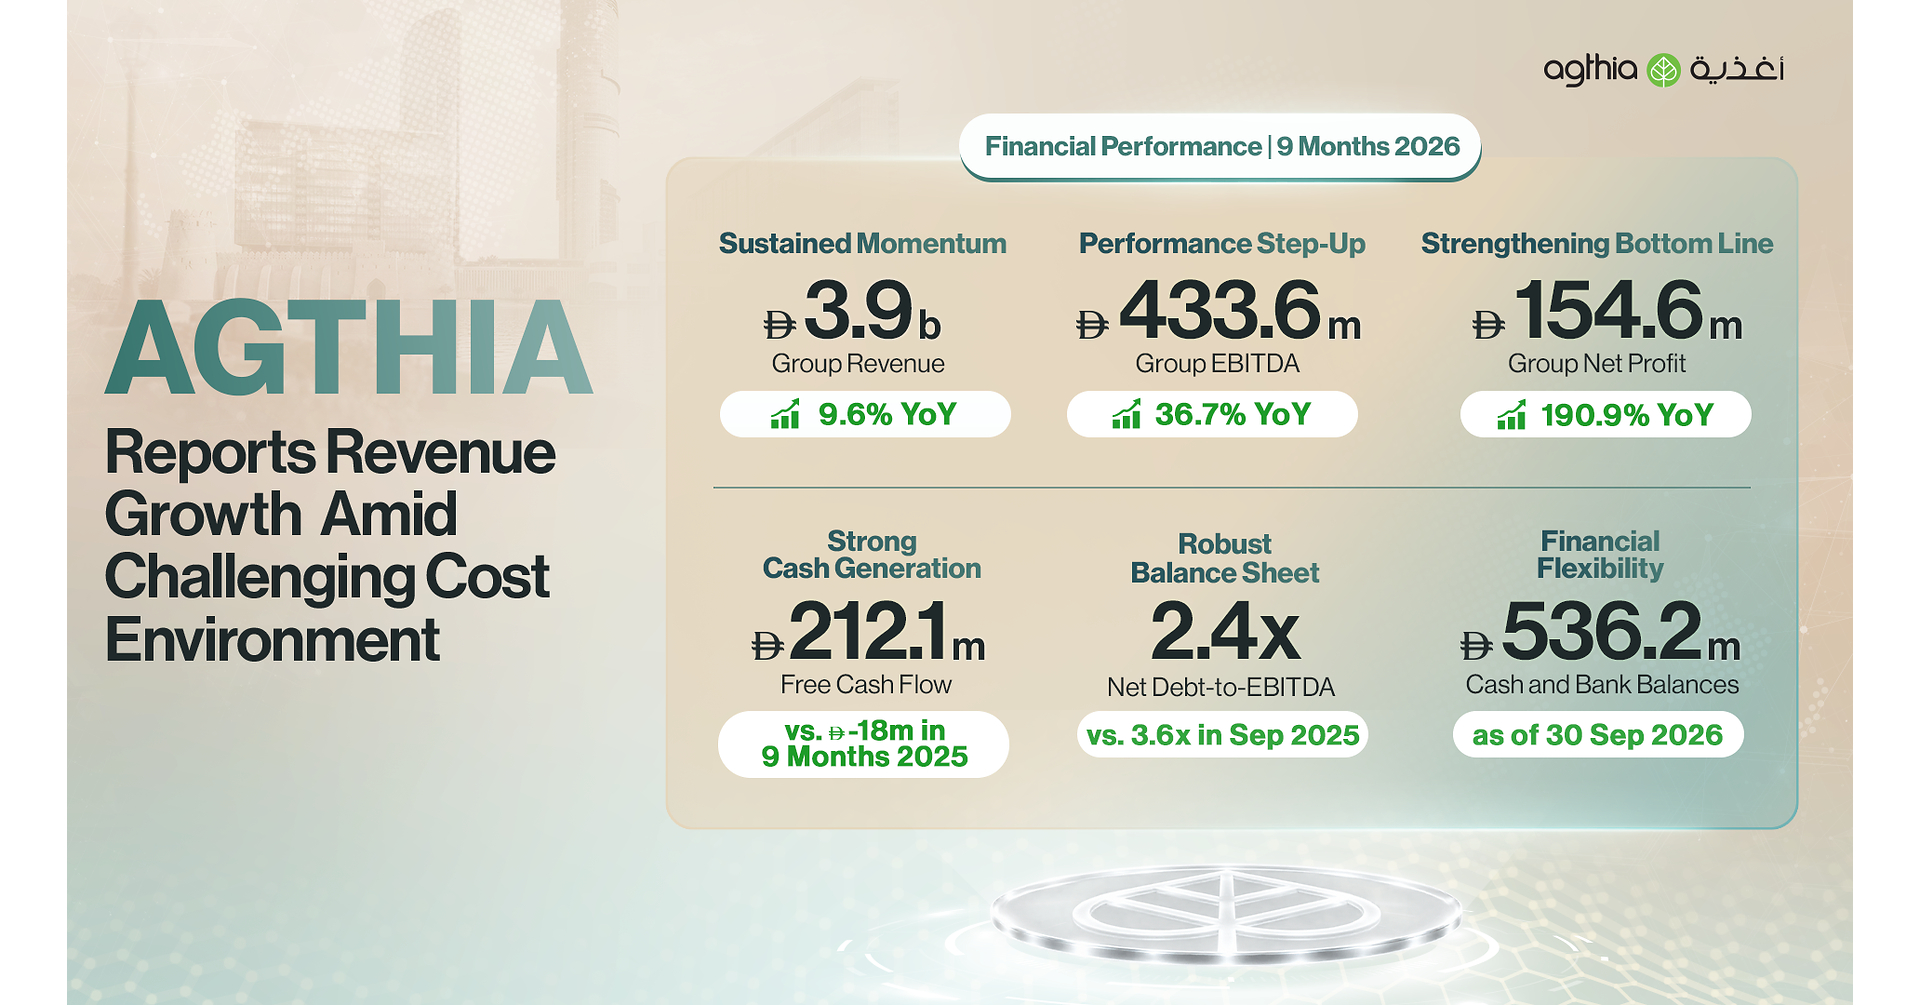
Agthia’s Q3 2026 revenue rose 14.4% year on year to AED 1.3 billion, including AED 104.7 million in one-off sales; underlying growth was 5.2%. EBITDA increased 39.0% to AED 123.1 million, while net profit was AED 33.2 million versus AED 4.1 million a year earlier, which included Snacking impairment charges. Nine-month revenue rose 9.6% to AED 3.9 billion and net profit nearly tripled to AED 154.6 million, alongside improved net debt-to-EBITDA of 2.4x; higher input, freight and distribution costs and regional logistics disruptions remained headwinds.
Analysis
The key read-through is earnings quality, not headline growth: one-off sales and a prior-year impairment distort comparisons, while underlying revenue growth is much slower than reported growth. The 39% EBITDA increase may signal genuine operating leverage from the Snacking reset, but it is not yet proof of durable group-wide margin expansion: Agri-Business shows how quickly input and distribution costs can overwhelm sales growth. Positive free cash flow and lower leverage provide a buffer against that volatility, not immunity from it.
Near term (days), the results may support sentiment, but chasing a rally risks paying for non-recurring sales and an easy impairment comparison. Over 1–3 months, watch whether PET, freight and feed-cost pressure eases and whether Snacking’s gross-margin gains convert to sustained segment EBITDA. Over 6–18 months, Saudi protein capacity and store expansion offer growth optionality; execution and logistics reliability determine whether added volume produces attractive returns.
Contrarian angle: investors may over-credit the transformation based on consolidated EBITDA while underweighting Agri-Business margin compression. Conversely, a broad dismissal of the quarter as one-off-driven would miss improving cash generation and the possibility that Snacking’s reset is structurally lifting profitability. No valuation or market-reaction data are provided, so the earnings alone do not establish an attractive entry price.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Key Decisions for Investors
- Do not chase an opening spike in Agthia; consider a staged, modest long only after the initial reaction if price action remains constructive and subsequent reporting confirms core growth and recurring EBITDA improvement. Upside is transformation-led margin recovery; downside is cost pressure overwhelming it.
- Use the next 1–3 months to verify segment EBITDA, not just revenue: persistent Agri-Business margin contraction or renewed group free-cash-flow deterioration would falsify the improving-quality thesis and warrant avoiding or reducing exposure.
- Track PET, freight, feed-input costs and regional logistics disruptions as leading indicators. A sustained easing would support margin recovery; renewed increases or export disruption would weaken the case even if reported sales remain strong.
- Treat Saudi protein capacity and Abu Auf expansion as 6–18 month catalysts, not near-term earnings certainty. Verify utilization, contribution to profit and cash conversion before assigning them a durable valuation premium.
More News
- NextDC shares surge 43% after Goodman, Digital Realty stake purchases
- Asian chip stocks slide as disappointing Qualcomm, Arm earnings weigh
- China Blocks SoftBank Acquisition of ABB Robot Unit, FT Says
- Snap shares fall over 10% on third-quarter earnings miss
- ‘Seismic’ blue wave triggers the sinking of oil prices, energy stocks, and the chances of power permitting reform
- Softbank’s $5.4 bln takeover of ABB robotics unit blocked by China- FT