
Gifford Bioscience expands with a new dedicated radiometric laboratory at the BioHub Birmingham
Source: PRWeb
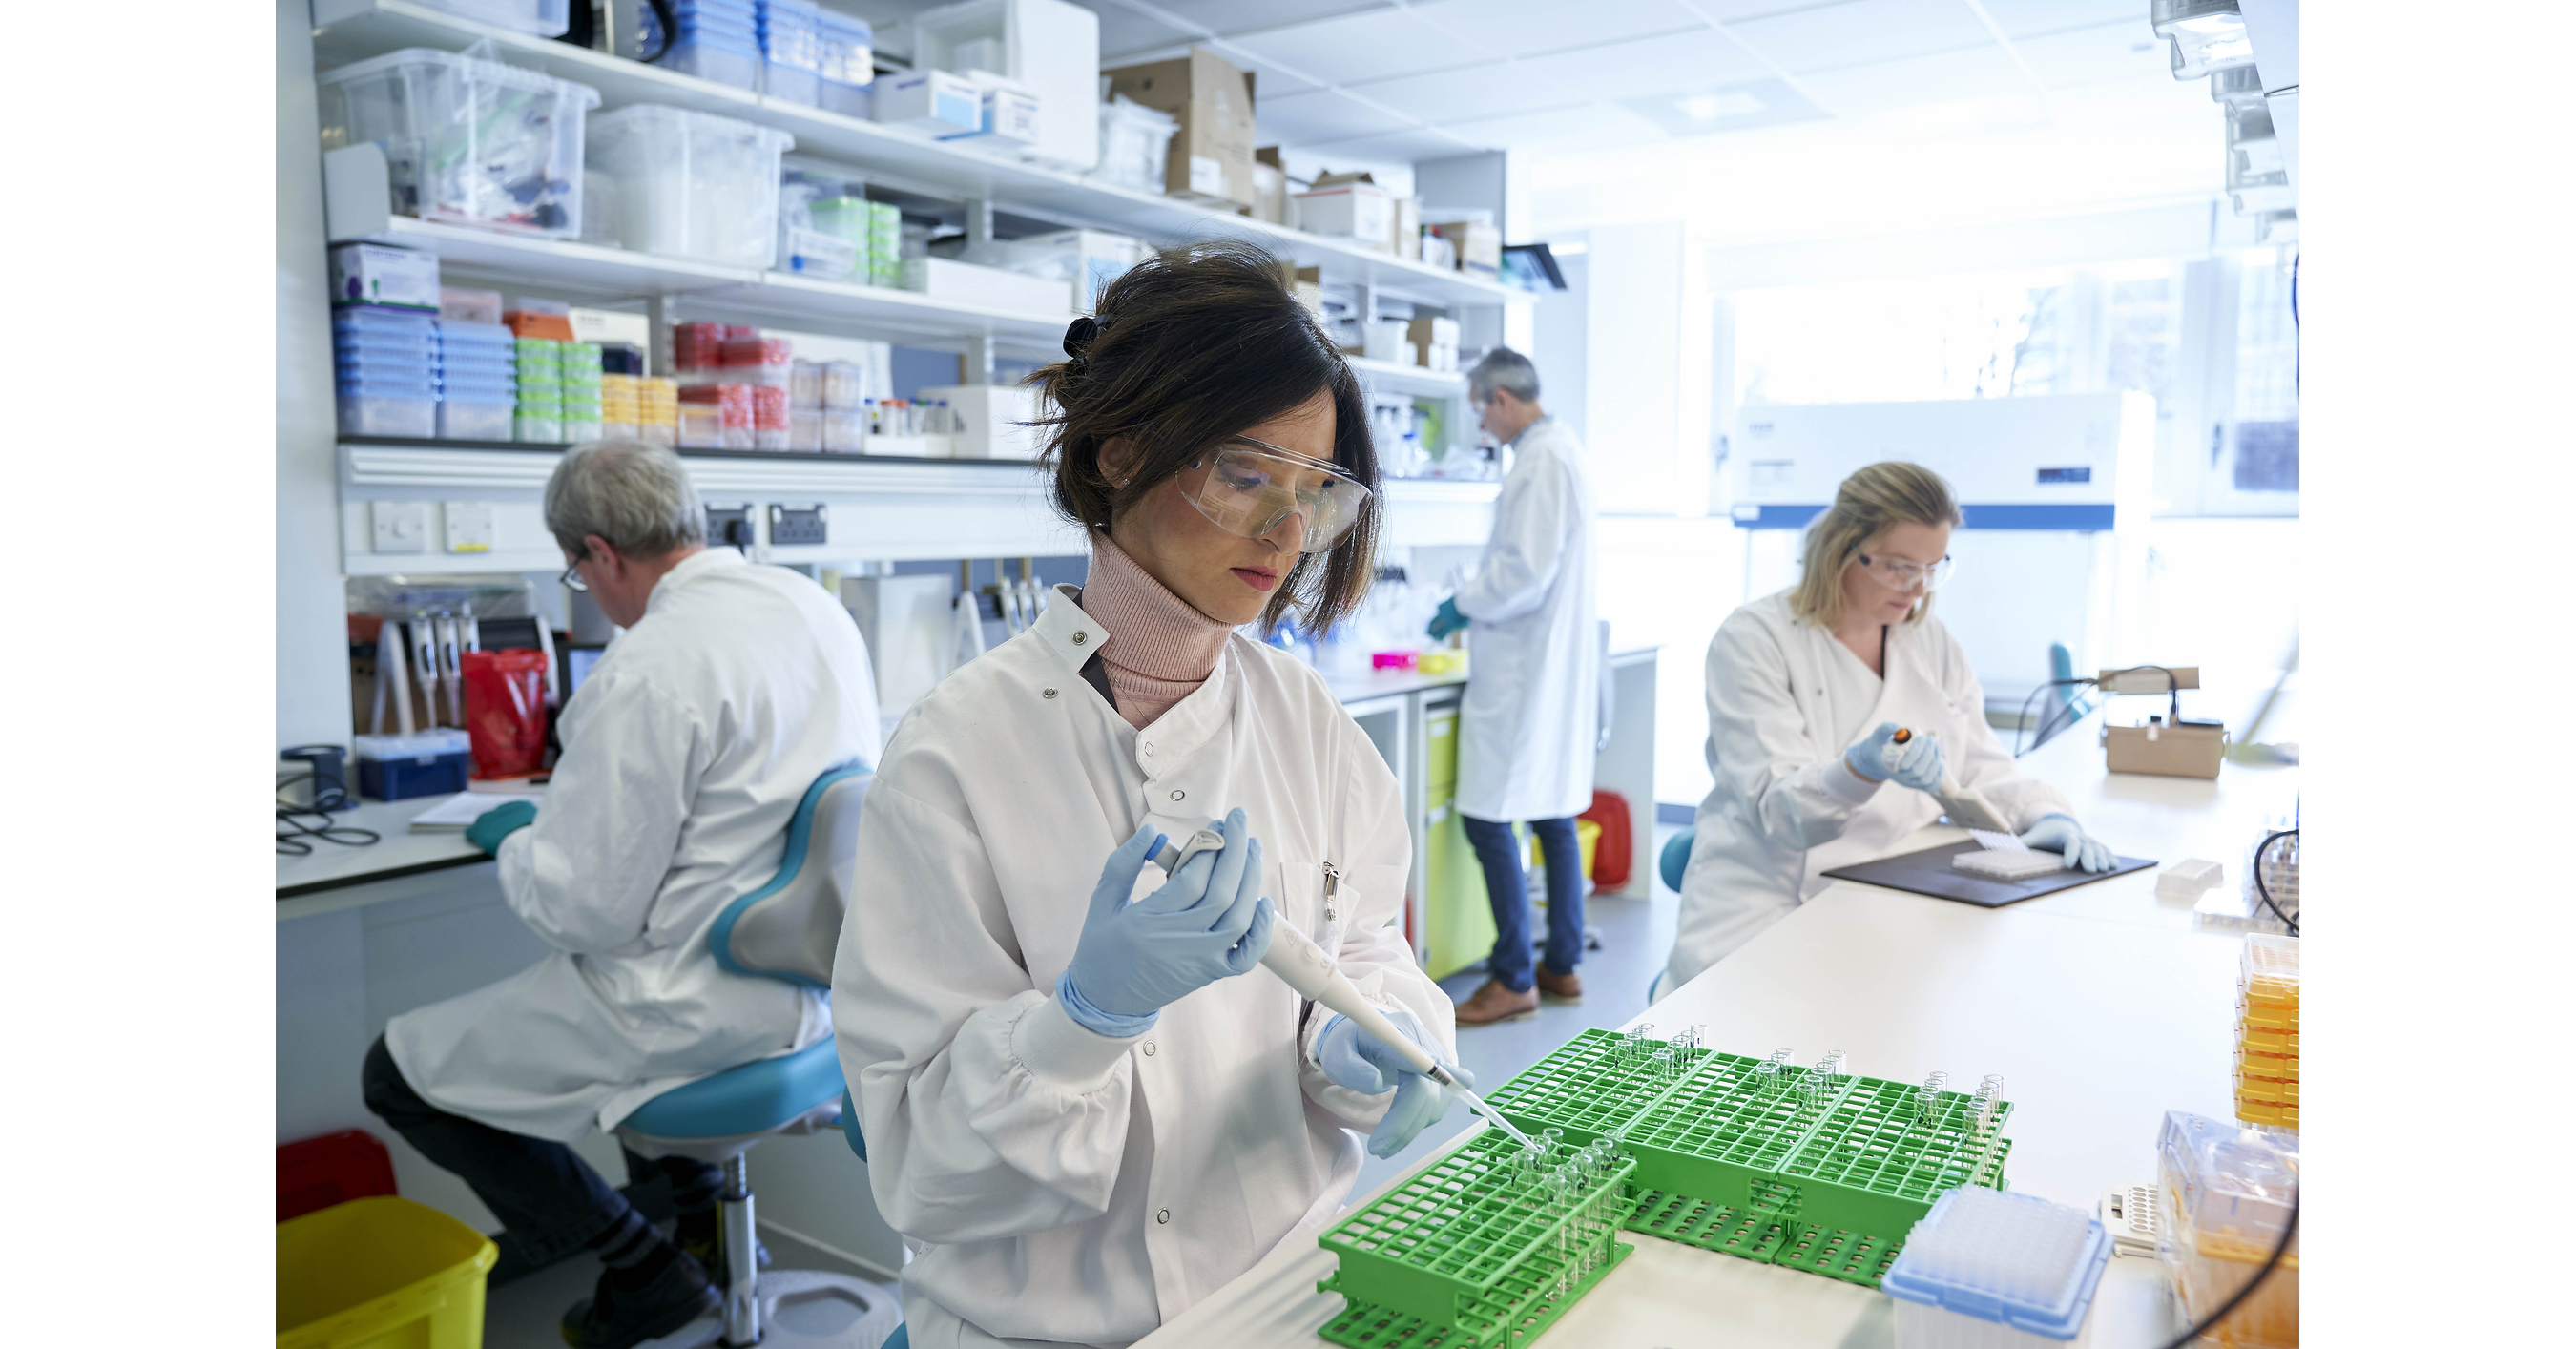
Gifford Bioscience opened additional radiometric laboratory space at BioHub Birmingham in July 2026, expanding capacity for client studies and custom assay development. The new space supports radioligand binding, quantitative autoradiography, uptake and release, and receptor occupancy studies alongside the company’s existing services.
Analysis
This is a small, private-company capacity signal—not evidence of sector-wide CRO demand or a material change in drug-development economics. The key investable question is whether added assay capacity converts into sustained utilization, pricing power, or repeat work; none is disclosed. If it does, the benefit would accrue first to Gifford and its clients’ preclinical decision process, not automatically to downstream drug developers: better target-engagement data can help stop weak candidates earlier, potentially reducing later-stage waste, but does not establish higher clinical success rates.
The read-through to listed CROs such as Charles River Laboratories is weak: Gifford’s specialist receptor-pharmacology work is not a basis for inferring a meaningful change in larger peers’ revenue or margins. Timing also dilutes the news value—the lab reportedly opened in July, while the announcement is dated October—so this is not a fresh operating catalyst. Over 1–3 months, watch for disclosed utilization, customer wins, or hiring; over 6–18 months, recurring demand and the ability to sustain pricing would matter more than facility capacity alone. The contrarian point is that added capacity can be a fixed-cost burden if client demand fails to ramp. No public-market position is warranted on this release alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No trade on the announcement: Gifford is not identified as a listed company in the supplied data, and there is no quantified financial impact to translate into a public-equity position.
- Treat Charles River Laboratories as an adjacent-sector watch item, not a direct beneficiary. Revisit only if evidence emerges that specialist assay outsourcing is increasing across the broader preclinical market.
- Monitor for utilization, repeat-customer activity, pricing, and any incremental staffing or operating-cost disclosures; capacity without demand would weaken the expansion thesis.
- Falsify a positive read-through if follow-up disclosures show underused capacity, no customer conversion, or increased costs without corresponding revenue growth. Conversely, multiple customer wins and sustained utilization would support a more constructive view of specialist CRO demand.
More News
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- All the news about the iPhone Duo
- The Tesla Roadster should go into production in 2028, but don't get your hopes up
- Apple’s $1,999 iPhone Duo puts the company's status-symbol power to the test
- Yields continue to rattle investors. These sectors are most at risk if rates stay elevated