
Bacardi Struggles in North America Even as Wider Profits Rise
Source: Bloomberg
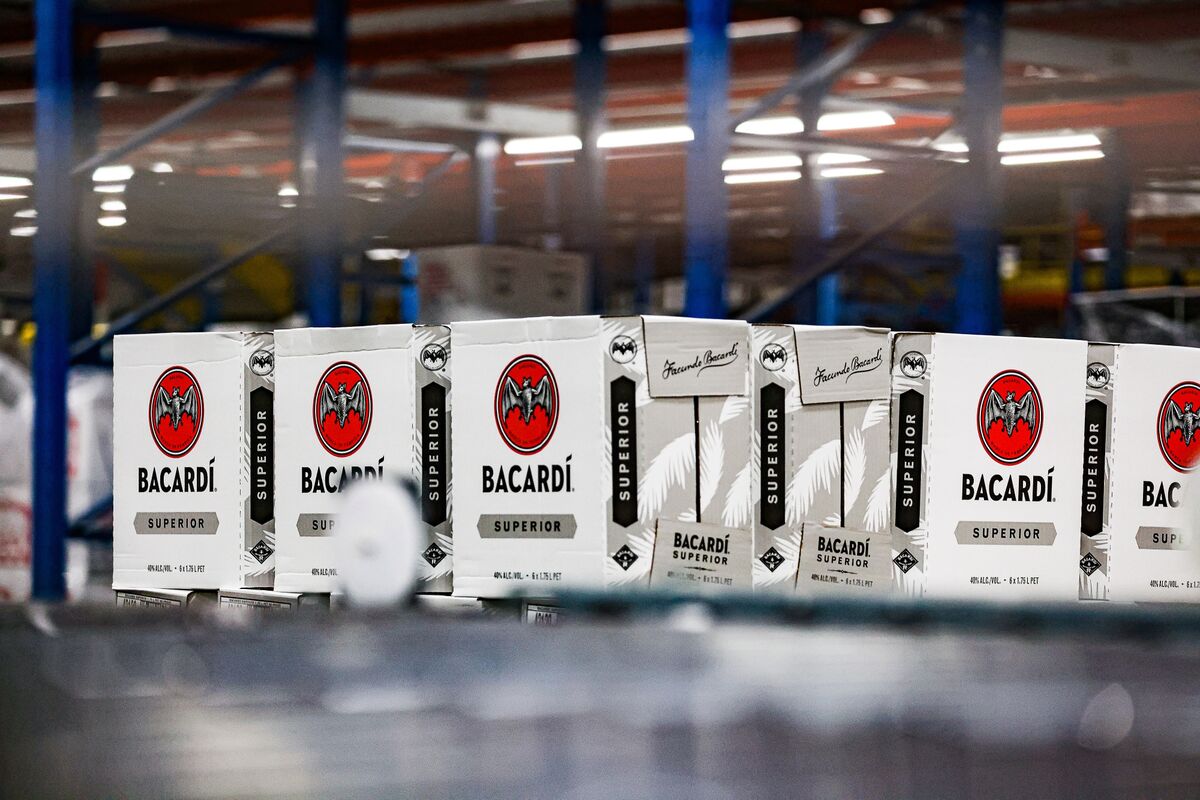
Bacardi-Martini NV's North American sales fell 14% over the past two years, signaling continued weakness in the regional spirits market. Profit nevertheless rebounded in the fiscal year ended March 31, as sales growth in Europe and other international markets more than offset the North American decline.
Analysis
The relevant read-through is not simply weaker spirits demand, but a likely reset in North American distributor inventories and promotional intensity. Private Bacardi's geographic diversification limits its own reported earnings damage, while listed peers with greater US exposure—Brown-Forman (BF.B), Constellation Brands (STZ) and Diageo (DEO)—face a less favorable earnings mix: lower shipment growth, more trade spend, and reduced operating leverage. Beam Suntory's private status makes BF.B the cleaner public proxy for premium brown-spirit category pressure.
Over the next 1-3 months, channel commentary and US depletion-versus-shipment gaps matter more than reported revenue. A recovery in Europe does not fully offset North American weakness for DEO and BF.B because US premiumization has historically carried above-average gross margins; a mix shift toward value offerings can compress margins even if volumes stabilize. Suppliers to on-premise consumption and glass/packaging should see only modest spillover, since the more material adjustment is likely distributor working capital rather than production capacity.
Consensus may be too quick to extrapolate a broad consumer collapse. Spirits weakness is increasingly category-specific—tequila, ready-to-drink and moderation trends are taking occasions from traditional rum and whiskey—so STZ's beer franchise could remain comparatively insulated. The bearish thesis is falsified if US depletions turn positive while promotional spending stays contained; that would imply inventory normalization, not demand destruction, and support a rapid multiple rebound in the beaten-down spirits complex over 6-12 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.10
Key Decisions for Investors
- Maintain a 1-3 month relative-value bias: long STZ / short DEO, sized neutral to broad consumer staples beta. STZ offers better insulation through Mexican beer exposure, while DEO remains exposed to US spirits shipment normalization and margin risk; reassess if DEO reports US organic net-sales acceleration without higher A&P expense.
- Avoid adding to BF.B ahead of its next North America depletion and distributor-inventory update. Upgrade to a long only if management demonstrates sequential depletion improvement and holds gross-margin guidance; otherwise, downside is a guidance reset driven by promotions rather than volume alone.
- Use DEO earnings as an event-risk watch rather than an outright pre-report short absent current inventory data. A disclosed widening between shipments and depletions, or incremental US trade-spend guidance, would support a 3-6 month short; a clean inventory normalization commentary would invalidate it.
- Watch US on-premise traffic, spirits depletions and retailer promotional activity over the next 60-90 days. Broad stabilization would favor selective mean reversion in DEO/BF.B; continued weakness concentrated in rum and whiskey favors staying long STZ versus spirits suppliers.
More News
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- Here's what happens to the economy when Treasury yields soar like they are now
- Oil industry warns a diesel export ban will raise fuel prices as Trump weighs restrictions
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet
- Meta's standoff with Amazon over Muse could be a sign of things to come
- How a Diesel Export Ban Could Impact US Fuel Prices