
PURECORE PROVIDES CORPORATE UPDATE HIGHLIGHTING EXECUTION ACROSS URANIUM, COPPER AND CAPITAL MARKETS
Source: PR Newswire
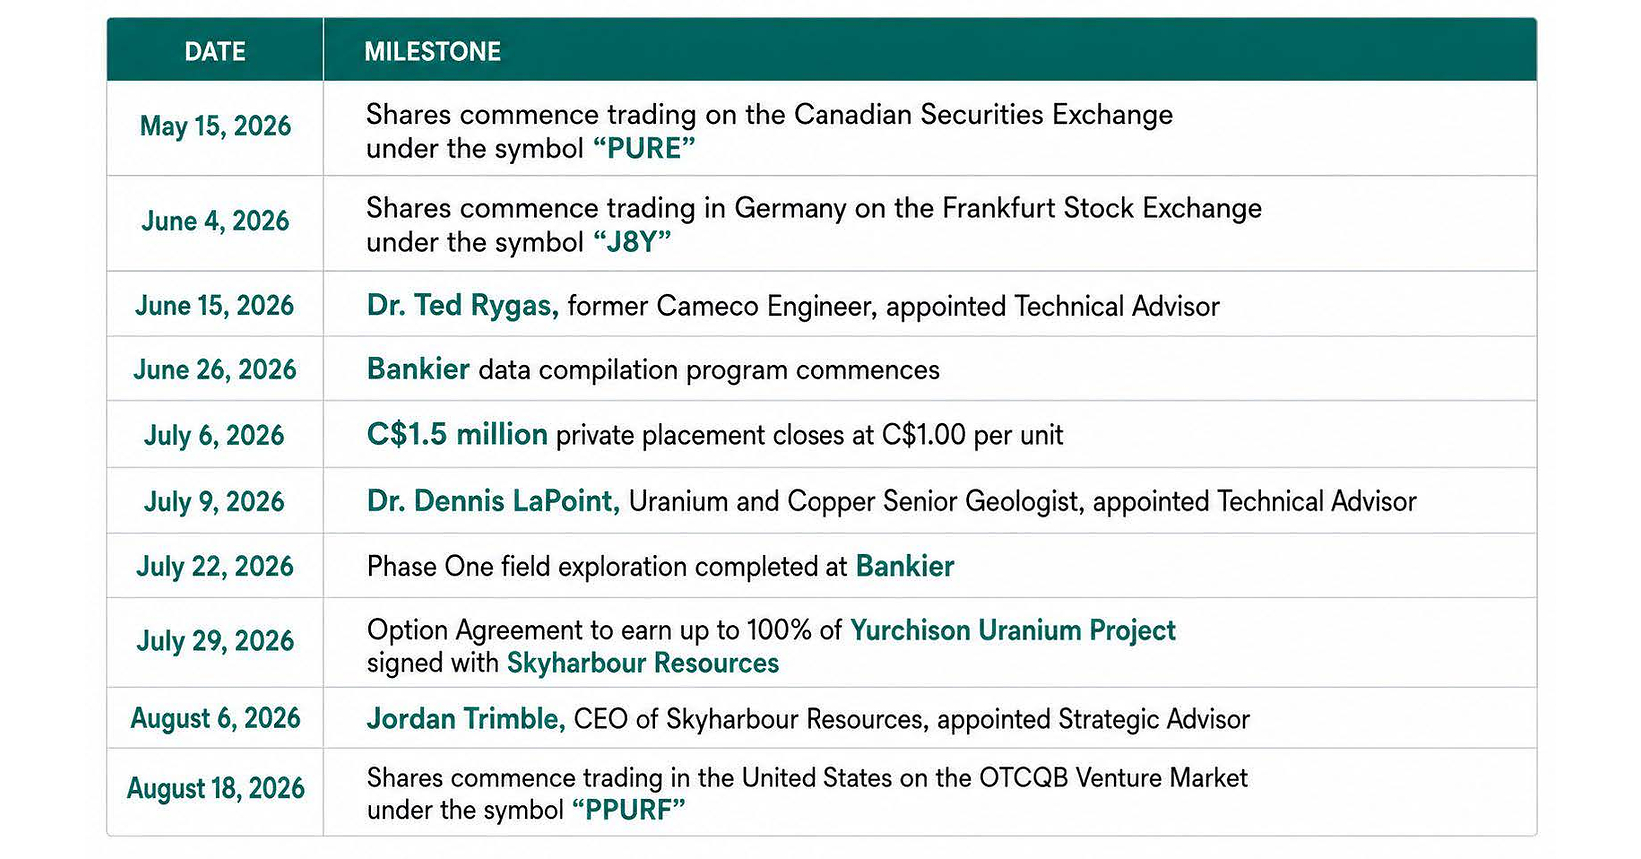
Purecore Metals closed a C$1.5 million non-brokered private placement at C$1.00 per unit (1,500,000 units) with warrants exercisable at C$2.00, expanding capital to advance exploration. The company also signed a definitive option agreement with Skyharbour to potentially earn up to a 100% interest in the 35,029-hectare Yurchison Uranium Property and completed field work (July 2026) at its 100%-owned Bankier copper/uranium project. Management highlights supportive uranium (BofA forecast US$130/lb average in 2027) and record copper prices, framing a near-term exploration ramp and continued market access expansion across Canada, Europe, and the U.S.
Analysis
This reads more like a liquidity event than a fundamental rerating. For PURE, the real variable is not the “two-commodity” story but whether recent capital can be converted into visible drill milestones before the warrant overhang and next financing reset the price. In microcap uranium explorers, incremental investor access can help near-term turnover, but it rarely changes terminal value unless it is paired with assay/drill data.
The cleaner second-order beneficiary is SYH: it monetizes optionality by farming out risk while preserving embedded discovery upside, which is the superior capital structure in a weak-data phase. Any enthusiasm for the uranium basket should be expressed through more liquid names if the goal is sector beta, because this update does not alter supply-demand math for CCJ or the broader uranium tape. The copper angle is even less actionable; it remains a narrative overlay, not a cashflow driver.
Contrarian view: the market may be overpaying for jurisdictional acreage and advisor optics while underweighting funding risk. The key falsifier is the absence of tangible technical progress within 60-90 days; at that point, the stock is more likely to trade on dilution mechanics than commodity forecasts. If management follows this with a discounted raise or inconclusive field work, the setup becomes a sell-the-rally rather than a momentum buy.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Do not chase PURE here; wait 60-90 days for drill targets, permits, or assay data before considering exposure. If price extends >20% above the C$1.00 financing anchor without new technical results, fade strength.
- Relative-value: long SYH / short PURE for 1-3 months as a pair trade on project-generator quality vs. explorer dilution risk; stop if PURE posts material drill success or SYH monetizes additional assets.
- If the goal is uranium beta, use CCJ or a liquid uranium ETF proxy instead of PURE; this release is not enough to justify taking microcap execution risk.
- Watch PURE's next financing terms closely; if new capital prices below the prior round or includes heavy warrant sweeteners, treat that as a negative catalyst and reduce any speculative long.
- Alert item: if SYH announces cash-generative option terms or if PURE secures a partner-funded program, that would improve the risk/reward and could flip the pair.
More News
- Bank of America is bullish on these top stocks ahead of earnings
- Wall Street sees buying opportunity in banks as shares tank ahead of earnings
- This AI infrastructure stock will rise on agentic AI boom, Bank of America says
- Milos Maricic: listen for the AI number on next week’s bank calls
- Alignment Healthcare Investigation Notice: SueWallSt Notifies Investors of Pending Investigation Into Alignment Healthcare (ALHC)
- Jim Cramer's top 10 things to watch in the stock market Friday
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Analyze SEC Filings With AI: A Verification-First Guide
- AI for IR Street Intelligence: Notes, Estimates, and Peers