
Parks Associates: Ten Streaming Services Phased Out in Q2 2026 as US Streaming Video Market Reorganizes
Source: PR Newswire
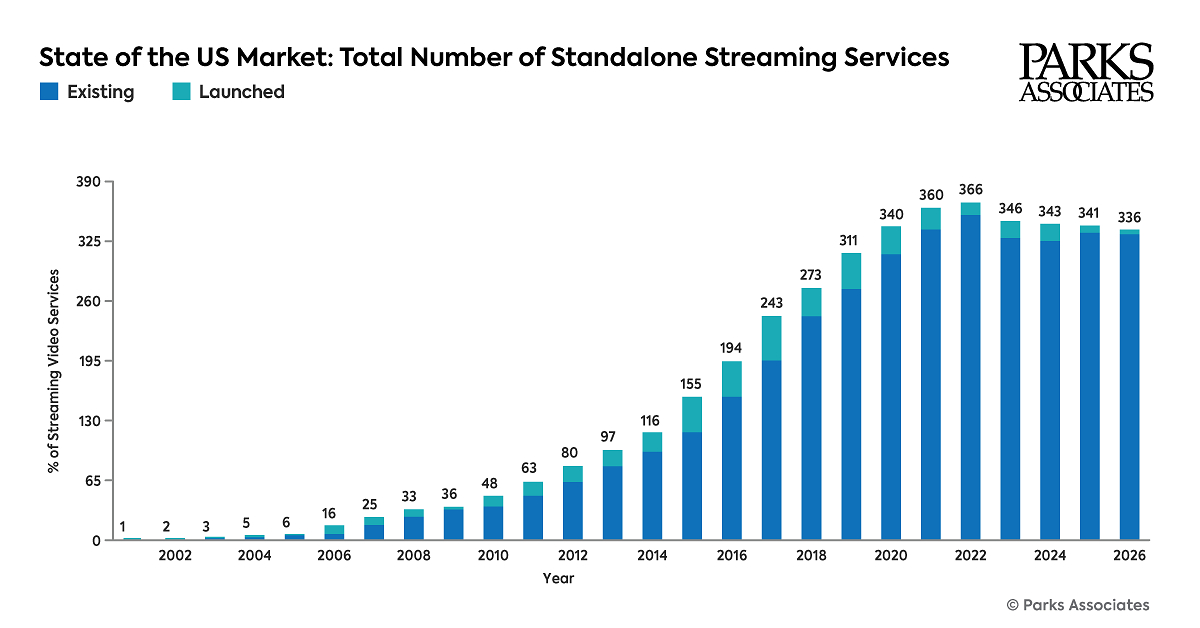
Parks Associates reported that 10 U.S. streaming-service profiles were phased out in Q2 2026, including BET+ as Paramount Skydance moved its content into Paramount+ via a dedicated BET Hub. The tracker added OG Network and TrueTVplus, bringing its coverage to 370 U.S. and 234 Canadian streaming services. The changes underscore continued consolidation and experimentation with FAST, AVOD, and sports-content distribution, but do not represent a material financial update for publicly traded operators.
Analysis
For PSKY, folding niche brands into the flagship app is principally a retention and marketing-efficiency lever, not a near-term revenue accelerator. The key economic test is whether the broader content bundle lowers gross subscriber churn enough to offset lost standalone pricing and brand-specific upsell; absent disclosure of migrated paid accounts, engagement, and advertising yield, the financial impact is not independently measurable. In the next 1-3 months, the market is more likely to focus on management's bundle strategy and content-spend discipline than on this individual product action.
The second-order beneficiary is the FAST/ad-tech ecosystem: as smaller sports and specialty services abandon direct-to-consumer economics, inventory and audiences migrate toward free, ad-supported distribution. ROKU and TTD are cleaner public proxies if this becomes a broader shift, while NFLX and DIS retain relative advantages because scale permits them to amortize sports, technology, and marketing costs across far larger subscriber bases. The contrarian risk is that consolidation can obscure rather than solve weak demand: if flagship-platform engagement does not rise, content rationalization merely lowers choice and reinforces consumer rotation among major services.
Over 6-18 months, the structural pressure remains on subscale DTC offerings and regional-sports economics, with rights owners likely favoring aggregation, wholesale licensing, or FAST distribution over standalone apps. For PSKY, a credible rerating requires evidence that consolidation improves DTC contribution margins without accelerating subscriber losses; otherwise, incremental app integration will not overcome the company's leverage, linear-TV decline, and content-investment burden.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.05
Ticker Sentiment
Key Decisions for Investors
- No standalone PSKY trade on this announcement; maintain a watch position only. Reassess after the next earnings release if DTC churn declines sequentially, ARPU holds, and management raises or reaffirms DTC profitability targets. A guidance cut or material increase in content cash spend falsifies the constructive consolidation thesis.
- Prefer a 3-6 month relative-value basket: long ROKU and/or TTD versus short a basket of subscale media exposure where available, rather than directional PSKY. The thesis is that migration toward FAST expands platform-level ad inventory and demand aggregation; exit if connected-TV ad pricing weakens materially or Roku platform revenue growth decelerates for two consecutive quarters.
- For PSKY holders, use any rally driven solely by brand consolidation as an opportunity to reduce exposure unless accompanied by disclosed migrated-subscriber retention and DTC margin data. The likely upside from lower marketing duplication is modest relative to the risk of lost standalone monetization and ongoing linear-network pressure.
- Monitor sports-rights distribution announcements over the next 6-12 months. Further movement from paid standalone services to aggregators or FAST would strengthen ROKU/TTD and pressure regional-sports and niche-DTC business models; a successful paid sports bundle with demonstrated low churn would challenge that view.
More News
- Analysis-Paramount pledges to release 30 films a year. How will that add up?
- Disney+ is raising prices for the 6th straight year — and Hulu is going up too
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- Here's what happens to the economy when Treasury yields soar like they are now
- Oil industry warns a diesel export ban will raise fuel prices as Trump weighs restrictions
- Meta's standoff with Amazon over Muse could be a sign of things to come
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More
- AI Tools for Family Offices: A Stack by Decision Type