
Birkenstock: Sector-Leading Growth At An Attractive Valuation
Source: seekingalpha.com
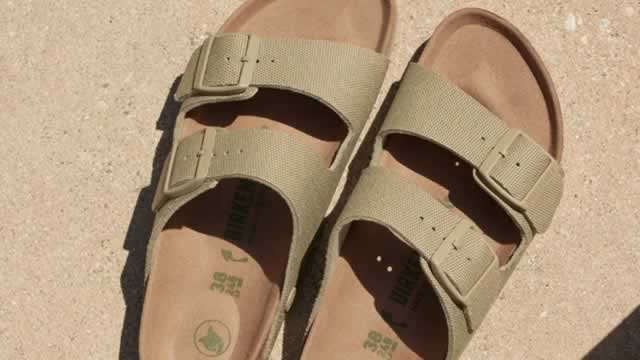
Birkenstock is characterized as undervalued at a 13.44x P/E despite sector-leading growth and profitability. Management is targeting 13–15% annual revenue growth through FY2028, supported by APAC expansion and growth in closed-toe footwear. The company’s functional-comfort positioning is viewed as supporting customer loyalty and repeat purchases.
Analysis
BIRK's valuation discount is unlikely to close simply because its reported P/E is low: investors remain focused on whether premium pricing can coexist with sustained unit growth as the brand broadens geographically and moves beyond its core open-toe assortment. The key earnings lever is mix, not just revenue: closed-toe penetration and direct-to-consumer expansion should raise annualized selling prices and gross margin if sell-through remains controlled, while wholesale growth alone would be less multiple-accretive. The principal competitive read-through is negative for mid-market comfort footwear, including CROX and SKX, where BIRK's premium brand positioning can take wallet share without competing primarily on price.
Over the next 1-3 months, the relevant catalyst is evidence that international growth is incremental rather than promotional: APAC inventory turns, DTC conversion, and gross-margin progression matter more than top-line guidance. A re-rating toward premium branded-footwear peers would require management to demonstrate that growth is not being bought through elevated marketing, distributor concessions, or excess inventory. The 6-18 month risk is that closed-toe expansion dilutes brand scarcity or creates a more seasonal inventory profile; a consumer slowdown would expose this quickly because discretionary footwear purchases can be deferred even when replacement demand is resilient.
Consensus may be underweight the strategic value of BIRK's controlled distribution model: limiting discounting can protect pricing power and reduce the markdown cycle that has impaired much of specialty retail. Conversely, the apparent valuation opportunity may be overstated if the cited P/E uses adjusted earnings or a temporarily favorable tax/interest profile; the investment case should be underwritten on normalized free-cash-flow conversion, inventory growth versus sales, and wholesale receivables rather than the headline multiple.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- Initiate a 6-12 month long BIRK position only after the next earnings release confirms revenue growth without inventory growth materially outpacing sales and preserves gross-margin progression. Target a peer-discount narrowing rather than a full peer multiple; risk/reward is attractive only if the position can be stopped on a guidance reduction or evidence of promotional activity.
- Use a relative-value expression: long BIRK / short CROX in equal beta-adjusted dollars over 3-6 months. The thesis is that BIRK's premium, controlled-distribution model should command better margin durability, while CROX has greater exposure to normalization in casual-footwear demand; exit if CROX's revenue reaccelerates while BIRK's DTC growth or gross margin decelerates.
- Do not buy upside calls until implied volatility and liquidity are reviewed. If post-earnings volatility is elevated, equity is preferable; if volatility compresses ahead of a report with APAC and closed-toe KPIs, consider defined-risk call spreads rather than outright calls.
- Set an earnings watchlist around three falsifiers: inventory-to-sales rising for two consecutive quarters, DTC mix declining while revenue growth remains high, or management reducing its multi-year growth framework. Any of these would indicate that the premium multiple thesis is weakening rather than merely delayed.
More News
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads
- Goldman’s Moe Says He’s in ‘Stronger-for-Longer Camp’ on AI
- Here’s the Tesla Semi… again
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly