
Zensar registered 4.1% sequential constant currency revenue growth for Q2FY27
Source: PR Newswire
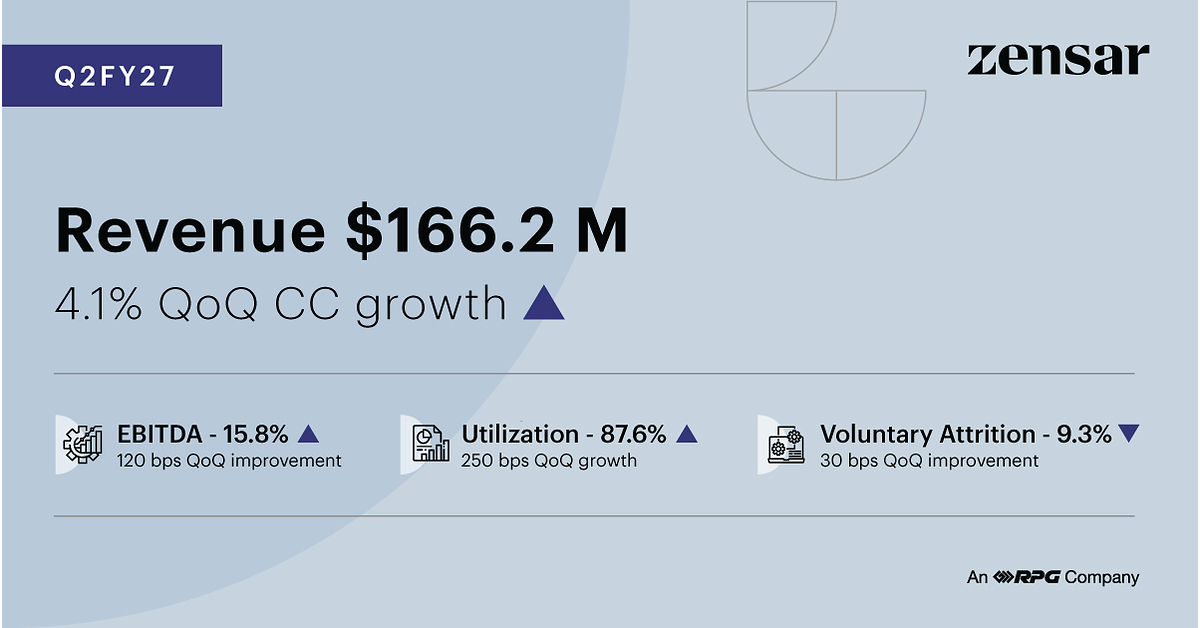
Zensar reported Q2FY27 revenue of $166.2M, up 4.1% sequentially in constant currency, with EBITDA margin rising 120 bps QoQ to 15.8%. Growth was broad across geographies, while results varied by sector: Banking and Financial Services grew 17.1% YoY, but Telecommunications, Media and Technology declined 21.6%. Management cited AI and digital-modernization demand; AI-influenced deals accounted for 36% of the quarter’s order book.
Analysis
The key signal is the divergence between improving near-term execution and uneven end-market demand. Margin expansion alongside sequential growth can support a near-term rerating if it reflects durable utilization, pricing or delivery efficiency; the release does not disclose enough to separate those drivers from mix or timing. Treat the AI order-book statistic as a leading indicator, not booked revenue: production conversion, contract economics and repeat business are the proof points. There is also a second-order risk that AI-led productivity compresses labor hours—and therefore revenue under time-and-materials contracts—unless Zensar can capture value through outcome-based pricing or expanded scope.
Growth is not yet broad in a durable sense: strong BFSI contrasts with sharp year-on-year weakness in TMT and healthcare/life sciences. That mix makes the result more vulnerable to a reversal in financial-services spending than the headline growth suggests. Over the next 1–3 months, client commentary and order conversion matter more than award language; over 6–18 months, the test is whether AI work expands wallet share without diluting billable demand or margins. The release supplies neither valuation nor detailed cash-flow, utilization, deal-conversion or guidance data, so a positive earnings reaction alone is not enough to underwrite a sustained multiple expansion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- Do not chase the AI narrative on this release alone. Before adding exposure, verify in the earnings call or next results whether AI-influenced bookings convert to revenue, and whether those projects carry comparable or better economics than legacy work.
- Keep Zensar on a conditional long watchlist rather than initiating a standalone position here: the setup improves if the next quarter sustains sequential growth and margins while TMT’s year-on-year decline stabilizes. Reassess if growth rolls over or margin expansion reverses; no price-based entry is supportable without valuation and market-price data.
- Monitor utilization, subcontracting and wage costs alongside revenue per employee or equivalent productivity disclosures. If margins retreat despite continued growth, the claimed operating leverage is not proving durable; if margins hold while AI revenue scales, the earnings-quality case strengthens.
- Treat the sector read-through as mixed, not a blanket bullish signal for Indian IT services: BFSI demand may support specialists, while persistent TMT and healthcare weakness argues against extrapolating Zensar’s quarter across peers.
More News
- Marvell to buy Lumentum in $115 billion deal in AI data-center bet
- Marvell, Lumentum tout historic $115B deal to create ‘category leader' in AI connectivity
- Palantir reports booming U.S. commercial revenue growth, topping government for first time
- Anthropic releases amended IPO prospectus with third-quarter financials
- Coinbase has been battered over the past month. Morgan Stanley says steer clear
- The AI boom is facing another supply crunch. This time it’s the amount of capital available to feed Silicon Valley’s endless need for cash