
Niutech schließt die Umstrukturierung der Unternehmensgruppe ab, um das chemische Recycling von Reifen und Kunststoffen voranzutreiben
Source: PR Newswire
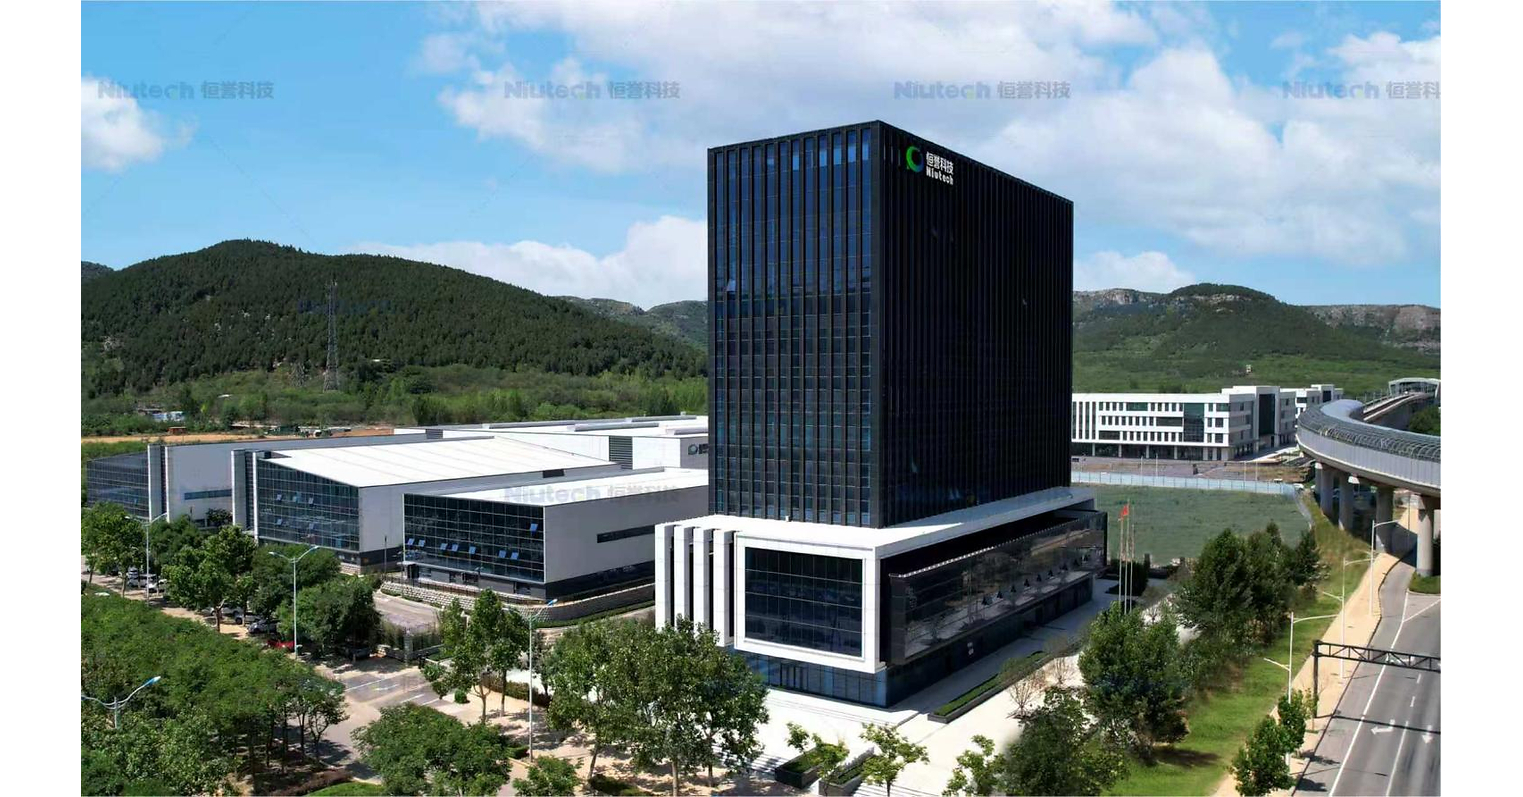
Niutech completed its group restructuring on August 26, 2026, broadening its registered business scope to include resource-recycling R&D, machinery and new materials. The company says its next-generation pyrolysis lines process more than 100 tonnes per facility per day; a 2026 Phase II project at majority-owned Hesheng Environmental Protection is expected to raise capacity to 160,000 tonnes per year. Niutech also reported a 198 million RMB order from a UK customer and said it is developing clean tire pyrolysis oil applications, including blending processes for sustainable aviation fuel.
Analysis
The investable question is not whether continuous pyrolysis works, but whether output qualifies as traceable recycled feedstock at economics that buyers can use. EU rules can pull demand forward, yet implementation, chain-of-custody accounting and product-quality acceptance may lag the headline regulatory direction. That creates a risk of capacity being built ahead of certified, bankable offtake.
The claimed UK order and operating history are useful diligence leads, not proof of recurring revenue or attractive returns. Verify contract scope, payment/milestone terms, customer identity, delivery schedule and whether the order is equipment revenue or includes ongoing services. Likewise, recovered carbon black meeting a stated test metric does not establish tire-maker qualification, consistent batches or price parity. If qualification succeeds, established tire producers could gain a lower-carbon input option; incumbent virgin carbon-black and fossil-derived feedstock suppliers face only a long-dated, volume-dependent threat.
Near term, restructuring itself is unlikely to establish earnings momentum. Over 1–3 months, order conversion, utilization and certification evidence matter more than nameplate capacity. Over 6–18 months, the upside case depends on repeat orders and offtake for pyrolysis oil; SAF blending is an option, not yet a demonstrated value stream, and may compete for capital and feedstock. The contrarian risk is treating regulatory ambition and a large plant as guaranteed demand. Any thesis weakens if project commissioning slips, utilization stays low, product acceptance fails, or cash collection lags reported orders.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Key Decisions for Investors
- No immediate trade on the restructuring announcement alone; the supplied data do not establish revenue conversion, valuation, liquidity or an independently verified earnings impact.
- Place Niutech on a diligence watchlist. Before taking exposure, seek audited segment economics, utilization and yield data, order backlog and cancellation terms, cash receipts against the UK contract, and third-party product qualification/offtake evidence.
- For a 1–3 month catalyst check, monitor commissioning and customer acceptance milestones for the 2026 expansion, alongside evidence that EU recycled-content rules recognize the relevant pyrolysis outputs. Treat delays or certification gaps as thesis-negative.
- For a 6–18 month read-through, track tire-maker qualification of recovered carbon black and repeat purchases of pyrolysis oil. Only then reassess potential substitution pressure on virgin carbon-black and fossil feedstock suppliers; falsify the upside case if utilization or repeat orders fail to rise.
More News
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Trump vows quick end to Iran war as fighting in Yemen intensifies
- Israel’s economy prospers despite years of war, but prices worry voters
- Verizon stock heads for worst day since 2002 as SpaceX U.S. network plans whack telcos
- SpaceX’s Wireless Threat Rises With Spectrum Deal
- ‘I drive a Tesla’: After Elon Musk said he’d lose his job, Delta CEO Ed Bastian says there’s ‘no tit for tat’ as airline unveils earnings miss