
DLC Sells Randhurst Village Following Transformative Leasing and Redevelopment
Source: PR Newswire
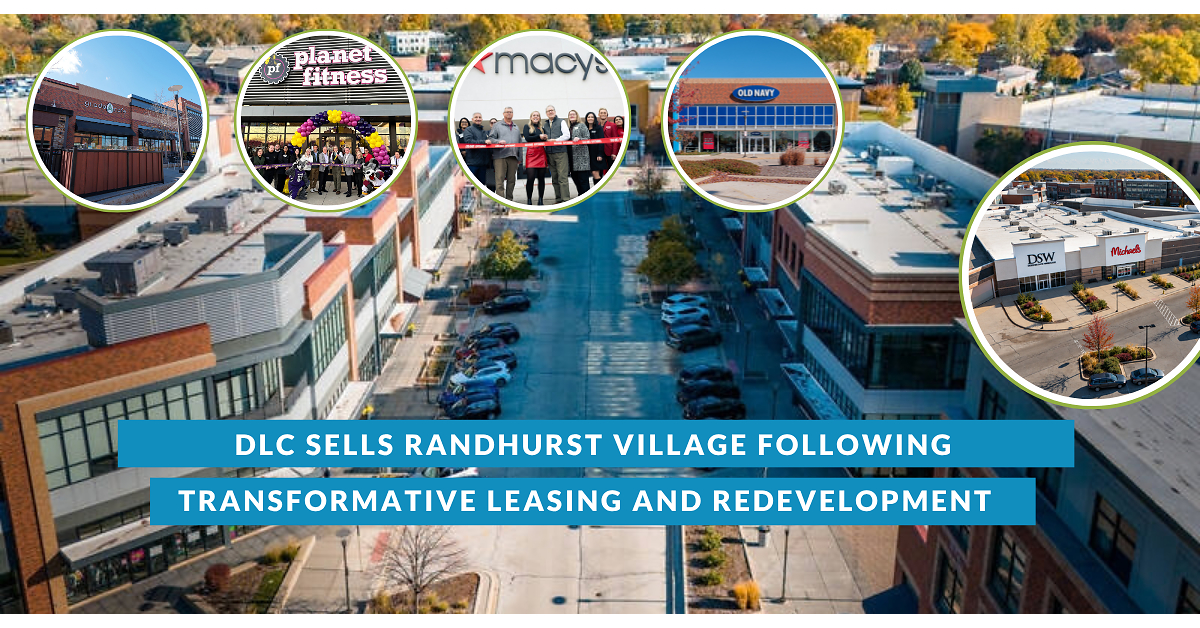
DLC sold Randhurst Village in Mount Prospect, Illinois, completing a value-add redevelopment strategy initiated after its 2016 acquisition; financial terms were not disclosed. The company converted a 200,000-square-foot former Carson Pirie Scott space into HomeGoods and Macy's, replaced a former Bed Bath & Beyond with Skechers and an upcoming Nike store, and expanded dining offerings. The sale validates DLC's active owner-operator strategy for repositioning open-air retail assets, though the absence of pricing limits assessment of realized returns.
Analysis
This is primarily a private-market price-discovery datapoint for necessity-led, open-air retail rather than an earnings catalyst for the named public tenants. A successful exit after vacancy remediation supports tighter cap rates for similarly grocery-, home-improvement-, and value-anchored centers, benefiting listed shopping-center REIT proxies such as KIM and REG; the effect should be strongest if sale price, NOI, and cap rate later demonstrate rents and traffic—not merely redevelopment spend—drove value creation.
The tenant mix is resilient to selective consumer spending pressure: COST and HD function as traffic anchors, while TJX and off-price peers typically gain share if discretionary demand weakens. NKE and M have a more nuanced read-through: replacing large-box vacancy with branded experiential/off-price-adjacent retail can improve store productivity, but it also reinforces landlords' negotiating leverage for scarce, high-traffic suburban locations. This is not sufficient evidence of a broad mall or department-store recovery; it instead highlights that obsolete boxes retain value only where conversion economics, demographics, and co-tenancy support replacement demand.
Over the next 1-3 months, obtain transaction terms before extrapolating. A cap rate below comparable open-air retail trades or a material premium to replacement cost would validate institutional demand and could support multiple expansion for KIM/REG; a high cap rate or seller financing would imply the exit was asset-specific. Over 6-18 months, refinancing costs remain the decisive constraint: elevated long-end Treasury yields can erase NOI-driven valuation gains for leveraged private owners even if leasing fundamentals remain firm.
Contrarian view: the press release emphasizes execution but omits realized IRR, stabilized NOI, occupancy, and buyer identity—the variables that determine whether this was genuine cap-rate compression or a one-off sale. Treat it as a watch signal, not a direct long catalyst for COST, HD, M, NKE, or PLNT, whose exposure to one location is immaterial.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- No direct position in COST, HD, M, NKE, or PLNT on this event; a single-center disposition has no measurable revenue or margin sensitivity for these issuers.
- Create an alert for disclosed sale price, cap rate, buyer, and financing terms over the next 30-60 days. If the implied cap rate is at least 50 bps below recent comparable grocery-anchored retail transactions, consider a 3-6 month long KIM versus short SPG pair; thesis is open-air retail valuation rerating versus enclosed-mall exposure.
- For a broader retail-real-estate expression, accumulate REG on any rate-driven pullback only if 10-year Treasury yields stabilize or decline; target 10-15% upside over 6-12 months from cap-rate support, with thesis invalidated by a sustained 50+ bp rise in long-end yields or material same-property NOI guidance deterioration.
- Monitor NMRK for fee-revenue confirmation rather than trade on the announcement. Repeated retail-disposition mandates and improved capital-markets backlog at the next earnings release would be needed to support a 6-12 month long; absent those disclosures, transaction fee contribution is too small and episodic.
More News
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly
- Costco tops estimates as discount gas, bulk deals draw inflation-weary shoppers
- Costco Wholesale Corporation Q4 Profit Rises
- Our top 10 things to watch in the stock market Thursday
- Nike Gears Up For Q1 Print; Here Are The Recent Forecast Changes From Wall Street's Most Accurate Analysts
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Introducing AllMind: A New Data & AI Workspace for Institutional Investors
- AI Tools for Private Equity Due Diligence: A Buyer Workflow