
Piramal Pharma renforce ses opérations prêtes pour l'avenir avec une réduction de 22,6 % des émissions, 41 % des énergies renouvelables et « zéro observation » de l'OAI par la FDA américaine
Source: PR Newswire
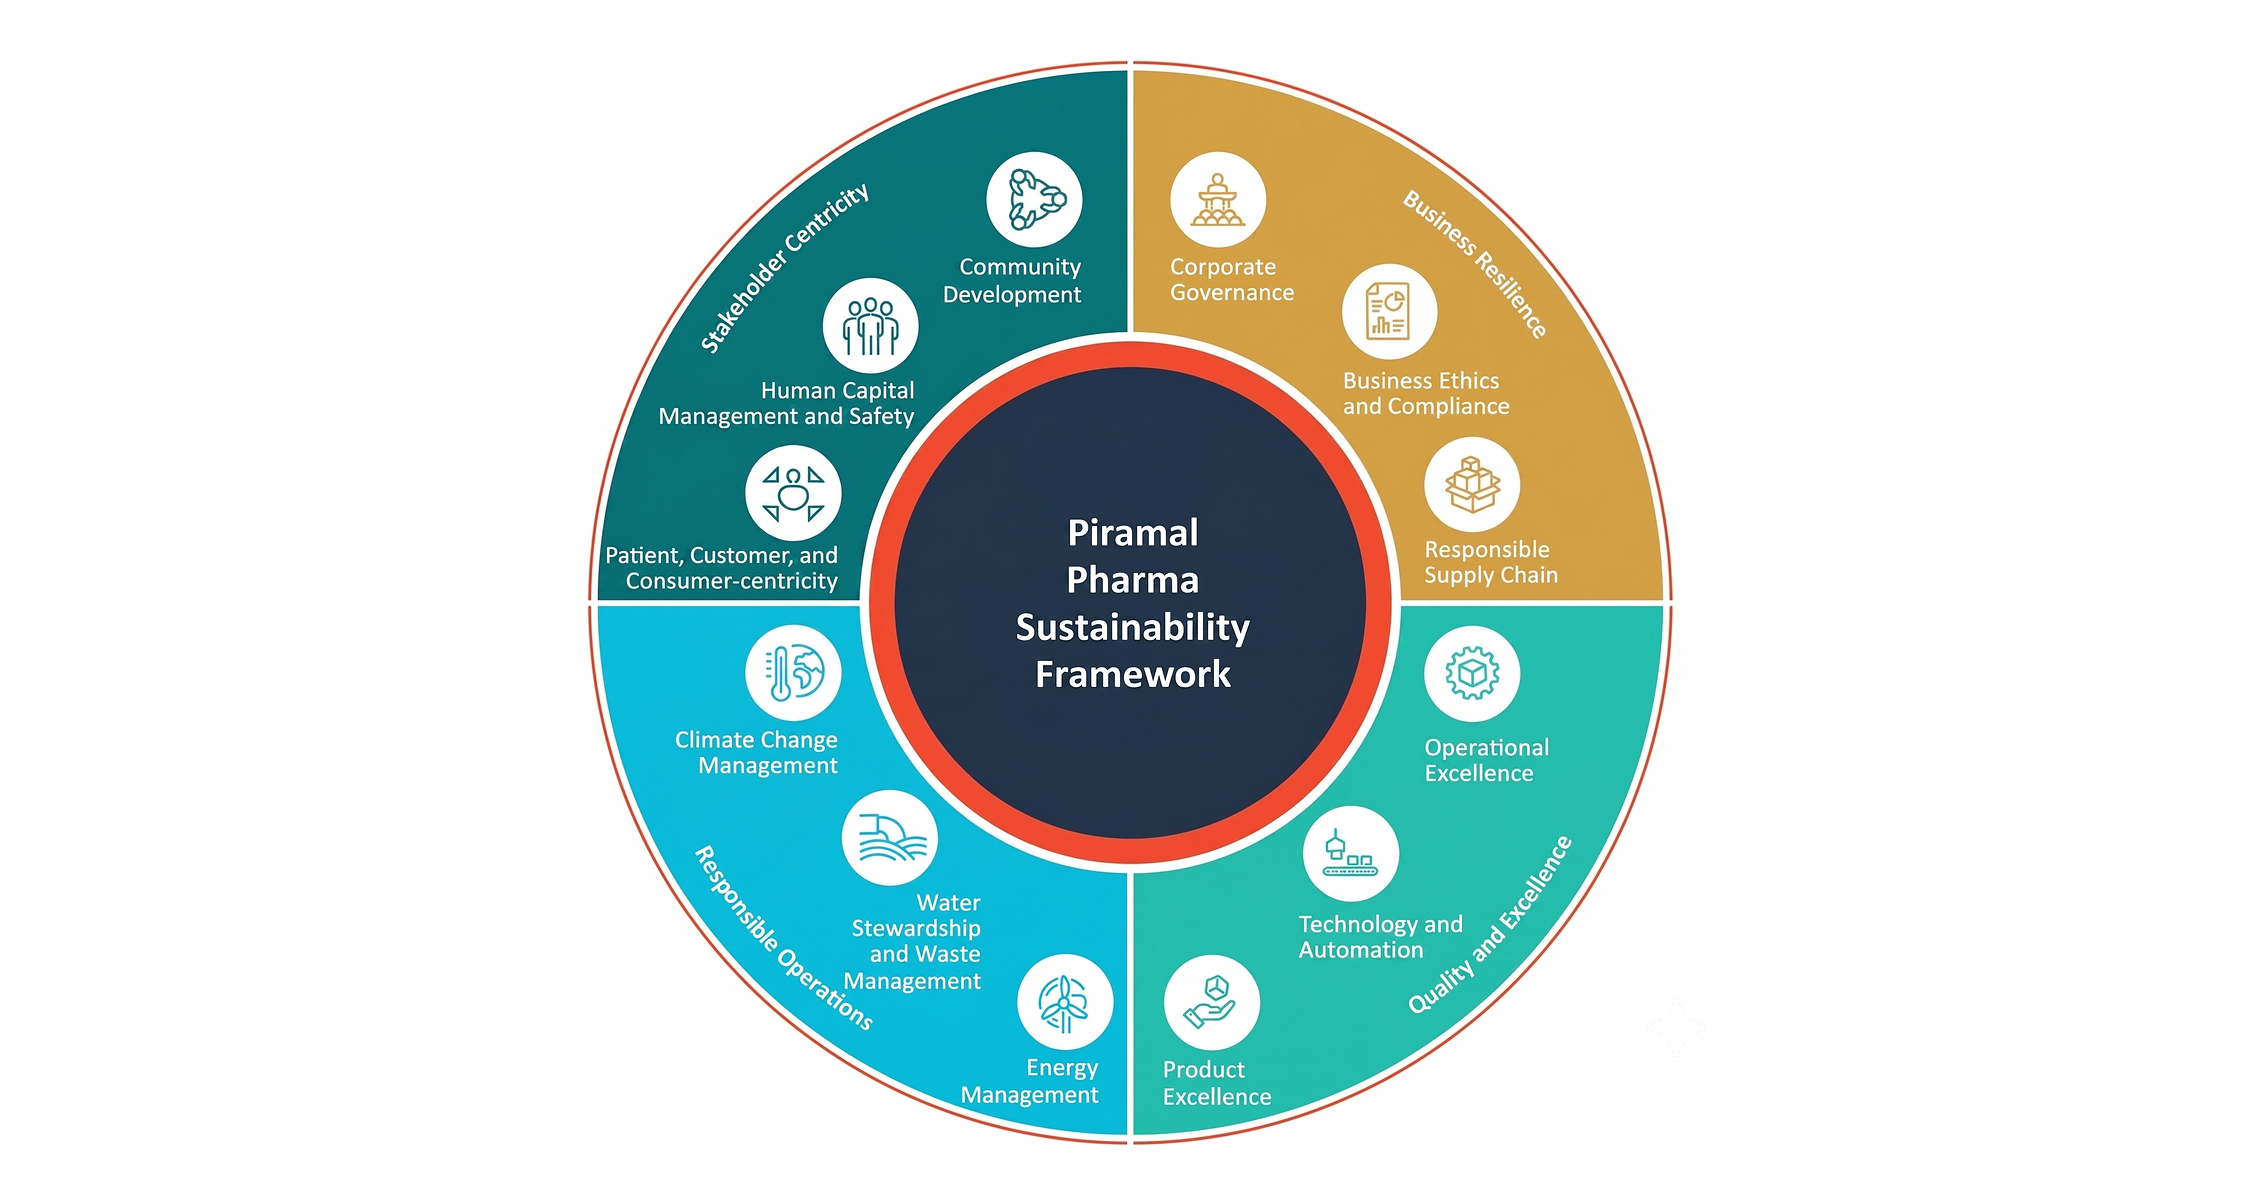
Piramal Pharma reported a key ESG milestone: Scope 1 & 2 emissions fell 22.6% vs the FY2022 baseline and renewable energy rose to 41% of total energy consumption. The company also cited FDA-related quality progress with three USFDA inspections and zero Official Action Indicated (OAI), alongside 38 regulatory inspections total and 100% ESG/code-of-conduct training coverage. Investment-level capex was disclosed at $90M to expand advanced therapeutic capabilities at Lexington and Riverview; overall, the report signals stronger operational compliance and sustainability execution rather than a direct earnings catalyst.
Analysis
This reads more like a de-risking update for Piramal’s manufacturing franchise than a valuation inflection point for ABBV. The economically relevant signal is not the ESG scorecard; it is the combination of clean FDA inspection history and continuing digital-quality investment, which lowers the odds of a remediation event, shutdown, or customer audit failure that could interrupt supply. For ABBV, the only plausible transmission is through the India ophthalmology JV, so the direct earnings impact is likely immaterial unless there is a disclosed change in JV economics or manufacturing footprint.
Second-order, the 90mm capex and higher advanced-therapy capacity are more interesting than the sustainability metrics because they could improve Piramal’s mix and customer stickiness in outsourced development/manufacturing. That matters for peers competing for CDMO work, but it does not obviously move ABBV’s core thesis, which remains driven by immunology/oncology execution rather than this supply-chain news. In the next 1-3 months, the market should treat this as a sentiment/quality-supportive item, not a catalyst.
Contrarian view: consensus may dismiss the release as boilerplate ESG messaging, but for pharma manufacturing the absence of regulatory friction is itself an option value. The true bearish case would be a future FDA observation, customer audit miss, or underutilization of the new capacity; absent that, this should not compress ABBV’s multiple or alter estimates. If anything, it modestly reduces tail risk around a small but strategically useful India platform.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Key Decisions for Investors
- Do not initiate a standalone ABBV trade on this release; the transmission to ABBV EPS is too indirect and likely immaterial over the next 1-3 quarters.
- If already long ABBV, hold through the next print; treat this as a minor supply-chain de-risking signal, not a reason to add size ahead of earnings.
- Set a watch item on any ABBV disclosure tied to the Piramal ophthalmology JV or India manufacturing localization; only a quantified change in revenue contribution or margin would justify revisiting the thesis.
- For pharma/CDMO baskets, prefer companies with demonstrated FDA-clean execution and customer-audit strength; if Piramal later shows meaningful advanced-therapy utilization, consider a relative long in the CDMO complex only after utilization data confirms the capex is revenue-accretive.
More News
- How Much Would You Need to Invest in These 5 Pharma Stocks to Earn $1,000 a Month in Dividends?
- Simply Injectables RI Welcomes Susan McKenna, NP, as Aesthetic Injector and GLP-1 Program Lead
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense vs Hebbia vs AllMind: Choose by Workflow
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace