
Pudu Robotics Launches PUDU GT Series, a Three-Model Lineup of Commercial Robotic Mowers for Professional Grounds and Turf Management
Source: PR Newswire
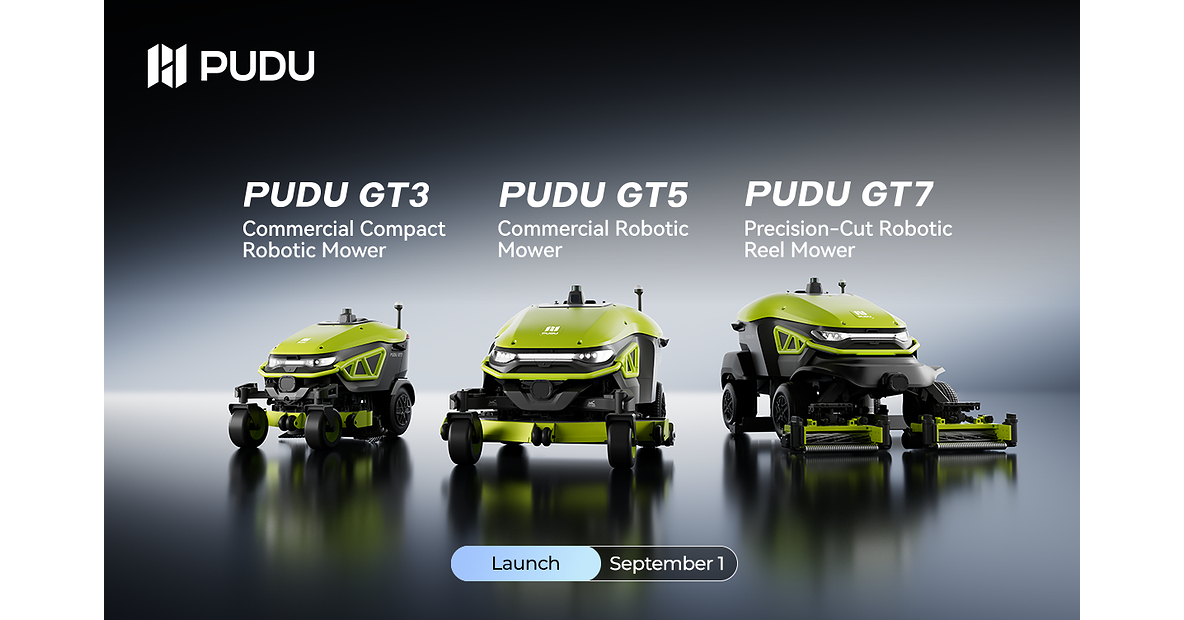
Pudu Robotics launched the PUDU GT Series—GT3 (36-inch), GT5 (60-inch) and GT7 (62-inch)—targeting distinct commercial mowing use cases from compact mixed sites to precision reel mowing for golf/sports turf. GT5 targets ~2 acres/hour and up to 10 hours runtime with coverage up to 16 acres on a charge, while GT7 uses RTK/LiDAR/camera vision for positioning accuracy up to ±2.5 cm and supports slope climbing up to 30 degrees. The company also highlighted an AI-native autonomy stack (LiDAR/vision/depth) across models and global debut at GaLaBau 2026, a positive product development with likely limited near-term pricing impact.
Analysis
This is less a near-term revenue catalyst than a proof point that autonomy is moving from indoor service robots into a labor-arbitrage category with recurring field support economics. If the platform works in messy outdoor environments, the value pool shifts away from pure mower hardware toward software, maintenance, fleet orchestration, and uptime guarantees — the same pattern that has historically compressed margins in commoditized equipment categories.
The first-order losers would be traditional turf and grounds OEMs with meaningful exposure to mid-tier commercial mowing, especially names like TTC and, to a lesser extent, DE and HUSQY, if buyers begin swapping labor hours for autonomy. The bigger second-order beneficiary may be landscaping contractors and facilities managers that can densify routes and reprice service contracts, because the initial savings come from fewer labor touches rather than from higher mowing ASPs. Premium golf-course and sports-field use cases are stickier; cut quality and liability slow displacement, so that segment is more of a demo channel than a near-term volume driver.
Near term, the market should treat this as a watch item: adoption will be gated by safety certification, edge-case performance, insurance, and procurement cycles, so any revenue impact is likely 2-4 quarters away at best. The contrarian view is that consensus may overestimate TAM because many customers already outsource grounds care; autonomy only matters if it lowers all-in cost after maintenance, supervision, and downtime. What would falsify the bullish thesis is a lack of paid deployments or repeat orders by the next earnings season, especially outside trade-show marketing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate position in INSO or TGT on this release; treat it as a monitoring item until there is evidence of paid deployments, channel inventory movement, or disclosed backlog.
- Set a 1-3 month alert on TTC and DE for commentary on autonomous grounds equipment adoption; if dealers or customers start citing pilot conversions, consider a tactical short TTC vs long DE pair, with the thesis that the more diversified OEM can absorb mix shift better.
- Do not chase the robotics theme via long-only industrial equipment today; the release is promotional until installed-base data appears. Reassess only if Pudu discloses repeat orders or service revenue in the next 2 quarters.
- If by the next earnings season there are named municipal, campus, or golf-course customers, consider a small short in traditional labor-intensive landscaping beneficiaries on any strength; the payoff is best if wage inflation remains sticky while autonomous uptime improves.
- Risk control: abandon any bearish view on TTC if the company reports autonomous attachment-rate growth or if channel checks show no pricing pressure in commercial turf equipment over the next 90 days.
More News
- AI Capex, Gamble or Jackpot?: Market Snapshot
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- Hybe shares jump 10% as K-pop sensation BTS' tour lifts earnings hopes
- Treasuries Soar as Tech Slump Threatens Growth
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Best AI Stock Research Tools for Professional Investors
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More