
Shinsung Materials Strengthens Competitiveness in the Functional Cosmetics Market with Differentiated Ingredient Technologies
Source: PR Newswire
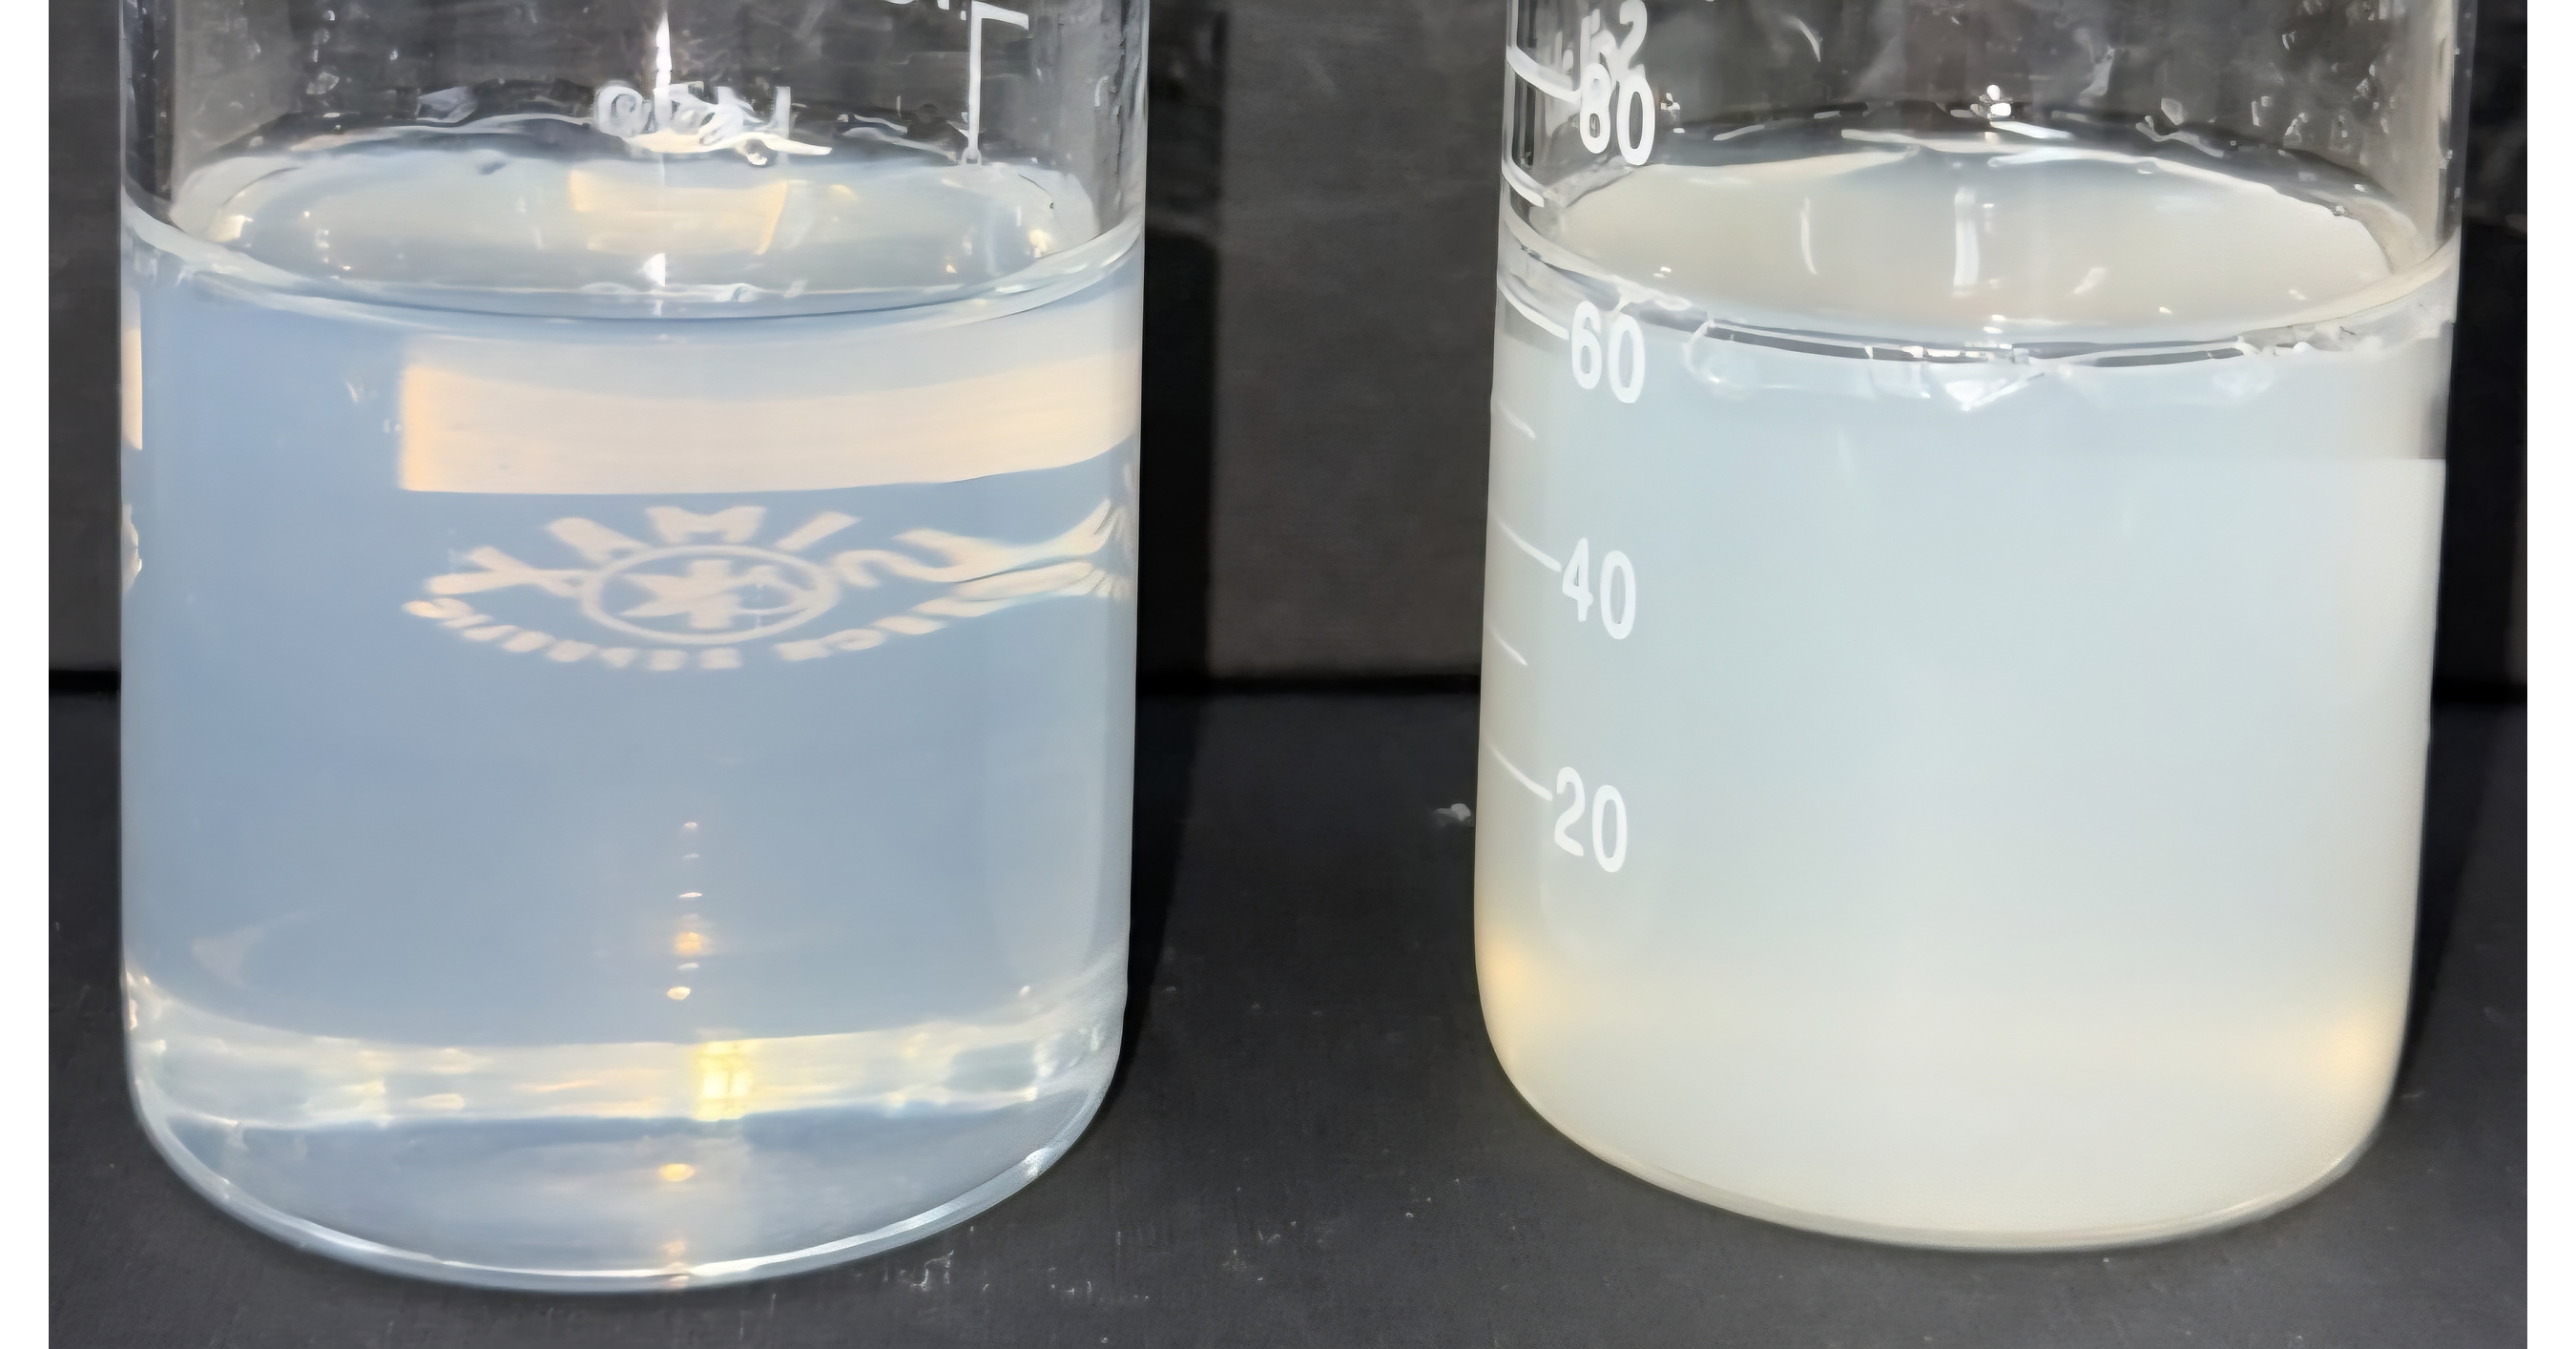
Shinsung Materials says it is strengthening its competitiveness in functional cosmetics by localizing water-soluble UV filters (TDSA) using a Korean patent (No. 10-1937332) and adding neutralization/powderization improvements to support storage and transportation. The company is also diversifying naturally derived oil gelling agents (e.g., Dextrin Palmitate and Stearoyl Inulin), highlighting COSMOS approval for OG-DP11 and advancing new R&D products OG-DP25, DM14, and DPE33 to broaden gel strength and texture options. Overall, the news is directionally positive, but it appears more product/strategy-focused than financially quantified.
Analysis
Meaningful equity read-through is not the supplier itself but the tightening of a small, sticky input bottleneck in premium skincare. A locally qualified source for water-soluble UV actives and natural gelling systems improves formulation optionality for K-beauty brands and CDMOs, which can translate into faster product cycles and less FX/import friction rather than an immediate step-up in category demand. Over 6-18 months, that tends to favor brands that monetize ingredient storytelling and frequent innovation, while commoditized mass-market players lose pricing power.
The first-order beneficiaries are consumer brands with premium/clean-label positioning and retailers that curate innovation; the second-order losers are legacy ingredient distributors and suppliers whose moat is logistics rather than specs. Because qualification and stability testing take quarters, the near-term catalyst is limited unless the company wins named OEM/ODM customers; until then, this is mostly an option on future share gains, not a visible P&L driver.
Contrarian view: the market may be over-crediting patents and certifications as if they were immediate barriers to entry. In cosmetics, formulation performance can be copied or substituted if the sensory profile is not superior at scale. The thesis breaks if there are no customer wins in the next 2-3 quarters, if clean-beauty demand cools, or if global competitors match transparency/gel strength at lower cost.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No actionable trade in GOOGL; this news has no direct revenue or multiple sensitivity for search/ads.
- Long ELF / short COTY over 1-3 months as a clean-beauty innovation pair; thesis is that ELF can capture more shelf share from ingredient-led product launches while COTY is more exposed to commodity brand compression. Stop if ELF guide cuts or COTY shows U.S. share gains.
- If you want a lower-beta expression, buy ULTA on pullbacks and pair against XLY underweights; cleaner formulations and faster newness cycles should modestly support prestige mix, but the move is likely small and should be treated as a tactical trade, not a structural call.
- Set an alert for any disclosed anchor-customer wins or commercialization timelines for the new ingredients; that is the real catalyst. Without that, the stock impact should remain de minimis.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.