
Angel Aligner ersetzt in Europa die „Torque Ridges" durch „Pressure Points"
Source: PR Newswire
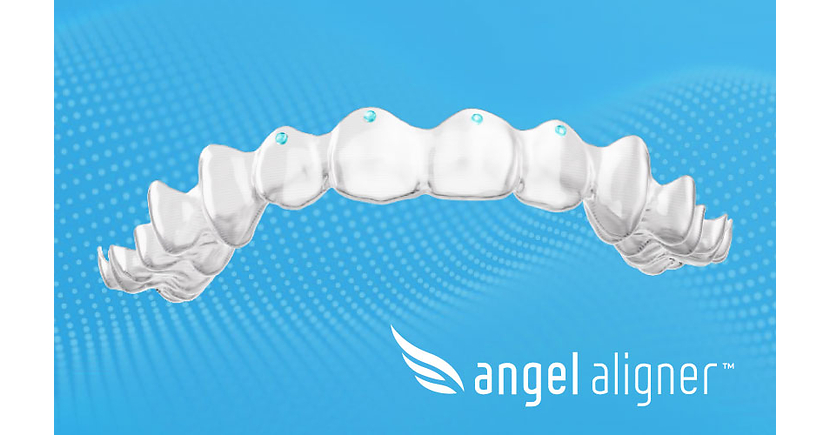
Angelalign Technology launched its new “Pressure Points” clear-aligner feature in Europe, replacing Torque Ridges for torque correction. The company says the single-pressure-point configuration increases tooth contact area by 25% and improves the predictability, precision and scalability of force application. A broader global rollout and future expansion into rotation and intrusion applications are planned, though no financial impact or sales targets were disclosed.
Analysis
This is a modest commercial-enablement signal for Angelalign (6699.HK), not yet an earnings catalyst. The relevant question is whether the feature improves case-completion rates, reduces mid-course refinements, or raises orthodontist retention—metrics that can support European scanner/case penetration and gross margin through lower clinical-support costs. A product claim around force predictability is not independently validated here; without published outcome data or clinician adoption metrics, the near-term revenue effect is likely immaterial.
Competitive pressure is marginally negative for Invisalign owner Align Technology (ALGN) and, to a lesser extent, Straumann (STMN.SW), whose clear-aligner offerings compete for orthodontist workflow share. The more material second-order benefit could accrue to digital-treatment-planning utilization: if standardized pressure points reduce manual intervention, Angel may scale lower-cost cases without proportionately expanding clinical labor. Conversely, a clinical-performance failure would be disproportionately damaging in Europe, where specialist endorsement and distributor relationships compound slowly.
Over the next 1-3 months, monitor European doctor onboarding, reported refinement rates, and any extension beyond the initial torque use case rather than reacting to the launch itself. Over 6-18 months, broader configurations could create a credible differentiation narrative only if they translate into faster treatment times or lower touch-up frequency; otherwise this remains feature parity in a market where ALGN's brand, installed base, and workflow integration dominate. The contrarian view is that the announcement may be more defensive than offensive: replacement of an existing mechanism may reflect an effort to close a clinical-gap perception rather than establish durable pricing power.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No standalone trade on this release. Maintain 6699.HK on watch for the next results cycle; upgrade only if European case growth accelerates while gross margin holds or expands, indicating the feature is improving conversion or clinical efficiency rather than adding support expense.
- For relative-value monitoring, track 6699.HK versus ALGN over a 3-6 month horizon. Consider long 6699.HK / short ALGN only after evidence of sustained European share gains and stable 6699.HK ASPs; absent those data, ALGN's installed-base advantage makes a pair trade premature.
- Set a downside alert for 6699.HK if management cites higher European training, clinician-support, or remediation costs without corresponding case-volume growth. That outcome would falsify the operating-leverage thesis and imply the launch is a cost center rather than a differentiator.
- Watch for independently presented clinical data on refinement rates, treatment duration, and adoption by orthodontic practices. A statistically credible reduction in refinements would be the key catalyst for a 6-18 month rerating; anecdotal marketing claims should not change positioning.
More News
- FAA says Boeing 737 Max software glitch not a flight-safety issue
- Your health insurance premiums may take a big jump in 2027 — here's why
- Anthropic to invest $100 million to train AI engineer talent
- Big Pharma turns to China for new drugs as patent cliff drives multibillion-dollar deals
- Why Lilly and Novo are betting on amylin to power a new wave of obesity drugs after GLP-1s
- Why AMD Stock Jumped 30% in September