
HABANOS, S.A. HAS UNVEILED THE MONTECRISTO FRAGATA, A NEW TRAVEL HUMIDOR EXCLUSIVELY FOR DUTY-FREE AND TRAVEL RETAIL
Source: PR Newswire
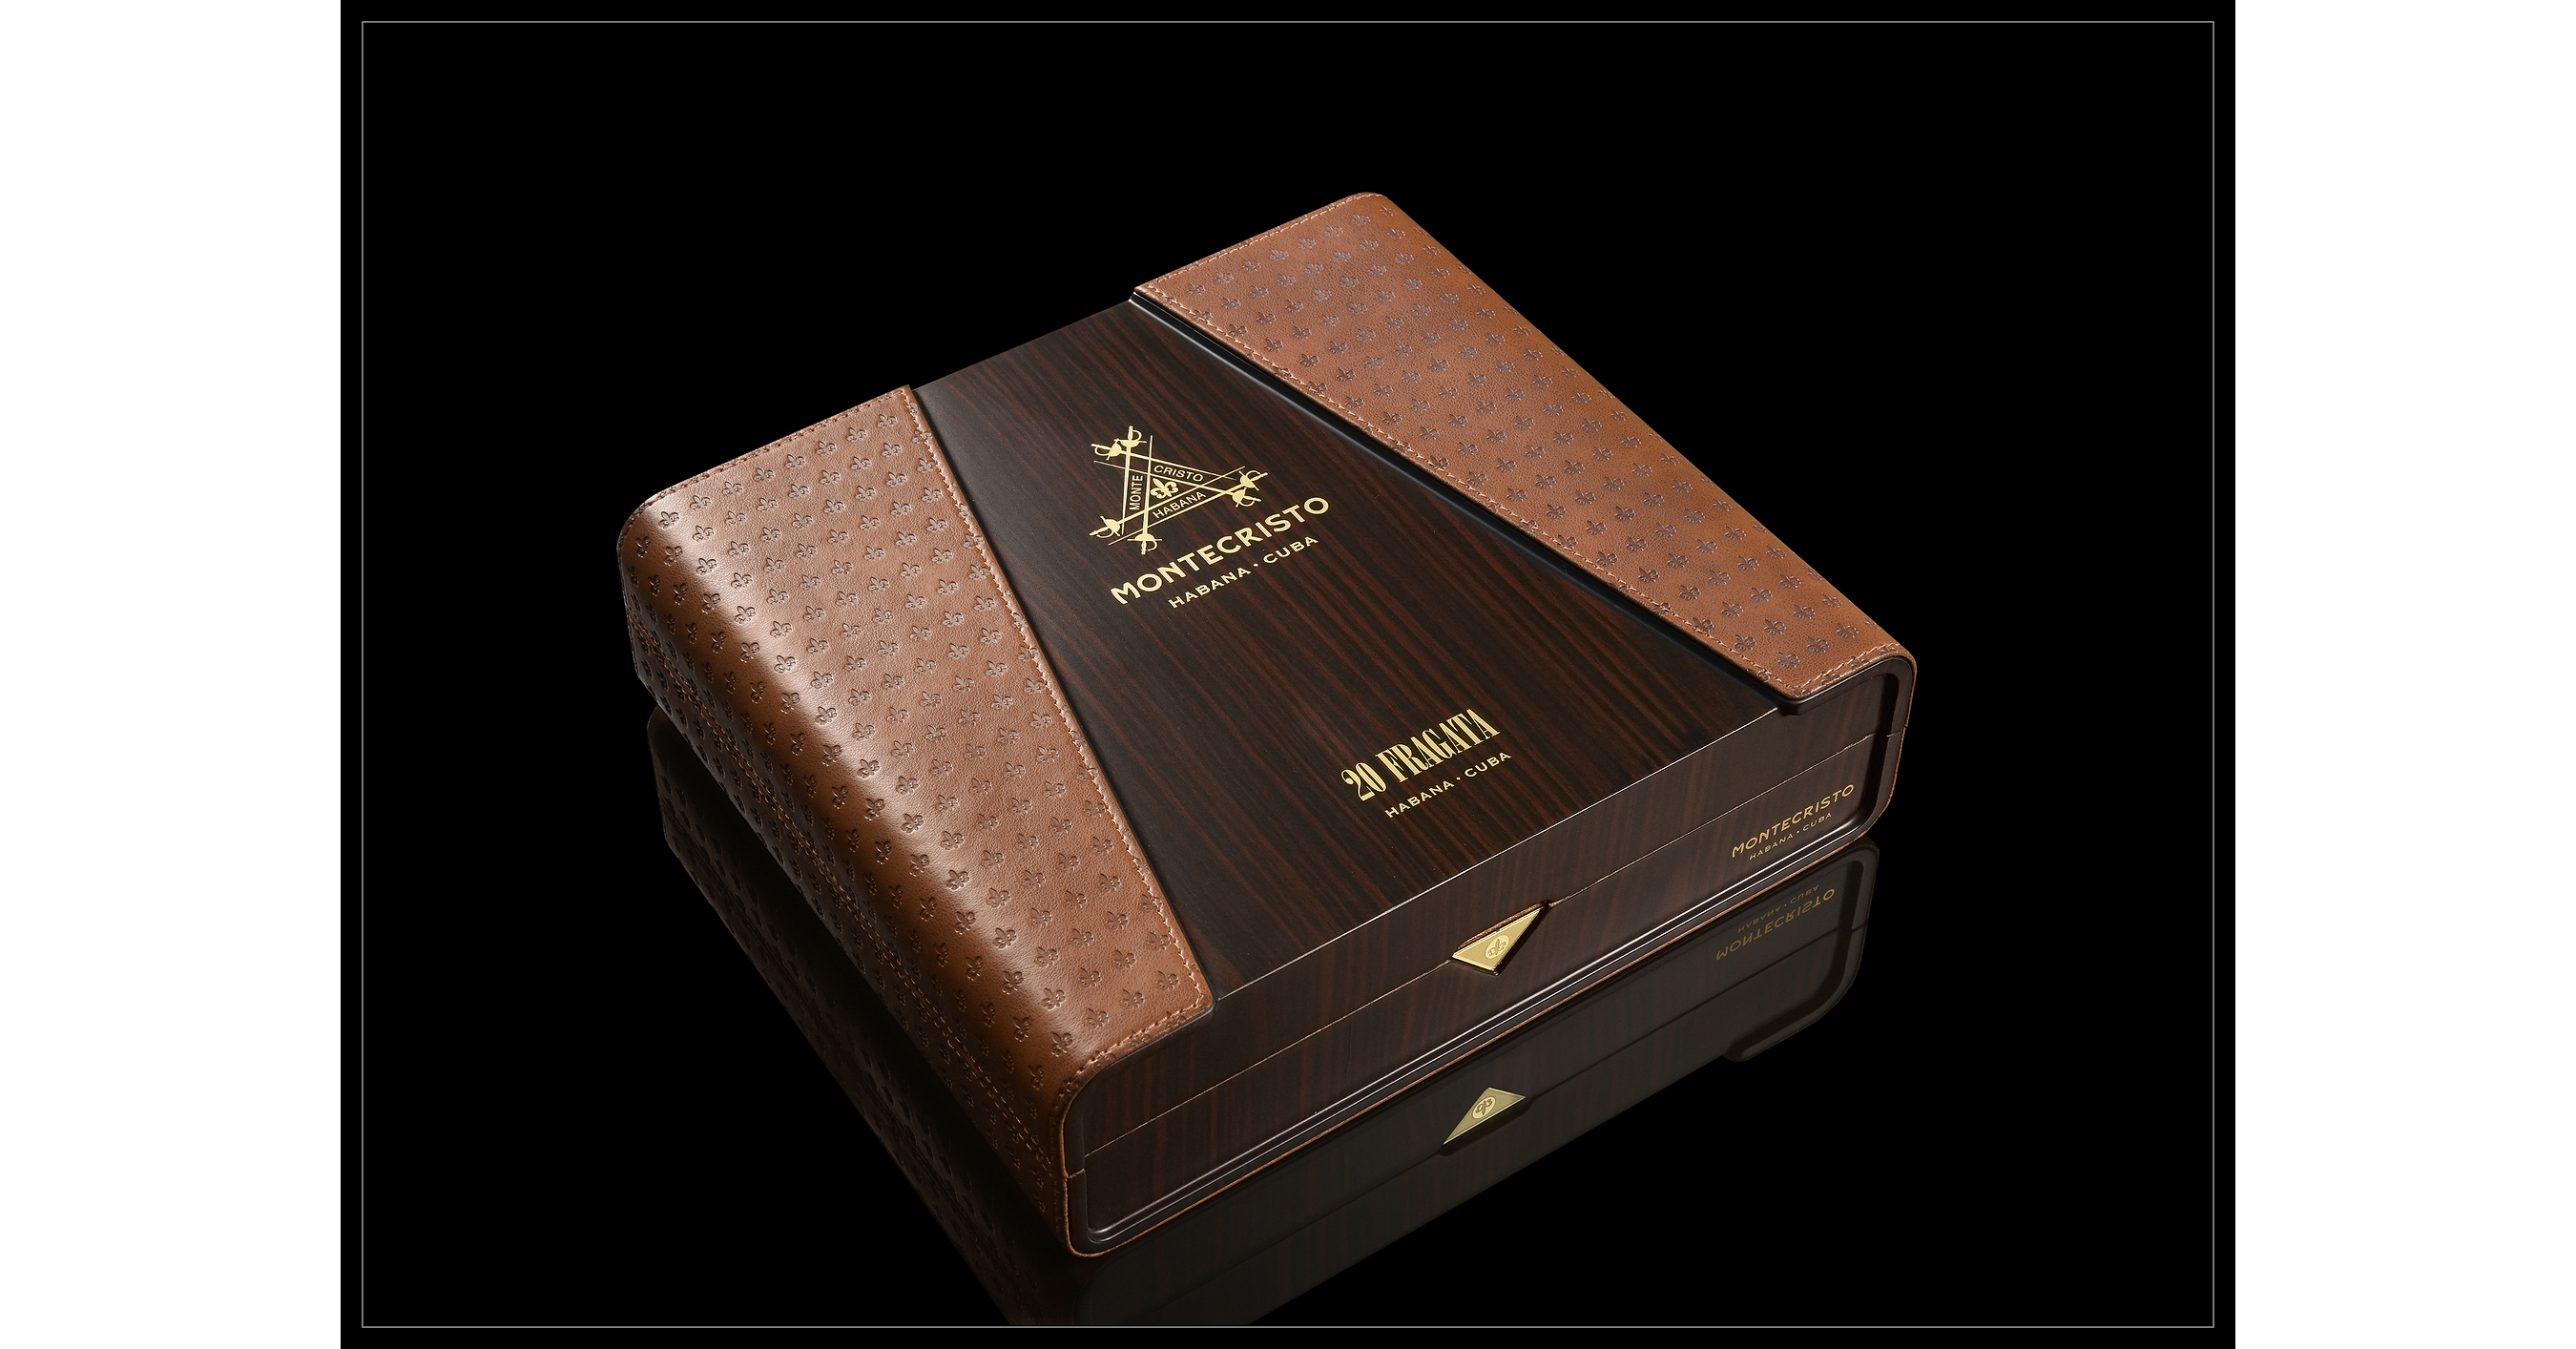
Habanos, S.A. launched Montecristo Fragata, a duty-free and travel-retail-exclusive luxury humidor containing 20 new Montecristo cigars. The Duke-format cigars carry recommended retail pricing of $64/€55 per stick, or $1,280/€1,100 per box. The launch extends Montecristo's premium travel-retail portfolio following the brand's 90th anniversary, but is unlikely to have broad market impact.
Analysis
This is not investable standalone news: Habanos is privately held and the launch is too limited to alter public-company earnings. The relevant signal is a high-end travel-retail demand test, where sell-through—not announced pricing—would indicate whether affluent international travelers remain willing to absorb discretionary luxury price points. Given capacity-constrained Cuban tobacco production, a successful limited release is more likely to improve product mix and brand pricing power than drive meaningful unit growth.
The closest listed read-through is travel retail rather than tobacco: Avolta (AVOL.SW) and Lagardere (MMB.PA) can benefit marginally if premium consumables are sustaining airport basket expansion, while China Duty Free (601888.SS) is a less direct proxy for luxury travel retail normalization. The second-order risk is that tighter airport restrictions on tobacco displays, rising excise duties, or weaker Chinese outbound travel make cigar launches a poor indicator of broader duty-free demand; tobacco is unusually regulation-sensitive and purchases are often inventory-driven.
Over the next 1-3 months, watch airport retail operators' reported spend-per-passenger and premium-category mix rather than extrapolating from a supplier press release. Over 6-18 months, resilient premium tobacco sell-through would support the broader thesis that luxury travel retail is shifting toward high-margin, scarcity-branded products, but it would not overcome passenger-volume weakness or regulatory pressure. No near-term directional equity trade is warranted absent disclosed order volumes, distribution footprint, or evidence of incremental airport traffic.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No standalone position: treat this as a qualitative demand datapoint, not an earnings catalyst, because neither Habanos nor its direct economics are publicly investable.
- Place AVOL.SW on a 1-3 month watchlist for premium spend-per-passenger commentary; consider a tactical long only if management confirms premium-category growth above passenger growth and maintains EBITDA guidance. Falsifier: a guidance cut tied to airport traffic or weaker transaction values.
- Use MMB.PA as a secondary travel-retail read-through rather than a direct cigar proxy; avoid initiating before quarterly travel-retail sales disclose whether mix gains offset volume. Falsifier: organic sales deceleration alongside deteriorating duty-free margins.
- Monitor China Duty Free (601888.SS) for Chinese outbound-travel recovery, but do not infer demand from this launch. A sustained rebound in outbound passenger data and luxury category sales would be needed before a long thesis is actionable.
More News
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
- Markets slip on dollar pressure, but this IT stock is up 10% today
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Research Workflows, Report Format Selection, and Interactive Synthesis
- Can ChatGPT Analyze a 10-K? A Verification Workflow