
A Medici Fortress, a Dubrovnik Cloister and the Tower of London After Dark: Windstar's New 2027 Experiences
Source: PR Newswire
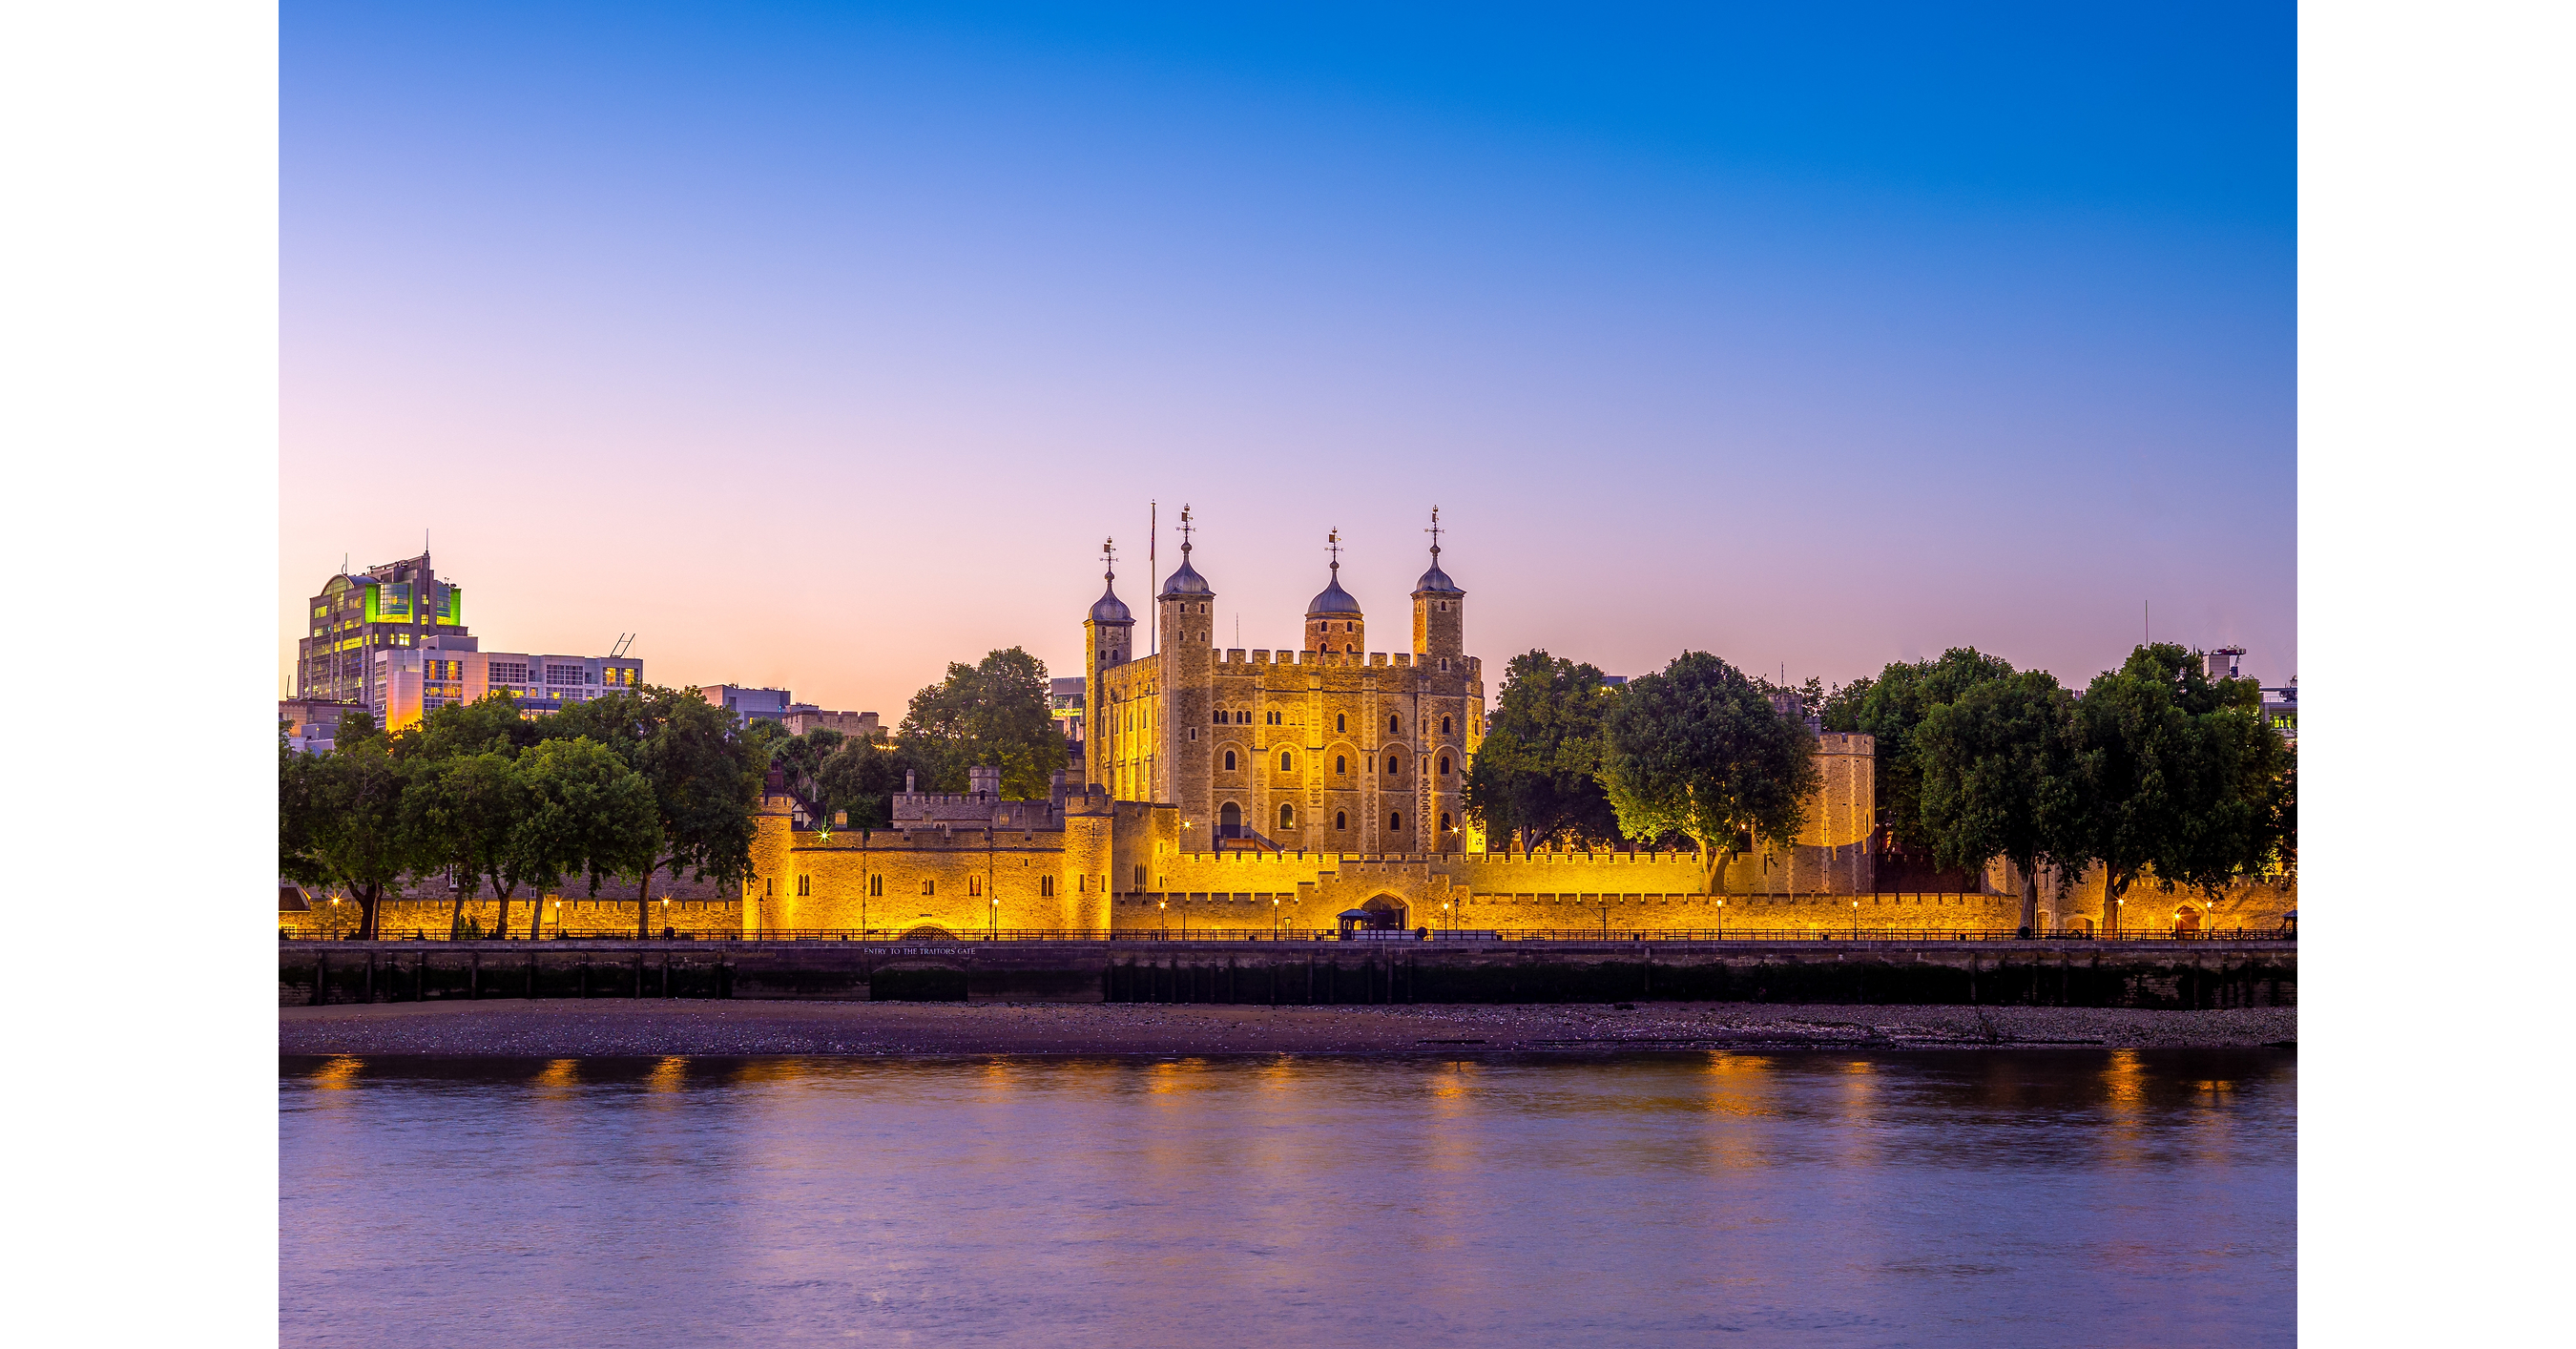
Windstar Cruises announced seven complimentary Destination Discovery Events across seven destinations for 165 sailings in 2027, more than doubling fleet coverage. The expansion coincides with the inaugural European year of the 224-guest, 112-suite Star Explorer, which debuts on December 28, 2026. New offerings include limited after-hours Tower of London access on three sailings, alongside events in Livorno and Dubrovnik, supporting differentiation in the premium small-ship cruise market.
Analysis
This is not a standalone valuation catalyst for AEG: the travel/entertainment subsidiary is privately held within Anschutz, and the parent is not a practical public-equity proxy. The relevant read-through is that premium small-ship operators are competing on curated port access rather than berth capacity, a product feature that can support pricing and onboard/shore-excursion attachment while avoiding the discounting typical of mass-market cruise inventory. The financial impact depends on whether these inclusions lift net yields enough to offset higher fixed event and destination-access costs; the release supplies neither pricing nor booked-load data.
Over the next 1-3 months, this is best viewed as a demand and revenue-management watch item for publicly traded luxury-cruise proxies rather than a direct trade. Viking Holdings (VIK) is the closest listed beneficiary if differentiated cultural access validates demand for destination-led, smaller-format itineraries; Norwegian Cruise Line (NCLH) has limited direct exposure through Oceania, while Carnival (CCL) and Royal Caribbean (RCL) remain structurally disadvantaged in restricted-access ports but retain scale economics. A broader premium-experience shift could modestly widen the yield gap in favor of VIK and NCLH/Oceania over mass-market operators across 2027 booking cycles.
The contrarian view is that complimentary programming is principally a marketing expense and may signal rising acquisition costs or an effort to fill shoulder-season Europe capacity, not pricing power. The thesis is falsified if luxury operators report stable booking volumes but lower net yields, elevated promotional spend, or weaker excursion margins during 2027 wave-season reporting. No direct AEG trade is warranted given the lack of public exposure and immaterial disclosed economics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No position in AEG: treat it as non-actionable because Anschutz/Xanterra is private and no separately traded operating asset captures the economics.
- Add VIK to a 2027 Europe-booking watchlist; consider a long only after management demonstrates premium European net-yield growth and booked-load strength in the next two quarterly updates. Target a 6-12 month horizon; exit on a material cut to yield guidance or evidence that promotional intensity is rising.
- Monitor a potential VIK long / CCL short pair into 2027 wave-season booking disclosures if destination-led itineraries show a measurable yield premium. Require confirmation from comparable net-yield guidance before entry; the key risk is resilient mass-market consumer demand and CCL's greater operating leverage to lower fuel costs.
- For NCLH, watch Oceania booking and pricing commentary rather than buying the parent solely on this news. Escalate only if management identifies premium-brand yield outperformance sufficient to move consolidated guidance; otherwise the signal is too diluted by Norwegian and Regent.
More News
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- RBC Capital cuts Sprouts Farmers Market stock rating on margin concerns
- Google's Gemini 4 Carbon looks like a diamond in the rough
- KION Q3 adjusted EBIT misses forecast as weak truck orders prompt guidance cut
- Microsoft’s strong quarter backs up its stock rebound. Here's our new price target
- As Waymo expands overseas, it remains a niche cash-burning business