
Reducto Opens New York City Office to Expand East Coast Presence
Source: PR Newswire
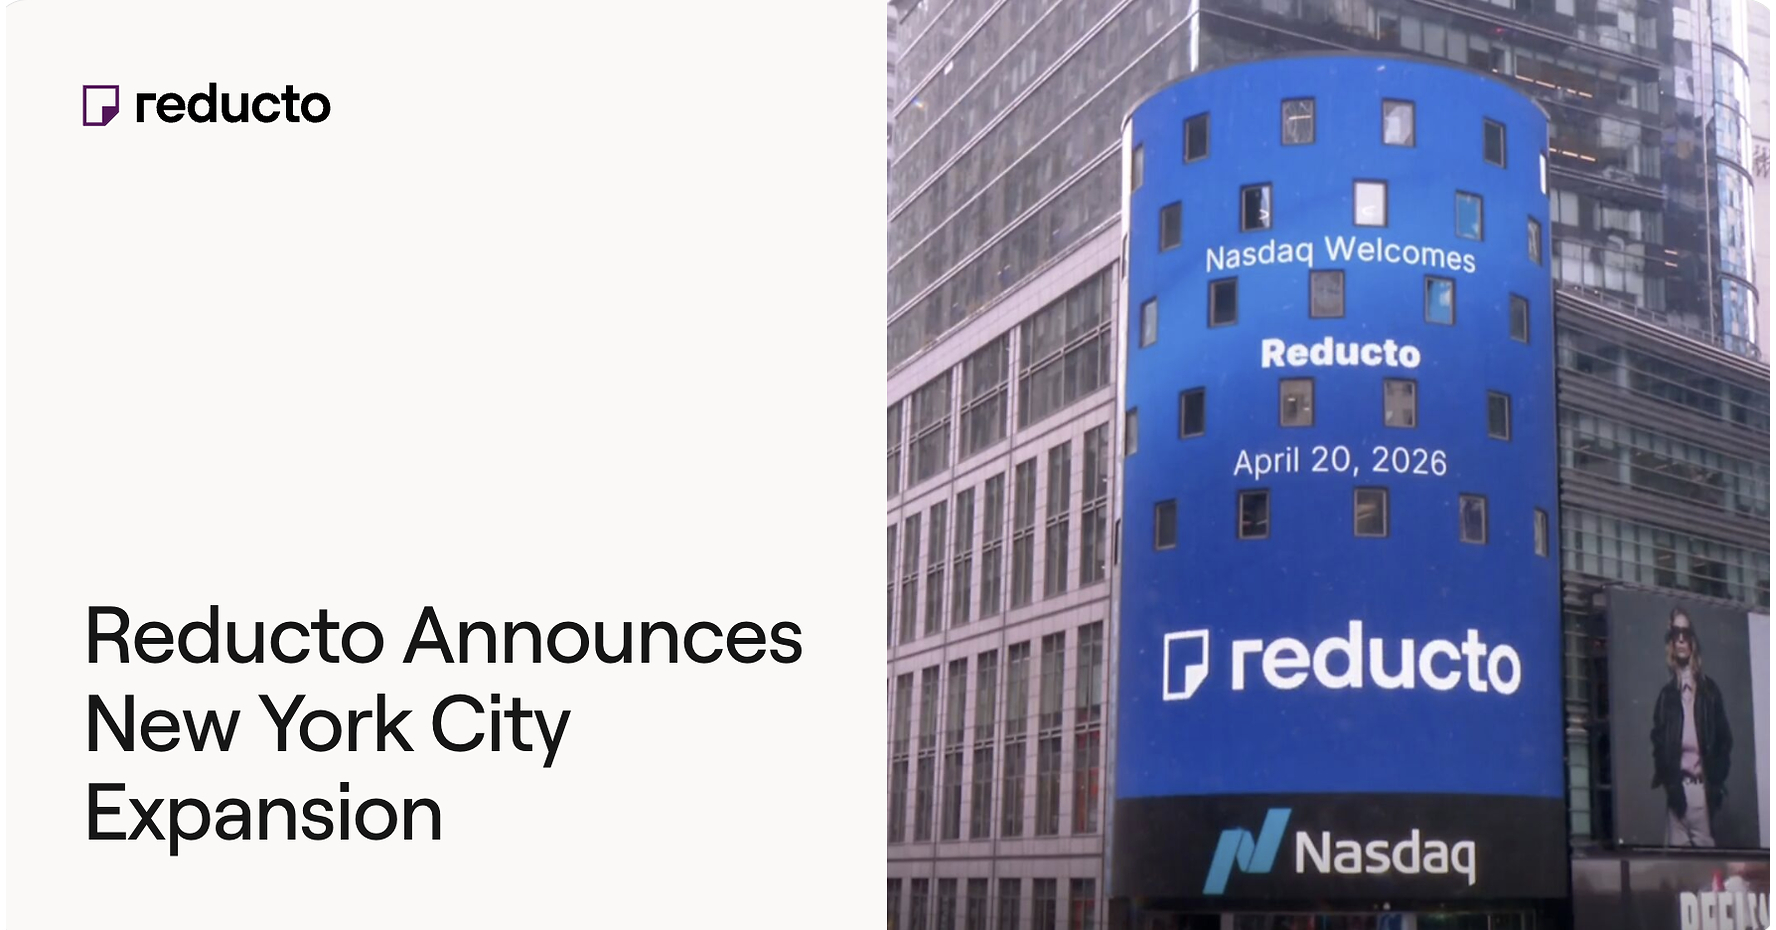
Reducto opened a New York City office to expand its East Coast enterprise presence and support growing demand for its AI document-intelligence platform. The company says it has raised more than $108 million, processes billions of pages for large enterprises and AI teams, and recently launched its r-1 unified parsing model. Reducto is hiring enterprise sales, business-development and solutions-engineering staff in New York, signaling continued commercial expansion.
Analysis
This is not a revenue-relevant catalyst for TOST. The only investable read-through is that document-ingestion tooling is becoming a more mature enterprise-AI layer, which could reduce implementation friction for vertical software vendors whose workflows depend on extracting data from invoices, onboarding forms, merchant statements, and compliance documents. For TOST, any benefit is indirect: faster and cheaper document automation could marginally support product velocity or merchant-support efficiency, but the vendor relationship, contract economics, and deployment scope are undisclosed.
The more important competitive implication is for private document-AI vendors and incumbents such as ABBYY, UiPath (PATH), and cloud AI platforms from Microsoft (MSFT), Alphabet (GOOGL), and Amazon (AMZN). A well-funded specialist gaining enterprise distribution can pressure standalone automation pricing, while hyperscalers retain an advantage where customers prioritize integrated security, model hosting, and procurement simplicity. This is a multi-quarter market-structure issue, not a near-term public-equity earnings driver.
Consensus should resist treating customer logos or page-volume claims as proof of durable monetization. Document-AI deployments often have high services intensity, long security-review cycles, and accuracy liability; scaling sales headcount can raise burn ahead of repeatable software gross margins. The thesis becomes investable only if subsequent disclosures establish contracted recurring revenue, net retention, and evidence that deployments displace rather than complement incumbent OCR/RPA stacks.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No directional TOST trade: the disclosed development has no stated commercial linkage to Toast and should not alter near-term revenue or margin estimates.
- Maintain PATH as a watch-list short candidate versus MSFT over the next 6-12 months if document-AI specialists and hyperscalers increasingly bundle extraction capabilities; require evidence of automation pricing pressure, weaker net-new ARR, or reduced guidance before initiating.
- For AI infrastructure exposure, prefer MSFT or AMZN over private document-AI thematic proxies on a 6-18 month horizon: enterprise buyers may consolidate document workflows into existing cloud/security estates. Falsify if specialist vendors demonstrate materially faster implementation and sustained premium pricing.
- Set an alert for independently reported Reducto ARR, gross margin, and large-enterprise contract disclosures. Absent those data, treat expansion announcements as hiring and distribution signals rather than evidence of an investable demand inflection.
More News
- What Would It Take for Investors to Pay More for Toast Stock?
- Australia’s central bank chief warns inflation risks materialising
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- Asian stocks rise as oil retreat eases inflation fears, BOJ in focus
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal
- California AG Bonta on Paramount-Warner Bros., Meta and AI
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research