
Built Beyond Trends: Global K-Beauty Brand AXIS-Y Enters Its Next Growth Chapter with MBK Partners at a KRW 430 Billion Valuation
Source: PR Newswire
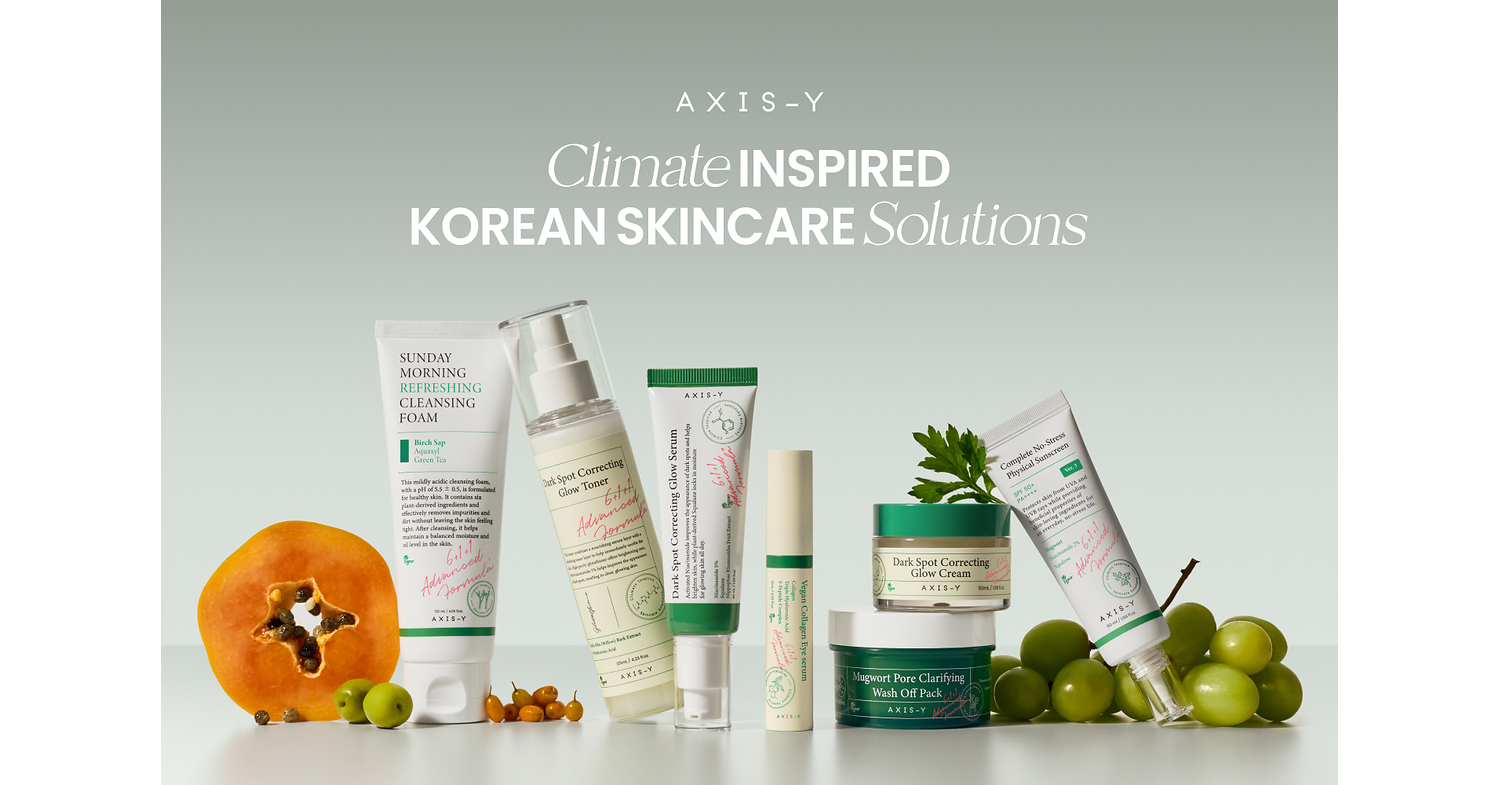
MBK Partners will acquire a 40% minority stake in vegan skincare brand AXIS-Y for approximately KRW 172 billion, implying an enterprise valuation of about KRW 430 billion. Founder management will retain 60% ownership and operational control of the profitable company, which generates more than 90% of revenue outside Korea, operates in roughly 100 countries, and has sold over 20 million units of its hero serum. The investment will fund international distribution, expansion into haircare and beauty devices, and AI- and data-driven consumer, forecasting and operational capabilities.
Analysis
This is a private-market price-discovery event rather than a direct public-equity catalyst. The implied valuation can support sentiment toward export-led Korean beauty brands, but it is not usable as a sector multiple without AXIS-Y’s revenue, gross margin, channel mix, repeat-purchase rate, and customer-acquisition costs. The key second-order question is whether incremental capital shifts spend toward owned international distribution and brand marketing—pressuring smaller digitally native K-beauty peers’ customer-acquisition economics—or toward outsourced manufacturing, which would benefit the unidentified Korean OEM/formulation supply chain.
For listed incumbents, the read-through is mixed. AMOREPACIFIC (090430 KS) and LG H&H (051900 KS) gain modest validation that overseas demand can support premium brand equity, but a globally scaled independent brand is more likely to fragment share in fast-growing online and specialty-retail channels than to lift their sales directly. COSMAX (192820 KS) and KOLMAR KOREA (161890 KS) are the cleaner potential beneficiaries only if they are confirmed suppliers; absent disclosure, treating them as beneficiaries is speculation rather than an investable conclusion.
Over the next 1-3 months, watch for distributor listings, retailer partnerships, hiring, and category-launch announcements: these would indicate whether the capital is being deployed into demand creation or merely balance-sheet strengthening. Over 6-18 months, expansion beyond skincare raises execution risk materially; devices and haircare require different regulatory, inventory, and return-rate capabilities, while a founder-controlled structure may reduce the probability of a near-term liquidity event. The contrarian view is that the transaction may be more a scarcity-premium private valuation than evidence of broad public-market rerating, particularly if growth is concentrated in one SKU or promotion-heavy marketplaces.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Key Decisions for Investors
- No immediate directional trade in Korean beauty equities: the news lacks disclosed financials, supplier identity, and public comparables; do not extrapolate the private valuation into listed-sector upside.
- Create a 1-3 month alert on COSMAX (192820 KS) and KOLMAR KOREA (161890 KS) for any disclosed AXIS-Y manufacturing relationship. A confirmed supply contract plus capacity commentary would support a tactical long; falsify if incremental orders are immaterial relative to annual sales or require margin-dilutive capacity additions.
- Maintain a relative-value watch: long COSMAX (192820 KS) versus short AMOREPACIFIC (090430 KS) only if independent K-beauty export data accelerate while large-brand overseas guidance remains flat. The thesis is OEM volume leverage versus branded share fragmentation; exit on an AMOREPACIFIC international-sales acceleration or a COSMAX utilization/margin miss.
- Monitor CJ Corp. (001040 KS) and Olive Young channel data for evidence that international-first brands are gaining domestic shelf space. A sustained shift toward indie brands could pressure legacy-brand promotional intensity, but this remains a channel signal rather than a current recommendation.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.
- Volvo Cars to cut 2,500 jobs as third quarter swings to loss
- Citizens raises Enova stock price target on strong growth outlook
- Debenhams returns to profit as turnaround gains traction, shares gain