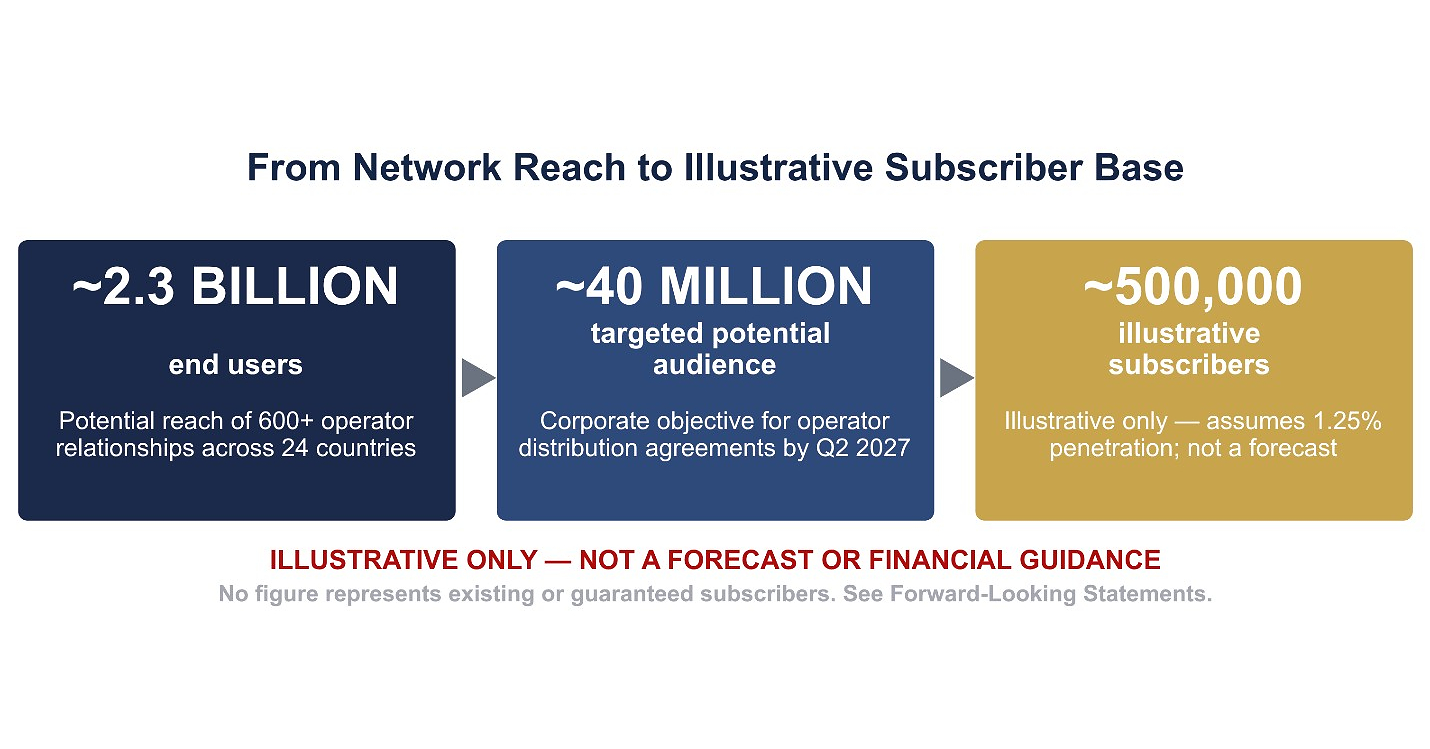
IQSTEL launched an IDILIO TV mobile-operator distribution sales pipeline targeting ~40 million potential mobile users by end-Q2 2027, leveraging its existing relationships with 600+ telecom operators across 24 countries. The company is modeling ~500,000 gross paying subscribers by end-2027 at a 1.25% penetration rate (illustrative, churn not included) and expects premium digital content to drive higher margins than wholesale voice/SMS. IQSTEL also reported preliminary unaudited H1 2026 revenue of ~$207M vs ~$130M in H1 2025. The IDILIO TV initiative is backed by a $5M seed round led by a16z Speedrun.
The economic read-through is not that IQST has discovered a new growth engine; it is that it may have found a lower-friction sales channel for an asset-heavy, low-margin telecom base. That can improve the narrative fast, but the first-order question is revenue share: if operators take a meaningful cut for billing, bundling, and promotion, the margin expansion may be far smaller than the press release implies. In other words, this is more likely to be a distribution arbitrage than a structurally new profit pool.
The likely winners are mobile operators that can bolt on a retention product without creating content, while the main losers are other microdrama startups and regional OTT apps that must buy traffic the hard way. The second-order effect is that carrier billing can shorten conversion cycles in undercarded markets, but it also concentrates bargaining power in the hands of operators, which can cap economics and force minimum guarantees. For IQST, the important issue is not audience reach; it is whether the company can convert that reach into disclosed paid subscribers without diluting gross margin or leaning on extra capital.
The market may overrate the signal because the seed-round investor list validates the content venture, not IQST's take-rate. Over the next 1-3 months, the stock will trade on whether management can convert pipeline language into signed operator agreements, paid-user data, and recurring digital-services revenue that is material to consolidated EBITDA. If those metrics do not appear by the next reporting cycle, the move is likely to fade and financing risk becomes the dominant story again.
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialOverall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
