
Kerry Celebrates Official Opening of State-of-the-Art Coffee Extraction Facility in Bethlehem, Pennsylvania
Source: PR Newswire
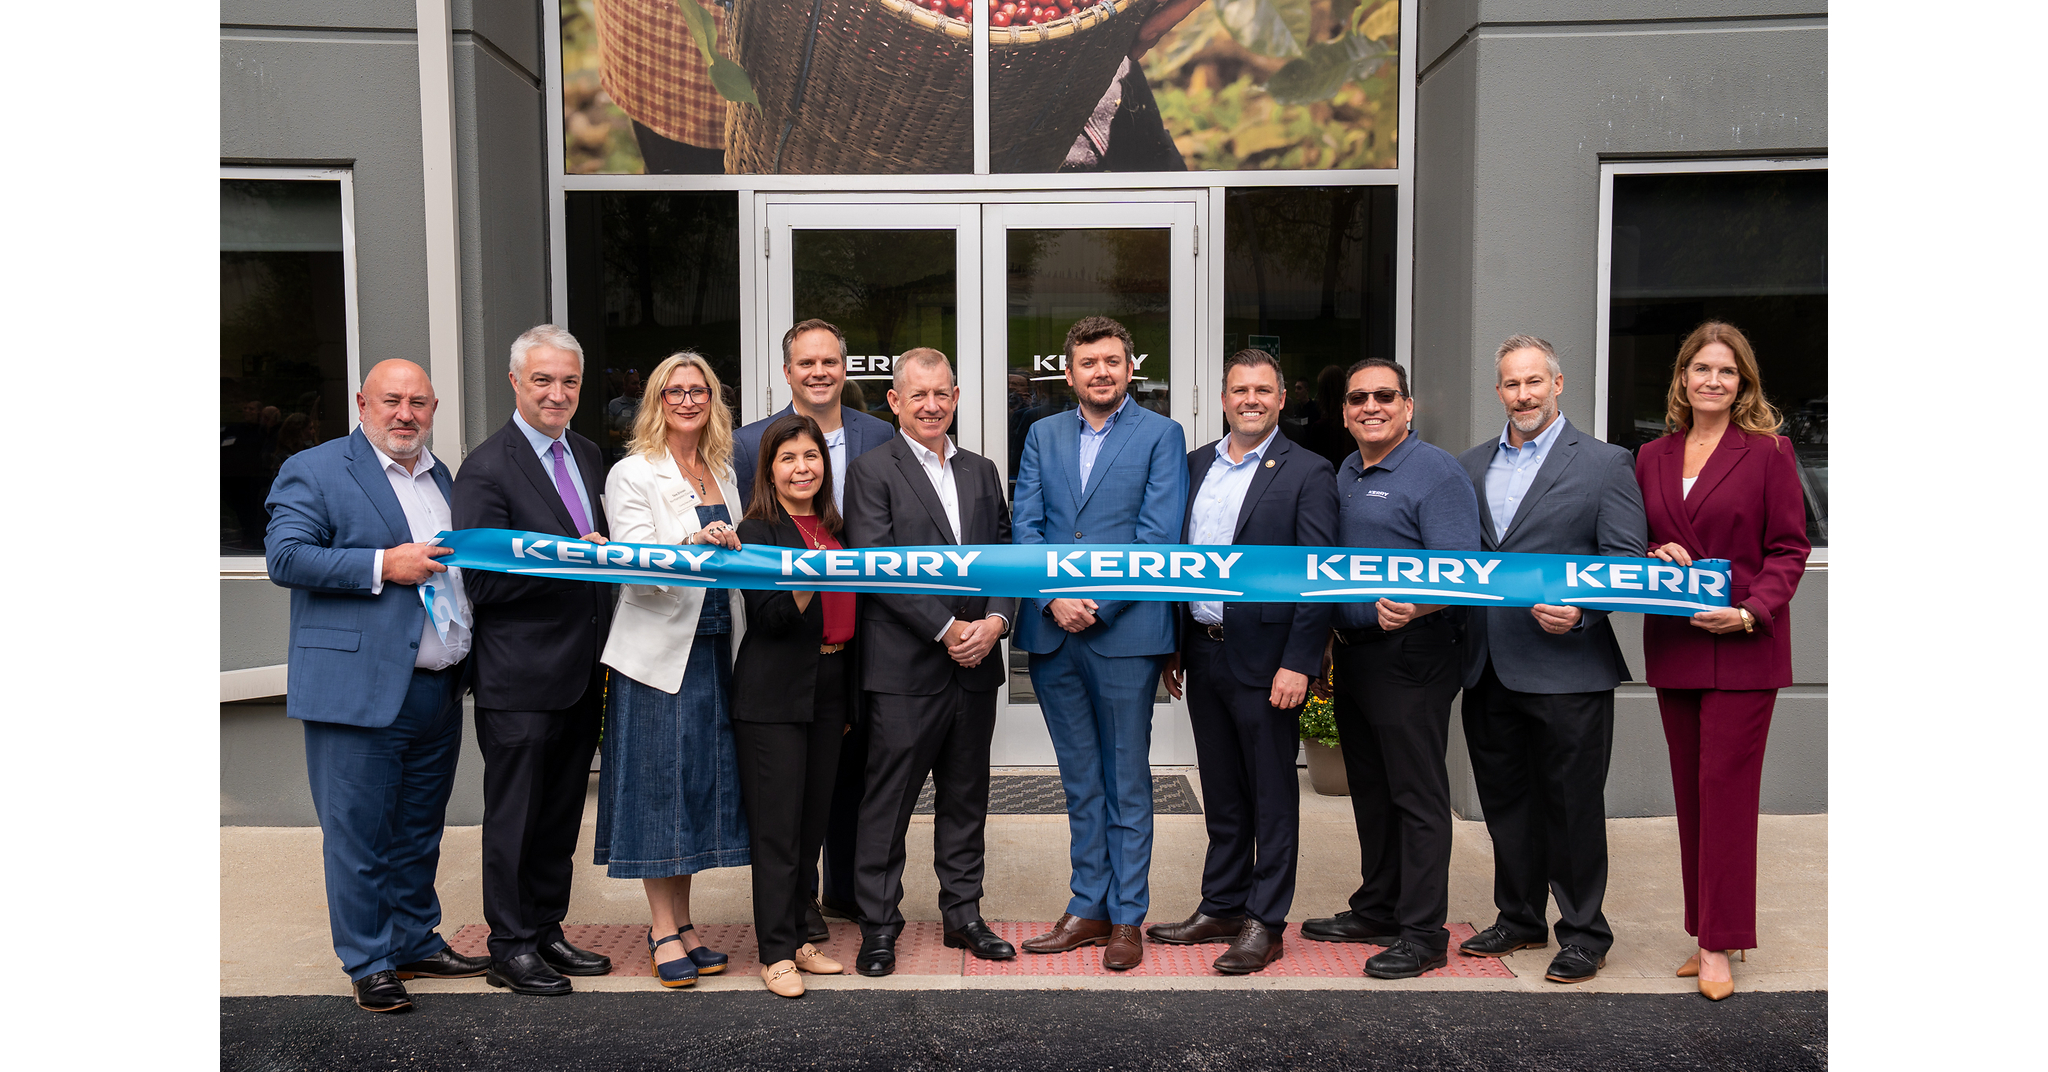
Kerry opened its first Pennsylvania manufacturing site, a Bethlehem coffee-extraction facility that significantly expands North American hot- and cold-brew production capacity. The expansion targets record premium-coffee demand, with 48% of U.S. adults consuming specialty coffee daily versus 39% for traditional coffee. The facility's 23–30 Brix concentrated products are designed to reduce shipping and refrigeration needs, with Kerry citing carbon reductions of up to 61% versus conventional alternatives.
Analysis
The facility is strategically more valuable as a customer-retention and formulation asset than as a near-term volume catalyst. By moving extraction closer to East Coast beverage and food customers, KRZ can shorten development cycles and embed itself in customers' recipes; once a flavor system is qualified in a scaled RTD SKU, switching costs are materially higher than for commoditized green coffee or generic flavors. The likely incremental prize is mix: proprietary extracts can support better gross margins and cross-selling into Kerry's taste, nutrition and preservation portfolio, rather than simply adding coffee capacity.
The main read-through is selectively negative for smaller, single-category coffee-extract suppliers and refrigerated liquid-coffee logistics, where shelf-stable concentrated formats can displace cold-chain freight and customer inventory. It is not yet a material earnings event for KRZ: neither capex, utilization, contracted volumes nor expected return was disclosed, and the stated environmental advantages are company claims rather than independently audited unit-economics. In the next 1-3 months, monitor customer-launch announcements and whether management identifies coffee as a source of North American margin expansion; absent those disclosures, the market should not assign a step-change multiple.
Contrarian risk is that premium coffee consumption remains resilient at the consumer level while branded RTD customers face promotion-heavy retail shelves and weak velocity, delaying utilization of new capacity. Higher arabica prices could also compress customer margins and shift demand toward lower-cost blends, limiting willingness to pay for differentiated extracts. Over 6-18 months, proof of high utilization and premium mix would support KRZ's ingredient-margin narrative; failure would leave the asset as underabsorbed fixed cost.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Maintain or initiate a modest long KRZ on weakness rather than chase the announcement; treat this as a 6-18 month execution catalyst, with upside contingent on disclosed North American margin expansion and coffee-related customer wins. Reassess if FY2027 guidance implies no organic-growth or mix contribution after ramp.
- Set an event-driven alert for KRZ results: upgrade conviction only if management quantifies capacity utilization, incremental revenue, or a measurable gross-margin benefit. Missing disclosures mean this is not currently a standalone catalyst trade.
- Watch a relative-value short basket of cold-chain-dependent beverage-input/logistics exposure versus KRZ only after evidence of customer conversions to ambient concentrates; the mechanism is credible but no named displaced supplier or volume data supports an immediate pair trade.
- Use arabica futures and major RTD coffee retail velocity as thesis risk indicators over the next two quarters. A sustained coffee-cost spike combined with weakening premium RTD sell-through would argue against adding to KRZ before facility ramp economics are visible.
More News
- Trump launches midterms campaign blitz amid record low approval ratings
- Nvidia Faces Questions Over China AI Chip Smuggling Cases
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company