
CLERHP's balance sheet grows by 43% to USD 163.84 million as it transforms from an engineering firm into a property developer
Source: PR Newswire
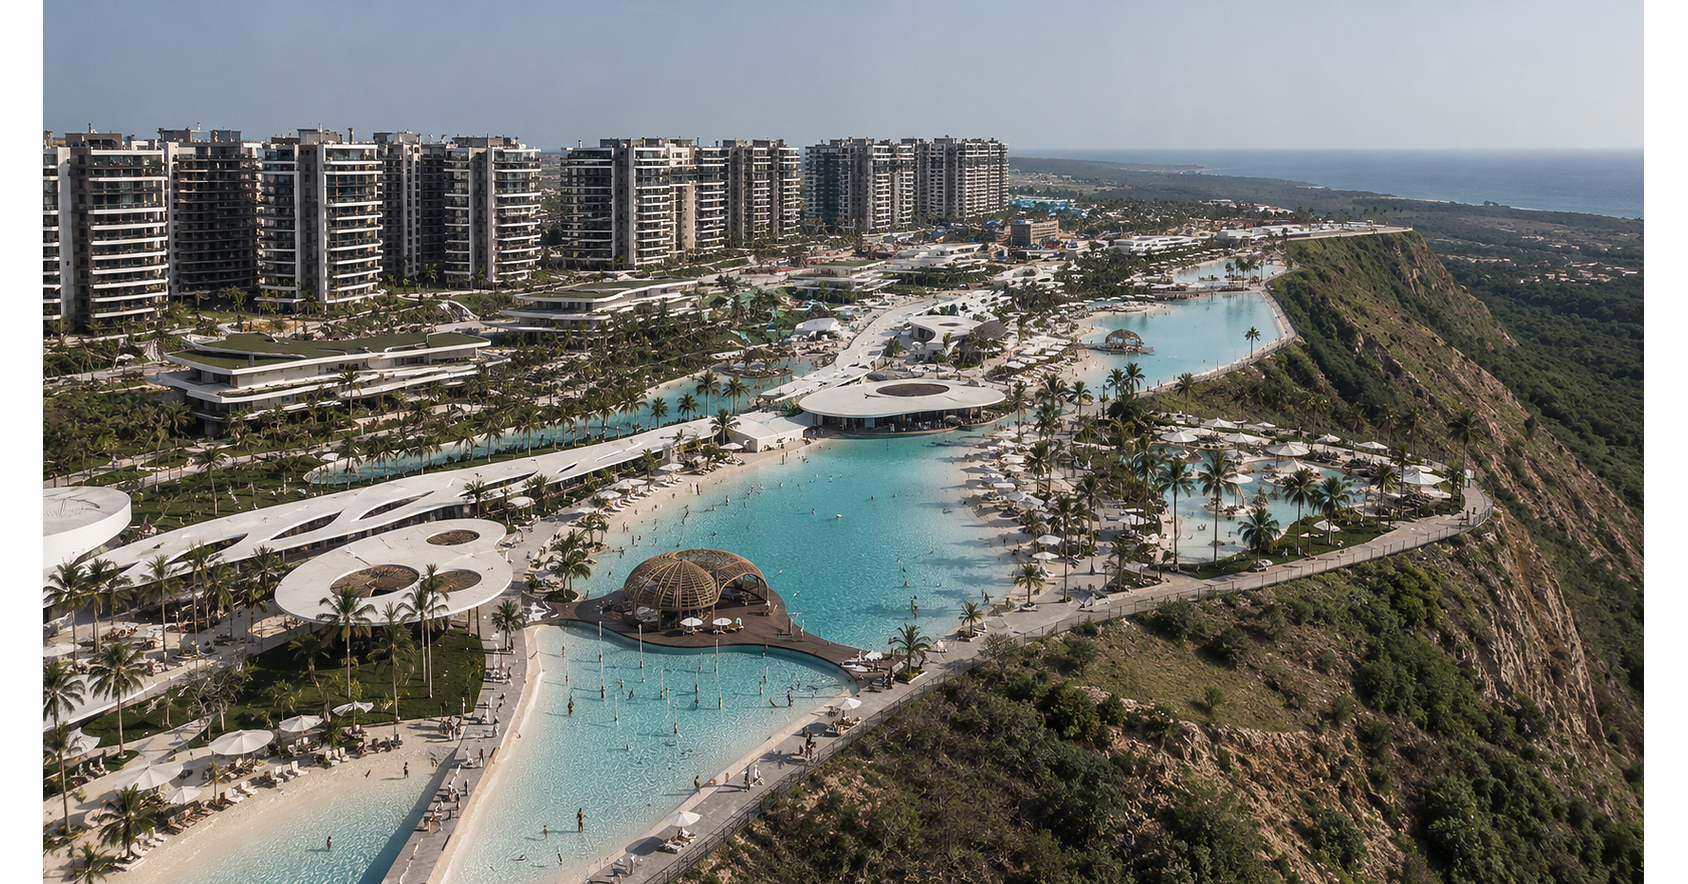
CLERHP reported first-half 2026 revenue of USD 7.20 million, up 2.25% year over year, EBITDA of USD 4.61 million, up 28.64%, and net profit of USD 2.24 million versus a loss in the first half of 2025. Larimar City & Resort had cumulative sales of USD 410.10 million as of October 2026, while its land was valued at USD 528 million; the CFO said most sales have not yet been recognized as revenue because homes have not been handed over. CLERHP's 2026–2028 plan forecasts USD 797.58 million in revenue, USD 256.37 million in EBITDA and USD 165.21 million in net profit; its financing programme of up to USD 75 million received A- ratings from Moody's Local Panamá and PCR.
Analysis
The key underwriting question is conversion, not reported sales: if revenue is recognized only at handover, Larimar’s contracted sales are not yet proof of cash collection, margin realization, or delivery capacity. That makes construction progress, customer deposits and cancellations, and handover timing the near-term signals to track. Delays could push revenue recognition out while increasing the need for working capital or additional funding.
Treat the land uplift as a collateral and financing claim—not operating cash flow. It may help support borrowing capacity, but the value is not independently validated here and does not itself service debt. Likewise, the A- ratings apply to the financing programme as described, not necessarily to the group’s overall creditworthiness. The unplaced portion of the programme makes market access and issuance terms an important execution risk; yields, covenants, maturities, and placement conditions are not provided.
The 2026–2028 plan implies a material delivery ramp, but the release does not clarify whether the headline financial targets are cumulative or annual. That scope, plus the handover schedule and project-level economics, must be verified before underwriting them. Over 1–3 months, watch for bond placement terms and evidence of construction and collections; over 6–18 months, successful handovers could validate the revenue conversion thesis. Delays, cancellations, weaker collections, or expensive/failed financing would falsify it. With no ticker, security pricing, or bond terms supplied, there is no actionable risk/reward to establish today.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- No position on the release alone. First verify whether the 2026–2028 targets are cumulative or annual, and obtain a dated handover schedule, contracted-sales cancellation terms, and customer collection data.
- Set an alert for the remaining bond placement: review actual yield, covenants, maturity, use of proceeds, and whether the financing is secured against project assets. Do not treat programme approval or a land revaluation as equivalent to funded liquidity.
- Reassess only when there is independently verifiable evidence of completed handovers and cash conversion; a rising sales headline without collections or delivery progress is not sufficient confirmation.
- Falsification watch: material construction or handover slippage, rising cancellations or weaker collections, or financing terms that make the project’s funding path less viable. No numeric price trigger is supportable without a security identifier and current market data.
More News
- Binance co-CEO Richard Teng says hackers used fake job interviews, AI tool to steal $6.3 billion in crypto 108511116
- AMD stock jumps 7% on earnings as data center revenue nearly doubles
- Marvell Technology could plunge on latest multibillion-dollar acquisition
- Disney Plans Thousands of Layoffs Companywide
- AMD rides data center riches to ‘largest and most profitable’ quarter in history
- AMD’s OpenAI, Meta chip deals trigger $1 billion quarterly charge