
Platforma stratosferyczna Sceye zakończyła rekordowy lot z USA do Japonii
Source: PR Newswire
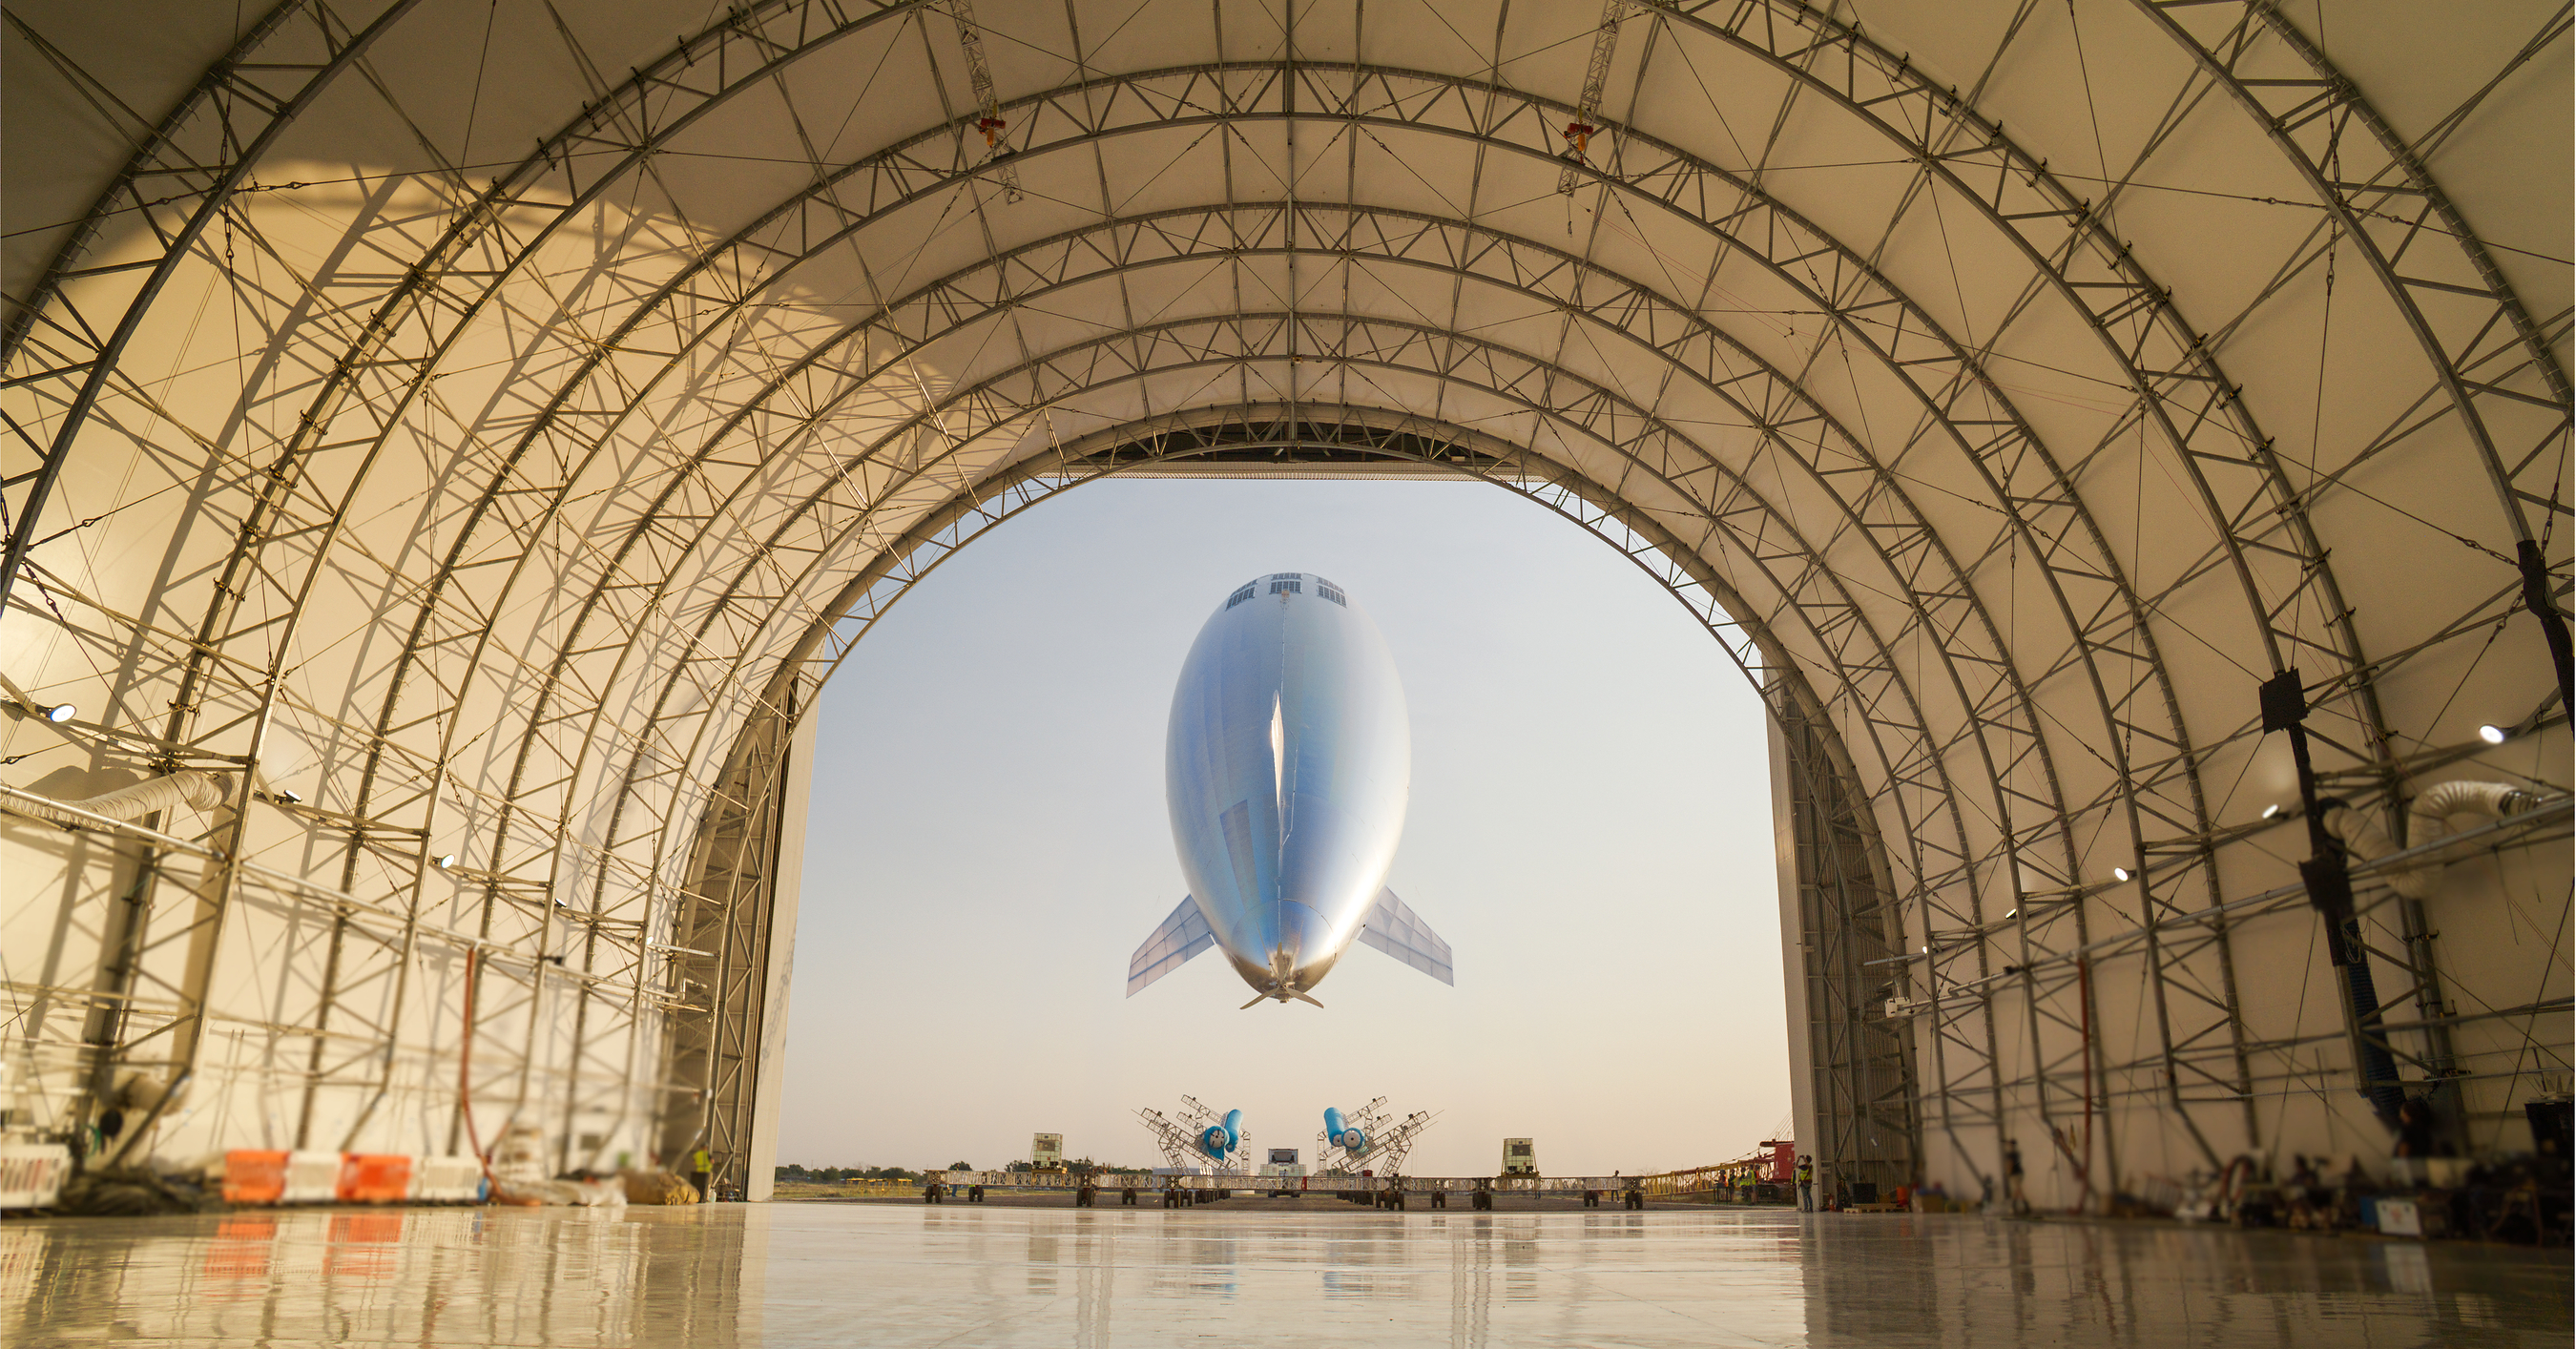
Sceye and SoftBank completed the ST1 stratospheric HAPS mission, covering nearly 30,000 km between New Mexico and Japan and operating for more than seven days in Japanese-managed airspace. The platform demonstrated mobile broadband, voice, messaging, internet, video streaming, emergency communications and drone links at 16.5-17 km altitude, while holding position within a 5-km radius. Onboard mobile-core and web-server processing delivered 68 ms average round-trip latency, more than 40% lower than internet-cloud processing, supporting commercial deployment prospects for Sceye's high-altitude connectivity infrastructure.
Analysis
The investable read-through is not a near-term disruption to terrestrial telecom economics; it is a validation step for a potential middle layer between towers and LEO satellites. SoftBank (9434 JP) gains strategic optionality in disaster resilience and rural coverage, but commercialization will depend on spectrum authorization, fleet reliability, replacement cycles and unit economics—not demonstrated latency alone. Over the next 6-18 months, HAPS could pressure the valuation premium attached to satellite direct-to-device scarcity, particularly AST SpaceMobile (ASTS), Globalstar (GSAT) and Iridium (IRDM), if operators conclude that targeted coverage can be delivered with materially lower capital intensity in favorable geographies.
The less obvious beneficiary is the telecom equipment and edge-computing stack: Ericsson (ERIC), Nokia (NOK), NEC (6701 JP), and potentially network-core vendors can monetize incremental radio/core deployments irrespective of whether HAPS, towers, or satellites win. Conversely, American Tower (AMT) and SBA Communications (SBAC) face only a long-duration risk: HAPS is most economic where tower density is low or disaster redundancy matters, not in dense urban markets where spectrum reuse and indoor coverage dominate. Consensus is likely over-extrapolating from technical validation; a commercial fleet requires aviation approvals across jurisdictions, proven multi-month station-keeping, payload availability, insurance, and a credible cost per covered GB versus LEO and rural towers.
Near-term price impact should be limited because the platform owner is private and no contracted revenue, deployment timetable, spectrum arrangement, or cost data are disclosed. The catalyst path is a disclosed paid-service agreement, regulator-approved recurring operations, or an operator capex commitment within 1-3 months; absent these, this remains technology-optionality rather than a revenue event. Falsification of the satellite-displacement thesis would be binding spectrum/airspace constraints, materially higher fleet replacement costs, or LEO operators securing exclusive carrier distribution and demonstrating superior cost per delivered GB.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Key Decisions for Investors
- No directional trade on SoftBank (9434 JP) solely on this development; place an alert for a paid HAPS service contract, committed fleet capex, or spectrum approval. Reassess if disclosed economics indicate rural coverage cost below terrestrial buildout and the addressable revenue can move consolidated EBITDA by at least 1%.
- Maintain a 6-12 month relative-value watch: short ASTS or GSAT versus long ERIC or NOK only if HAPS commercialization milestones are corroborated by carrier procurement. Target a 15-20% convergence in satellite optionality premiums; stop out on exclusive carrier launches, funding announcements, or backlog growth that validates LEO direct-to-device economics.
- For telecom infrastructure exposure, favor AMT over SBAC as a defensive expression: AMT's greater geographic diversification and enterprise fiber exposure reduce sensitivity to any eventual rural-access substitution. This is a structural, not next-quarter, consideration; reassess if HAPS deployments become recurring rather than trial-based.
- Monitor SoftBank, NTT (9432 JP), KDDI (9433 JP), and Rakuten Group (4755 JP) capex commentary over the next two earnings cycles. A carrier shifting disaster-recovery or remote-area spending from towers/satellites to HAPS would be the first independently verifiable signal with broader sector relevance.
More News
- Saudi Arabia intercepts missiles and drones as fighting with Houthis rages
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- 5 big analyst AI moves: ’Uniquely catalyst-rich’ months ahead for SpaceX
- Saudi Arabia intercepts drones and missiles as fighting with Yemen’s Houthis continues
- Qatar official calls for peace and security to boost trade, investment