
Will Monster Beverage's Innovation & Global Expansion Aid Growth?
Source: zacks.com
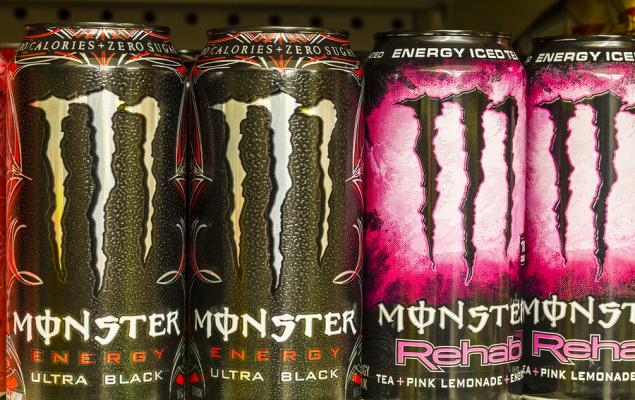
Monster Beverage reported U.S. Ultra sales growth of 19% year over year and Juice Monster growth of 26% in second-quarter 2026, with management crediting innovation for contributing to sales growth. Shares gained 12.5% over six months versus 2.4% for the industry, while the stock trades at 34.94x forward earnings against an 18.6x industry average. Consensus EPS growth estimates are 7.8% for 2026 and 14.3% for 2027; estimates were stable over the past 30 days and Zacks rates MNST Hold.
Analysis
MNST’s growth narrative is strategically credible but not yet a clear earnings-revision catalyst: the reported brand growth sits alongside stable 2026–27 EPS estimates. At 34.9x forward earnings versus 18.6x for the industry, the stock requires continued premium growth and execution; another leg of multiple expansion likely needs evidence that innovation adds category demand rather than shifting consumers among Monster’s own brands. The key second-order risk is portfolio complexity: new launches and heavier marketing can defend shelf space against Celsius and Red Bull, but may also raise promotional and launch costs or cannibalize established products before incremental sales are visible.
Over the next 1–3 months, watch organic volume, realized pricing, U.S. share, and gross-margin commentary—not launch counts or management enthusiasm alone. International distribution offers a longer-dated growth lever, but execution and local brand-building can precede meaningful profit contribution. Packaging and input-cost movements are a margin sensitivity to monitor, not a demonstrated current headwind in this report.
Contrarian read: the article’s positive framing may be largely priced in after the recent relative outperformance, while stable estimates leave limited near-term confirmation. Conversely, the premium is not automatically excessive if growth translates into durable share gains and upward revisions. A sharp slowdown in Ultra/Juice momentum, weaker margins, or continued estimate stagnation would challenge the valuation; upward revisions supported by volume and international contribution would falsify the cautious view.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Avoid chasing MNST on this article alone; consider a modest underweight versus consumer-staples exposure while estimates remain unchanged and valuation remains premium. Reassess after the next earnings update.
- For a long entry, require confirmation from organic volume/share gains and improving 2027 EPS revisions; do not treat product launches or marketing expansion by themselves as proof of incremental demand.
- Track quarterly gross margin, promotional intensity, and evidence of cannibalization across Monster brands. A material margin deterioration alongside slowing U.S. growth would strengthen the underweight thesis; sustained growth with stable margins would invalidate it.
- Monitor Celsius and Red Bull competitive activity and international distribution progress over the next 6–18 months; the article provides no market-share, launch-level profitability, or regional contribution data, so verify these before sizing a directional trade.
More News
- Goldman Sachs lowers Pepsico stock price target on growth outlook
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Rising fuel costs slashed Delta’s profit outlook despite strong demand
- ‘I drive a Tesla’: After Elon Musk said he’d lose his job, Delta CEO Ed Bastian says there’s ‘no tit for tat’ as airline unveils earnings miss
- Why is the Chinese stock market missing the AI rally
- OpenAI's revenue scare, Delta earnings, what investors think of a Starbucks-Chipotle deal and more in Morning Squawk