
METLEN y PETRONAS firman un acuerdo de suministro de GNL en el sureste de Europa
Source: PR Newswire
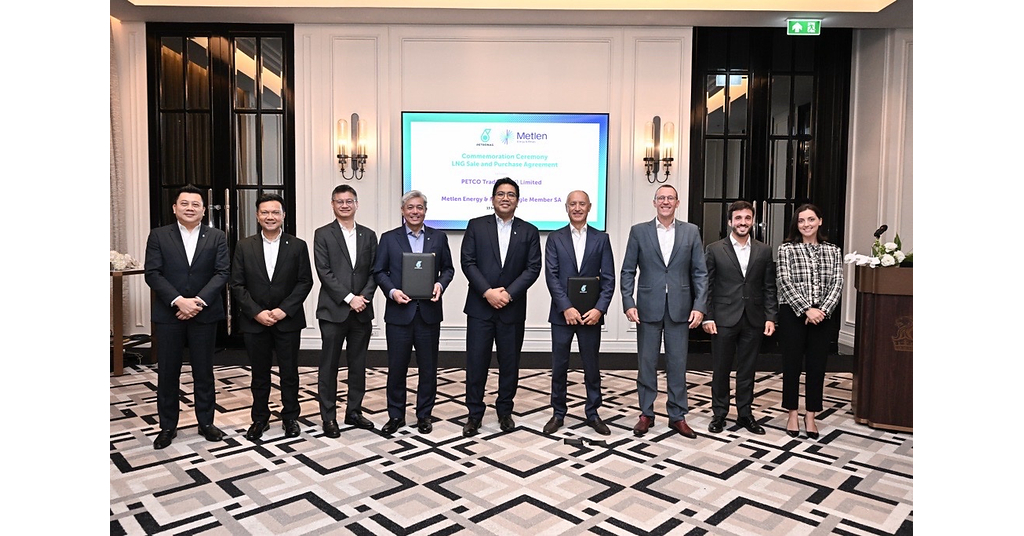
METLEN and PETRONAS signed a five-year LNG supply agreement beginning in 2027, under which PETRONAS will deliver six Atlantic-basin cargoes annually to Greece, equivalent to approximately 600 million cubic meters per year. The deal diversifies METLEN's gas sourcing, improves supply flexibility and resilience for Greece and southeastern Europe, and expands PETRONAS's LNG presence in Europe and the Mediterranean. The agreement is strategically supportive of regional energy security, though its contracted volume is modest relative to the broader European gas market.
Analysis
The commercial volume is too small to change METLEN's consolidated earnings directly, but its strategic value is higher than its nominal throughput: a contracted Atlantic-basin source improves optionality against a regional gas dislocation and can support trading margins when southeast-European hub prices detach from TTF. The benefit accrues only if METLEN retains destination and scheduling flexibility; a fixed-price or oil-indexed structure could instead create mark-to-market exposure if European gas prices normalize. Given elevated leverage relative to many European utility peers, investors should treat this as a resilience and credit-positive signal rather than a near-term EBITDA upgrade.
For 1-3 months, MTLN could receive a modest scarcity premium as investors increasingly value integrated gas procurement alongside its generation and power-marketing operations, particularly ahead of winter contracting. The more investable second-order read is on Greek gas infrastructure and regional power spreads: additional reliable seaborne supply reduces the probability of extreme marginal-gas pricing, which is marginally negative for unhedged thermal generators but supportive for industrial power consumers and METLEN's downstream customer franchise. PETRONAS is unlisted, leaving no clean listed supplier expression.
Consensus may overstate the security-of-supply narrative: six cargoes annually do not insulate Greece from a broader LNG shipping disruption, Atlantic-basin competition, or a cold-winter storage draw. The thesis is falsified if management cannot demonstrate incremental gas-marketing gross profit, lower procurement volatility, or stable net-debt/EBITDA despite continued capital deployment; a deterioration above roughly 3.5x would likely dominate any valuation benefit from supply diversification over the next 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Maintain/watch-list long MTLN rather than chase the announcement: add only on a 5-8% pullback or after results show measurable energy-trading margin resilience and no upward revision to leverage. Target is a modest multiple re-rating from lower earnings volatility; risk is that the SPA is economically immaterial or inflexible.
- Set a winter 2026-27 alert on TTF versus southeast-European gas and power benchmarks: a sustained regional premium above TTF, combined with evidence that METLEN can redirect or optimize cargoes, would justify upgrading to a 6-12 month long MTLN position.
- Avoid using MSCI or LSEG as read-through trades; their mention is ESG/indexing-related and has no identifiable revenue or earnings linkage to the supply contract.
- Risk-control trigger for any MTLN long: reduce if FY2027 guidance implies net debt/EBITDA above 3.5x, gas procurement losses emerge, or a European LNG oversupply materially compresses gas-trading optionality. These outcomes would outweigh the contract's strategic benefit.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- RBC Capital cuts Sprouts Farmers Market stock rating on margin concerns