
K-Beauty Leader Dr.Althea Hits 35 Million Global Sales for 345 Relief Cream, Unveils Expanded 345 Relief Line
Source: PR Newswire
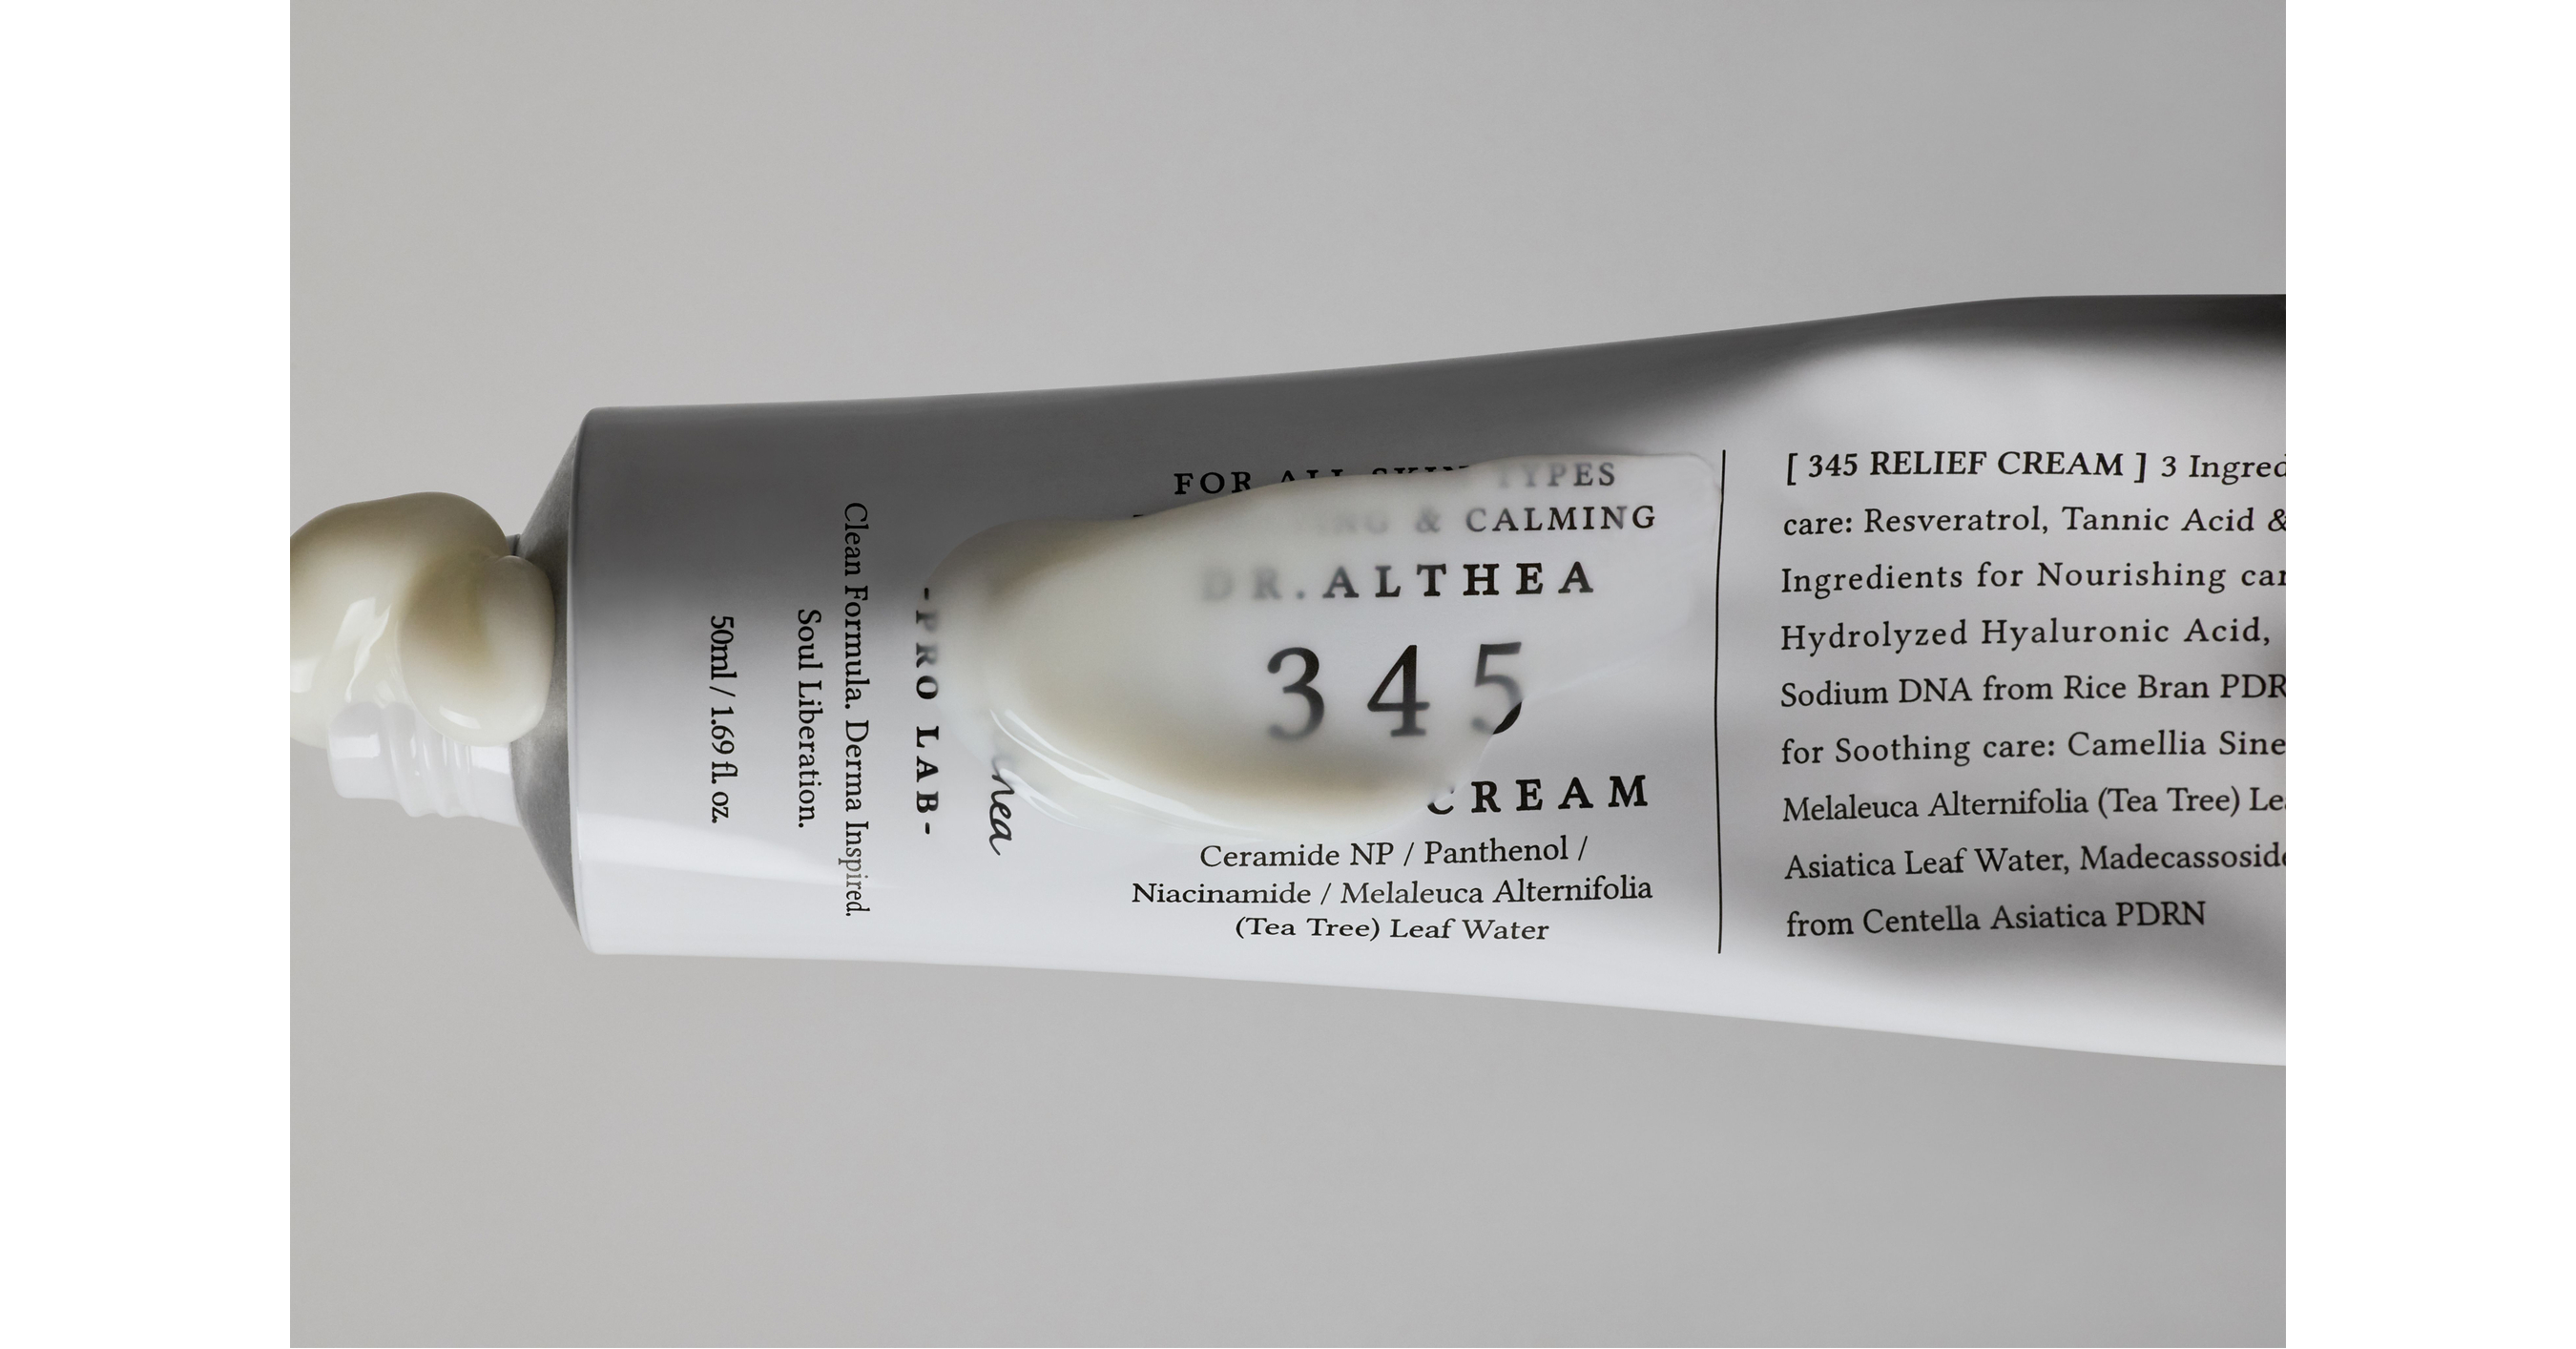
Dr.Althea said its 345 Relief Cream has surpassed 35 million cumulative units sold globally, signaling strong consumer demand for its sensitive-skin skincare products. The company is expanding the 345 Relief line with products including a cleansing oil, serum, mist, mask, and spot treatment, while broadening U.S. availability through Amazon, Ulta Beauty, and Olive Young. The announcement is a positive brand and retail-distribution milestone, though it does not disclose revenue, profitability, or forward sales guidance.
Analysis
This is directionally positive for AMZN and ULTA as evidence that Korean beauty continues to create repeatable, cross-border hero-product demand, but the disclosed sales figure is not independently tied to either retailer’s sell-through, take rate, or inventory commitment. For AMZN, the more relevant read-through is third-party Beauty Services and fulfillment volume rather than material first-party revenue; the incremental impact is immaterial against its scale. ULTA has greater category sensitivity, but an emerging-brand launch is unlikely to alter FY earnings absent evidence of meaningful door count, replenishment velocity, or exclusivity.
The investable second-order effect is intensifying competition for sensitive-skin shelf space. Dermatology-positioned incumbents including EL (Clinique), LVMUY (Sephora ecosystem proxy), and OTC-adjacent names such as Kenvue (KVUE) face modest share pressure if affordable K-beauty converts routine-based consumers from single-product purchases into multi-step regimens. That dynamic is more likely to compress promotional economics and customer-acquisition efficiency for specialty beauty than to produce immediate revenue displacement.
Over the next 1-3 months, monitor Amazon bestseller rank, review velocity, price discounting, and Ulta web availability as real-time verification of demand versus PR-driven claims. A sustained top-tier ranking with low discounting would support a broader K-beauty basket thesis into holiday; heavy couponing or rapid marketplace seller proliferation would indicate weak pricing power and gray-market risk. Over 6-18 months, the key question is whether retailers can retain gross-margin dollars as international brands gain direct-to-consumer scale and bargaining leverage.
Contrarian view: the market may overinterpret unit sales as proof of incremental US retail demand. Cumulative global units do not establish current velocity, geographic mix, repeat rates, or wholesale economics; brand awareness can increase marketplace traffic without producing enough category profit to move AMZN or ULTA estimates.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- No standalone AMZN or ULTA trade on this release; expected earnings sensitivity is below materiality. Treat it as a category-demand data point rather than a company-specific catalyst.
- For an existing ULTA position, track 4-8 weeks of Dr.Althea SKU availability, ranking, and promotional intensity ahead of holiday resets. Add only if verified replenishment and broader assortment coincide with management commentary on prestige/skincare traffic; reduce if discounting becomes the primary conversion lever.
- Maintain AMZN as the cleaner indirect beneficiary only within a broader Beauty/third-party-services thesis, not as a K-beauty expression. The thesis is falsified if marketplace pricing disperses sharply or seller counts rise faster than review growth, signaling commoditization rather than durable demand.
- Watch EL and KVUE for a more actionable relative-value setup if retailer data show K-beauty gaining sensitive-skin share while their skincare organic sales or gross-margin guidance weakens. Until then, no short is warranted because the category impact is unquantified.
More News
- Exclusive-Anthropic’s IPO pitch embraces AI’s promise and peril
- AI market needs to make $6 trillion a year by 2031 to fund its infrastructure habit
- Why Synopsys Stock Soared Nearly 5% Higher Today
- Wall Street is closing out a strong quarter. Plus, Lilly's mixed obesity drug trial data
- Synopsys, Amazon Web Services sign chip design licensing deal worth more than $1 billion
- OpenAI apes AWS Marketplace while Anthropic remains stubbornly Microsoftian
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Selecting an AI Research Platform for Institutional Investors
- Weekly Update: New Reporting Features and More Sources for Document Search