
'Sands China's Community Revitalization Programme for Rua das Estalagens 2026' Unveils 24 Selected Enterprises
Source: PR Newswire
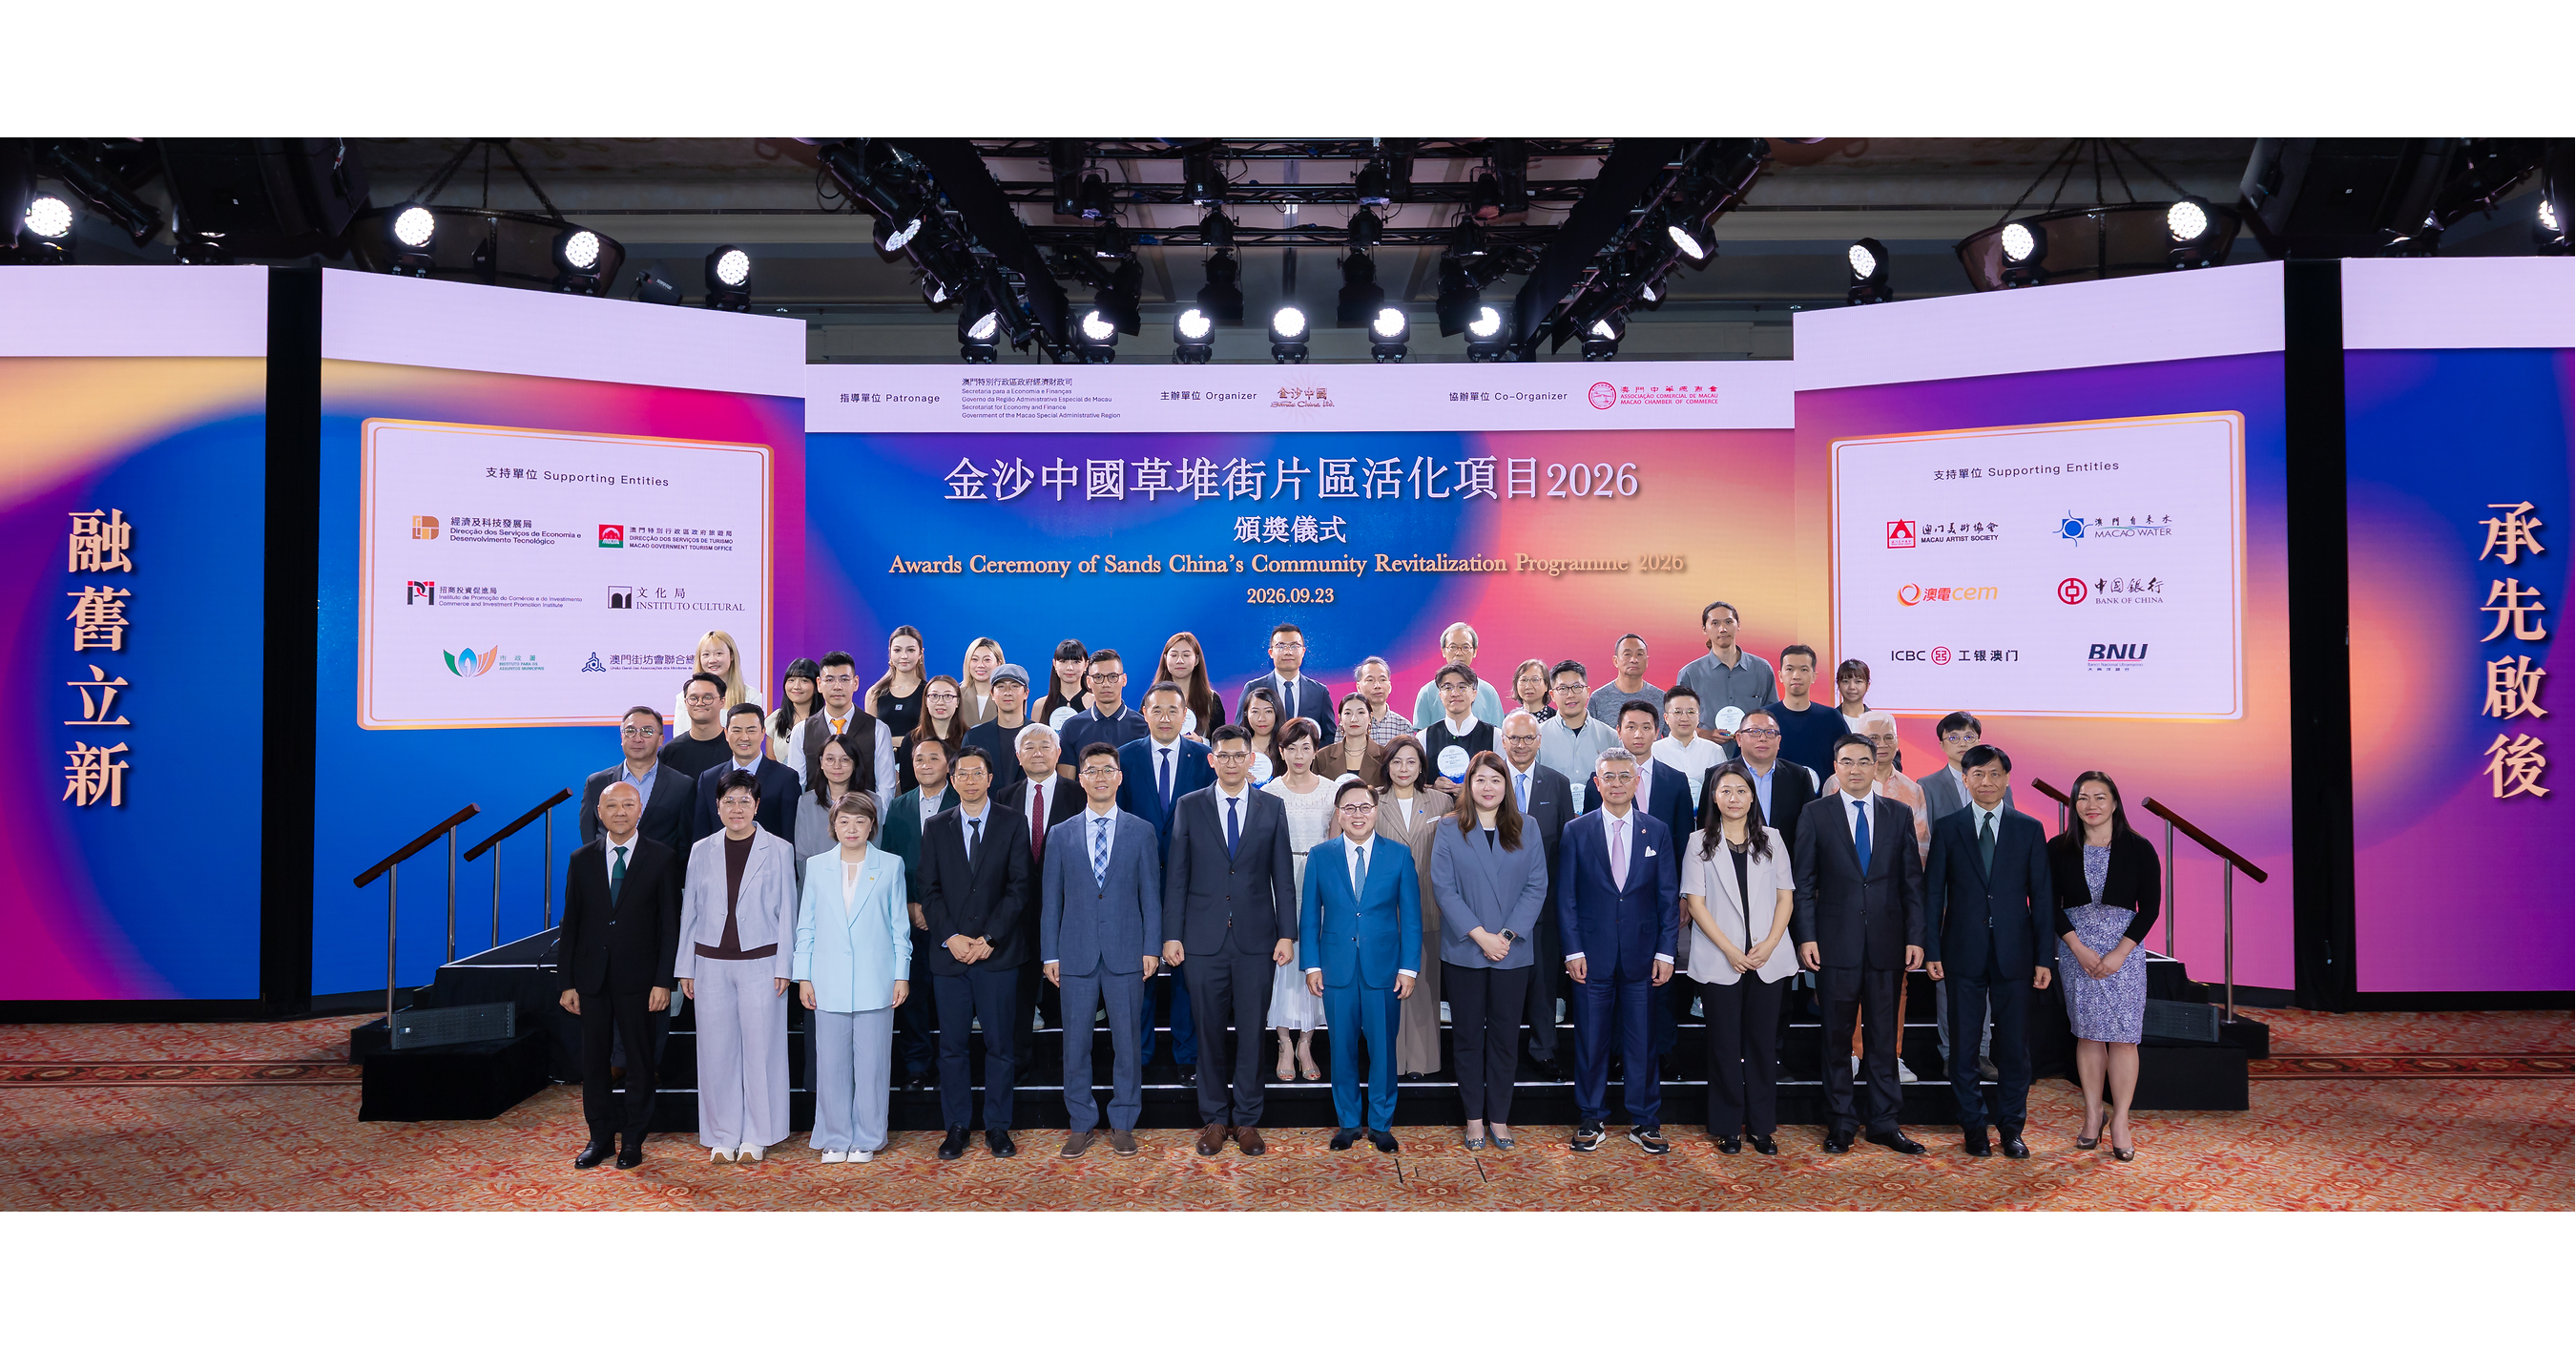
Sands China selected 24 enterprises—11 new-business proposals and 13 shop-rebranding plans—for its 2026 Rua das Estalagens community revitalization programme, bringing total businesses supported since 2024 to 30. New ventures must invest at least MOP300,000 and can receive subsidies of up to MOP1 million, while existing merchants can receive up to MOP500,000; 60% of funding will be paid upfront. The initiative supports Macao SME development, retail and tourism-district renewal, but is unlikely to materially affect Sands China's near-term financial results.
Analysis
This is principally a regulatory-capital allocation signal rather than an earnings event. LVS’s Macao concession value depends on sustained alignment with Beijing/Macao priorities around non-gaming diversification; visible local-SME investment can modestly reduce renewal, operating-permit, and future capex-friction risk. The direct P&L effect is immaterial relative to LVS EBITDA, but successful district programming can improve the company’s standing when government seeks partners for tourism, cultural, and MICE initiatives.
The second-order benefit is strategic differentiation versus Galaxy Entertainment (0027 HK), MGM China (2282 HK), and Wynn Macau (1128 HK): Sands has the largest mass-market-oriented Cotai footprint and can convert community/cultural programming into incremental itinerary length and non-gaming spend. That said, activity on the peninsula is unlikely to materially change Cotai visitation or gaming hold in the next 1-3 months; investors should not extrapolate a small CSR outlay into a consumer-demand inflection.
Contrarian view: the market may underprice the value of concession-risk mitigation but overprice the near-term commercial payoff from diversification headlines. The relevant 6-18 month catalyst is evidence that Macao policy support translates into higher-margin non-gaming traffic, preferential participation in government-led events, or reduced compliance/capex burden—not social-media traction at subsidized merchants. Falsify the strategic benefit if LVS’s Macao mass GGR share, retail rent trajectory, or non-gaming revenue growth continues to lag peers despite elevated government engagement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- No standalone LVS trade on this announcement; treat it as a qualitative positive for concession-regulatory positioning, not a forecast-changing catalyst.
- For existing LVS exposure, retain a 6-18 month overweight only if quarterly Macao mass-market revenue and mall/rental metrics sustain outperformance versus 0027 HK and 1128 HK; reassess on a material downward revision to Macao EBITDA guidance or loss of mass-share momentum.
- Watch for government announcements on MICE, cultural-tourism, or district-redevelopment partnerships involving Sands. A measurable, recurring traffic or event-allocation benefit would support adding LVS versus MGM China (2282 HK), whose smaller Macao asset base offers less operating leverage to broad destination programming.
- Avoid using short-dated LVS calls: the immediate revenue contribution is too small to overcome Macau GGR, China consumption, FX, and US multiple-risk drivers. Use any post-headline strength to evaluate entry only after monthly Macao GGR and LVS property-level operating data confirm demand.
More News
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- Here's what happens to the economy when Treasury yields soar like they are now
- Oil industry warns a diesel export ban will raise fuel prices as Trump weighs restrictions
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet
- Meta's standoff with Amazon over Muse could be a sign of things to come
- How a Diesel Export Ban Could Impact US Fuel Prices