
iPhone Duo Expected to Capture Nearly 25% of Foldable Smartphone Market in 2026 as Apple's First Foldable Drives Supply Chain Upgrades, Says TrendForce
Source: PR Newswire
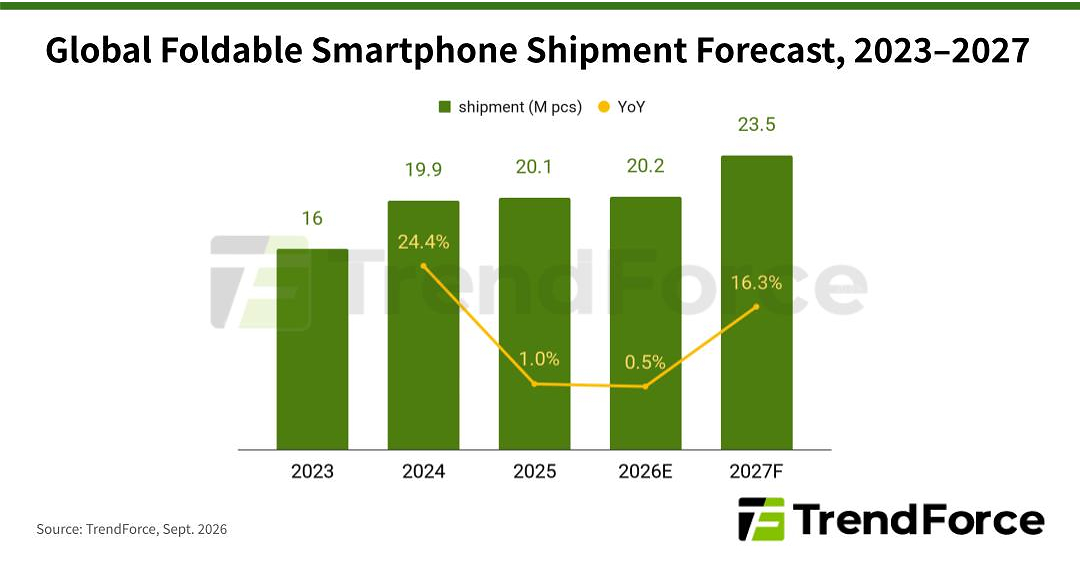
TrendForce forecasts Apple’s first foldable, the iPhone Duo, will ship about 5 million units in 2026 and capture 24.8% of the global foldable market, making Apple the No. 2 brand behind Samsung’s projected 35.1% share. Global foldable shipments are projected at 20.2 million units, up only 0.5% YoY, with Apple largely offsetting a more than 20% decline in combined Android-brand shipments excluding Apple amid higher component costs. Apple’s 10-layer display design, titanium construction and iOS 27 multitasking/AI features are expected to accelerate upgrades and scale across display, ultra-thin glass, hinge and device-architecture supply chains.
Analysis
The investable implication is not unit volume but Apple’s ability to impose qualification standards on a fragmented foldable component stack. At an initial ~5 million-unit run rate, iPhone Duo is unlikely to move AAPL consolidated revenue or EPS materially in FY26; it can, however, create a premium-margin upgrade cycle if the device expands iPhone mix and attachment rates. The more durable value accrues to qualified display, UTG, adhesive and precision-hinge suppliers, where Apple validation can reduce customer concentration risk and force Android OEMs to adopt higher-spec components.
The near-term read-through for AAPL is therefore more mixed than the launch narrative suggests. A premium foldable could cannibalize high-end Pro/Pro Max demand rather than create an incremental replacement cycle, while omitted imaging and biometric features leave a clear opening for Samsung and Huawei at the ultra-premium end. The key 1-3 month catalyst is channel evidence on sell-through versus production plans; preorder headlines are less useful than evidence of low return rates, carrier subsidy support and whether Apple raises component orders after the first build cycle.
Consensus may overstate the category-expansion effect. A flat overall foldable market implies Apple is initially reallocating demand, not unlocking a new handset TAM; that makes Samsung’s foldable economics more vulnerable than AAPL’s. Over 6-18 months, however, higher industry volumes of Apple-qualified materials could lower component costs and ultimately broaden foldable adoption—an outcome that benefits scaled Asian display and materials ecosystems more than the handset OEMs competing away the savings.
Treat the supplier angle as a watchlist rather than a trade until the bill of materials and sourcing allocations are independently confirmed. The thesis is falsified if early production is not expanded after launch, if iPhone ASP fails to rise despite foldable mix, or if Samsung holds foldable volumes through price cuts without a material margin reset.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Maintain AAPL as a core long, but do not add solely on foldable launch enthusiasm; add on evidence of a raised December-quarter build plan or iPhone ASP/mix uplift. Upside is multiple support from a new premium tier; downside is limited incremental EPS if cannibalization dominates.
- Initiate a 1-3 month relative-value watch: long AAPL versus short Samsung Electronics (005930 KS) only if channel data show Apple gaining premium foldable share while Samsung cuts pricing or guides mobile-margin pressure. Exit if Samsung unit guidance is maintained without margin deterioration.
- Monitor Apple supply-chain disclosures for Corning (GLW), Universal Display (OLED), TDK (6762 JP) and Murata (6981 JP). Do not position before confirmed content or allocation data; qualification wins could matter more than initial volumes, but unverified supplier attribution is a material risk.
- For downside protection around the first post-launch earnings report, consider AAPL put spreads funded by upside call sales only if implied volatility remains below the prior major-iPhone launch range; the risk event is weak foldable incremental demand disguised by stable total iPhone units.
More News
- AI funding fears rattle Wall Street. Here's how we're adjusting our portfolio
- Spotify Earnings: A Miss, But Long-Term Potential Remains
- The AI graveyard: a running list of projects and startups that didn’t make it
- Block’s new voice model sounds eerily human
- Peter Thiel says Apple has done 'nothing new' after Steve Jobs
- SpaceX's $1 Trillion Revenue Ambition: Can Elon Musk Deliver?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals
- What Makes Financial Data Ready for AI Research?