
The big reason Boeing’s stock is falling so hard after earnings
Source: MarketWatch
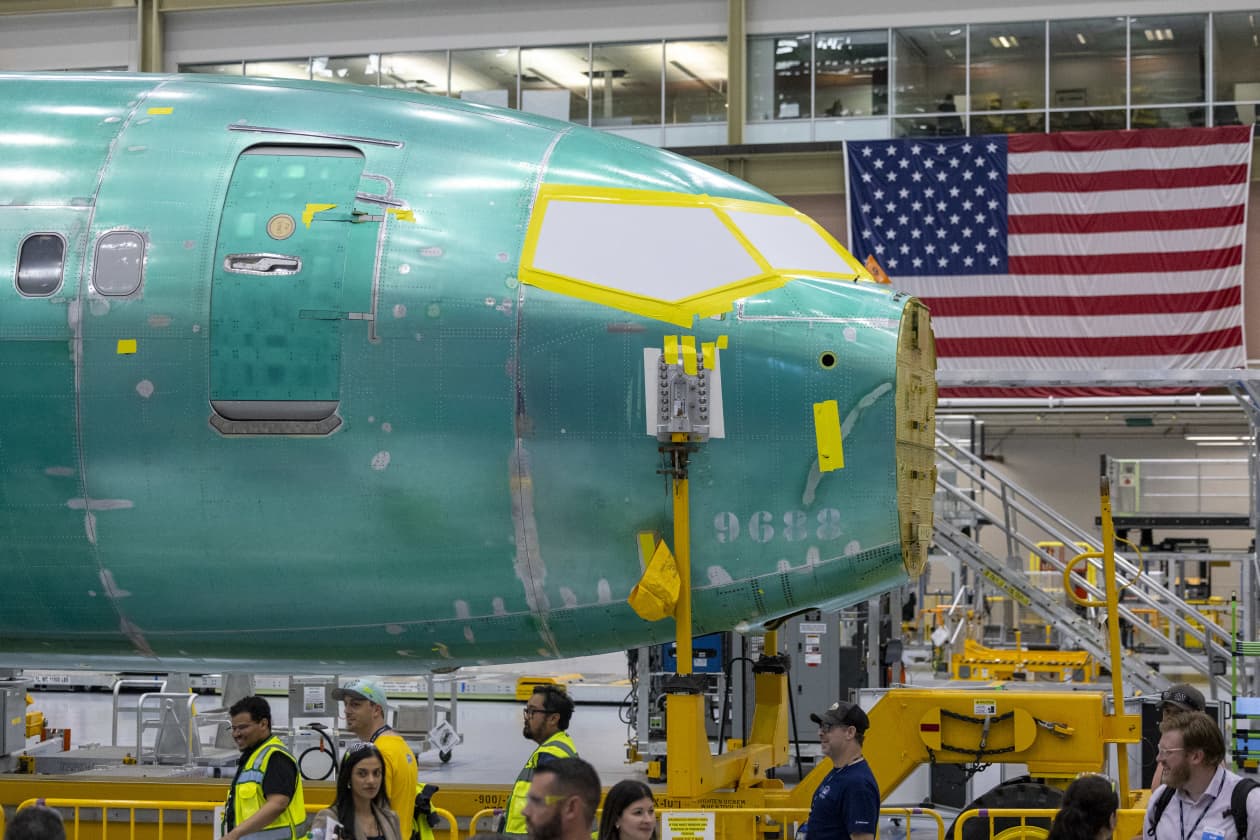
Boeing said it expects to miss its target of delivering 500 737 Max aircraft this year, as executives need more time to stabilize production and deliveries at 47 planes per month. The company provided no revised delivery outlook, renewing concerns about its turnaround; its shares fell sharply Tuesday.
Analysis
The key equity risk is not the missed unit count in isolation; it is that slower throughput can delay cash conversion while keeping quality-control and rework costs elevated. With no replacement outlook, investors cannot anchor the timing of a recovery, so execution risk may weigh on BA’s multiple even before the full-year delivery shortfall flows through reported results. Near term, watch for further guidance changes and evidence that production stability is improving—not just management reaffirming a rate. Over the next 1–3 months, the most useful checks are completed deliveries, inventory and working-capital movement, and any supplier or customer commentary that corroborates the ramp. Over 6–18 months, persistent constraints could extend airline fleet gaps and support Airbus’ negotiating position on available narrowbody capacity; however, long order backlogs and limited near-term substitution capacity make an immediate transfer of Boeing demand to Airbus unlikely. A contrarian risk is that the delivery miss is already reflected in BA’s reaction while the market underweights the value of eventual production normalization. That case needs measurable improvement in deliveries and cash generation, not assurances alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately negative
Sentiment Score
-0.55
Ticker Sentiment
Key Decisions for Investors
- Avoid adding to BA solely on weakness until the company provides a credible revised delivery path. Treat the absence of a new outlook as a reason to demand a wider execution-risk discount.
- For a near-term relative-value expression, consider a modest BA underweight versus a diversified aerospace-and-defense basket rather than an outright short; reassess after the next delivery update. The hedge will not isolate commercial-aircraft execution risk perfectly.
- Monitor monthly delivery data alongside inventory/working-capital trends and supplier commentary. A worsening combination would strengthen the downside thesis; improving deliveries with cash conversion would weaken it.
- Falsification: reduce or close the underweight if BA demonstrates sustained delivery improvement and better cash conversion without another adverse guidance revision. Conversely, renewed production disruption or continued lack of a credible outlook would extend the risk window.
More News
- Boeing shares slide on a disappointing cash flow update. Why this dip is buyable
- Tech's relief rally extends as attention turns to tough decisions for the Fed
- JetBlue Promises It Will Return to Profitability
- Boeing jetliner production challenges weigh on third-quarter results
- Meta AI Boom Fuels Goldman Windfall
- Cramer says something is missing in Tuesday's market rally and he's not eager to jump in