
THREE LEGENDS. THREE MORE YEARS. GUINNESS IS RUNNING IT BACK WITH NOTRE DAME AND JOE MONTANA
Source: PR Newswire
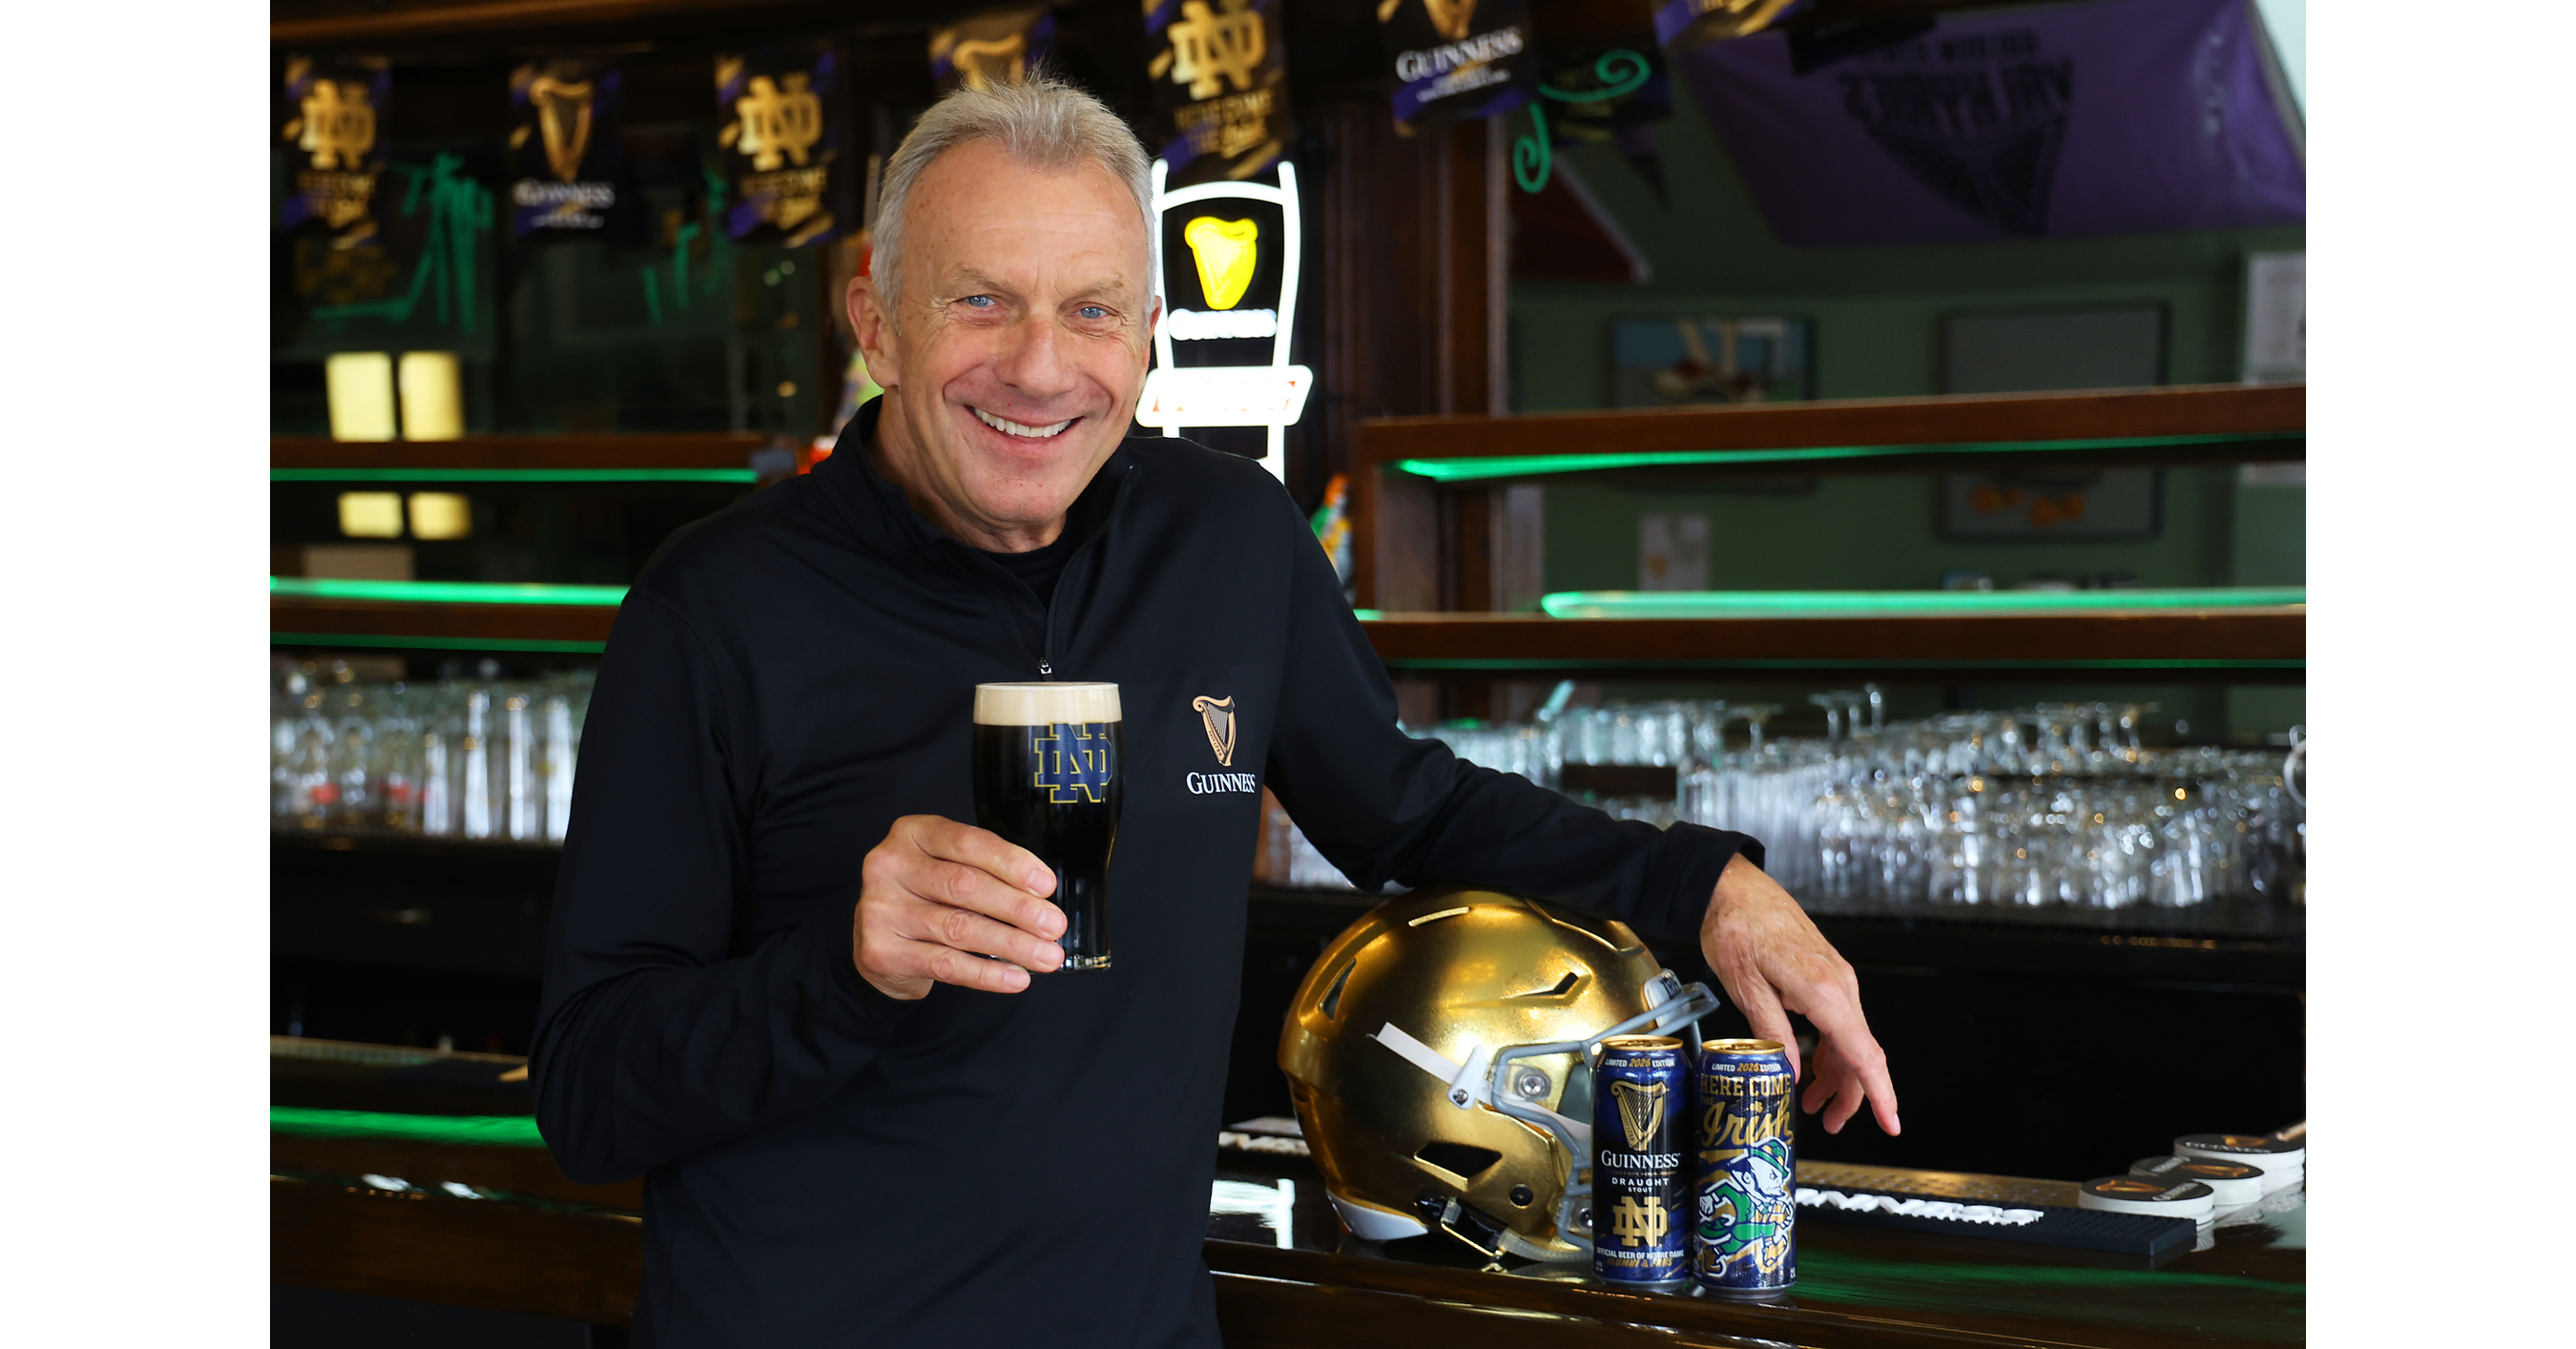
Guinness is extending its “Official Beer” partnership with Notre Dame Athletics for another three seasons and re-signing Hall of Fame quarterback Joe Montana as a brand ambassador. The article also notes a new limited-edition Notre Dame Guinness Draught can featuring the Football Leprechaun mark, available now in select markets and in more markets over the season. Overall, this is a positive brand/consumer engagement update for Guinness and Diageo, but it is unlikely to materially move financial markets.
Analysis
This reads more like a low-cost brand maintenance move than a material earnings event. The important signal is not the sponsorship itself, but that Diageo is willing to keep paying to protect an occasion-driven beer franchise in a high-visibility sports window, which usually implies management still sees attractive payback versus broad-based discounting. The second-order beneficiary is the on-premise ecosystem around game-day drinking — draft lines, sports bars, and distributor inventories — but the impact on consolidated DEO is likely de minimis unless it translates into sustained premium stout share gains.
The competitive angle is that this can quietly pressure seasonal craft and import substitutes more than mainstream lagers; Guinness occupies a premium, tradition-heavy niche that is harder to replicate with price promotions alone. If anything, the biggest loser is not a named peer but the fragmented craft segment that competes for the same fall football rituals. The market may underweight the signaling value: Diageo is protecting a U.S. brand asset with relatively low media spend versus acquiring growth through M&A or deep discounting.
Contrarian view: consensus will likely dismiss this as PR, and that is probably correct on near-term P&L. The real catalyst is scanner data over the next 1-3 months; if the limited-edition SKU lifts velocity and expands distribution, the market could re-rate DEO's U.S. beer contribution as a more durable growth pocket. Falsifiers are simple: no observable share gain in premium stout, weak fall sell-through, or evidence that the activation is just inventory stuffing rather than consumption growth.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade in DEO on the announcement alone; wait for Nielsen/IRI data over the next 4-6 weeks before underwriting any earnings impact.
- If U.S. premium stout share improves, consider a 3-month pair: long DEO / short TAP, targeting modest relative outperformance as Guinness takes occasion share from domestic premium beer.
- Use SAM as the cleaner contrarian short if craft-beer shelf space appears to be displaced by Guinness activations; stop the trade if fall sell-through data does not confirm substitution.
- Fade any 1-2 day pop in DEO unless it is accompanied by hard volume data; the headline is likely too small to justify multiple expansion on its own.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Bank of America is bullish on these top stocks ahead of earnings
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Why This Canadian Community Is Betting on Coal Again