
Tyfone Creates One Unified Platform for Digital Acquisition, Lending, and Banking Through ATTUNE Acquisition
Source: PR Newswire
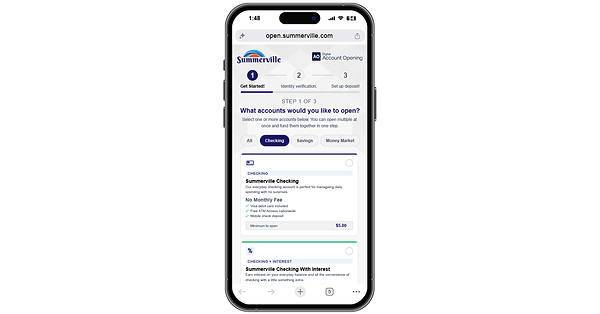
Tyfone announced the acquisition of ATTUNE to create a unified platform for digital account opening, loan origination/servicing, and AI-powered digital banking engagement. The deal expands Tyfone’s Digital Lending capabilities (including Quick Pay, Skip-a-Pay, and collections) and establishes ATTUNE’s account opening and origination tech as foundational pillars of Tyfone’s Loanovia lending lifecycle platform. Management frames the move as reducing fragmented point solutions and improving deployment flexibility without a costly rip-and-replace.
Analysis
This is a modestly bullish signal for integrated fintech platforms and a negative read-through for narrow point solutions. In community banking, the economic winner is usually the vendor that controls the workflow and renewal relationship, not the one with the best single module; that favors scaled software names such as JKHY and QTWO over smaller account-opening/origination specialists. The second-order effect is higher switching costs and less appetite for best-of-breed stacks, which can compress the addressable market for niche vendors even if top-line growth remains steady.
The market impact should be limited near-term because bank software adoption is slow and procurement is risk-averse. The first real catalyst window is 1-3 quarters, when management teams begin to discuss attach rates, implementation speed, and whether bundled workflows lift deposit conversion or loan pull-through. If those metrics do not improve, this will read as a private-company roll-up with little public-market consequence.
Contrarian view: the consensus may overestimate the monetization benefit of a 'single platform' message. Community FIs often care more about uptime, compliance, and integration risk than feature breadth, so consolidation can improve retention at the margin without materially changing TAM or multiples. The main falsifier is evidence that integrated onboarding actually shortens sales cycles or lifts net revenue retention; absent that, the tradeable signal is weak.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate trade in AURT/FISI/INSO on this headline; treat it as a watch item unless next bank-tech updates show measurable expense savings or faster digital account growth.
- Use pullbacks to stay constructive JKHY over the next 3-6 months; the thesis is that suite breadth and lower churn should earn a premium if community FI budgets keep consolidating. Falsify on slower bookings or weaker renewals.
- Watch QTWO as a relative winner versus smaller onboarding/origination vendors; if the market starts paying for platform depth again, QTWO should outperform point-solution fintechs. Reduce if community-bank sales cycles lengthen in the next two quarters.
- Consider a cautious long KRE / short niche fintech basket only if subsequent checks show pricing pressure on fragmented vendors; otherwise do not force the trade. This is a low-conviction catalyst, not a standalone macro signal.
More News
- AI Capex, Gamble or Jackpot?: Market Snapshot
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- Hybe shares jump 10% as K-pop sensation BTS' tour lifts earnings hopes
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’