
Economic Uncertainty Extending Sales Cycles in Used Heavy Equipment Market
Source: PR Newswire
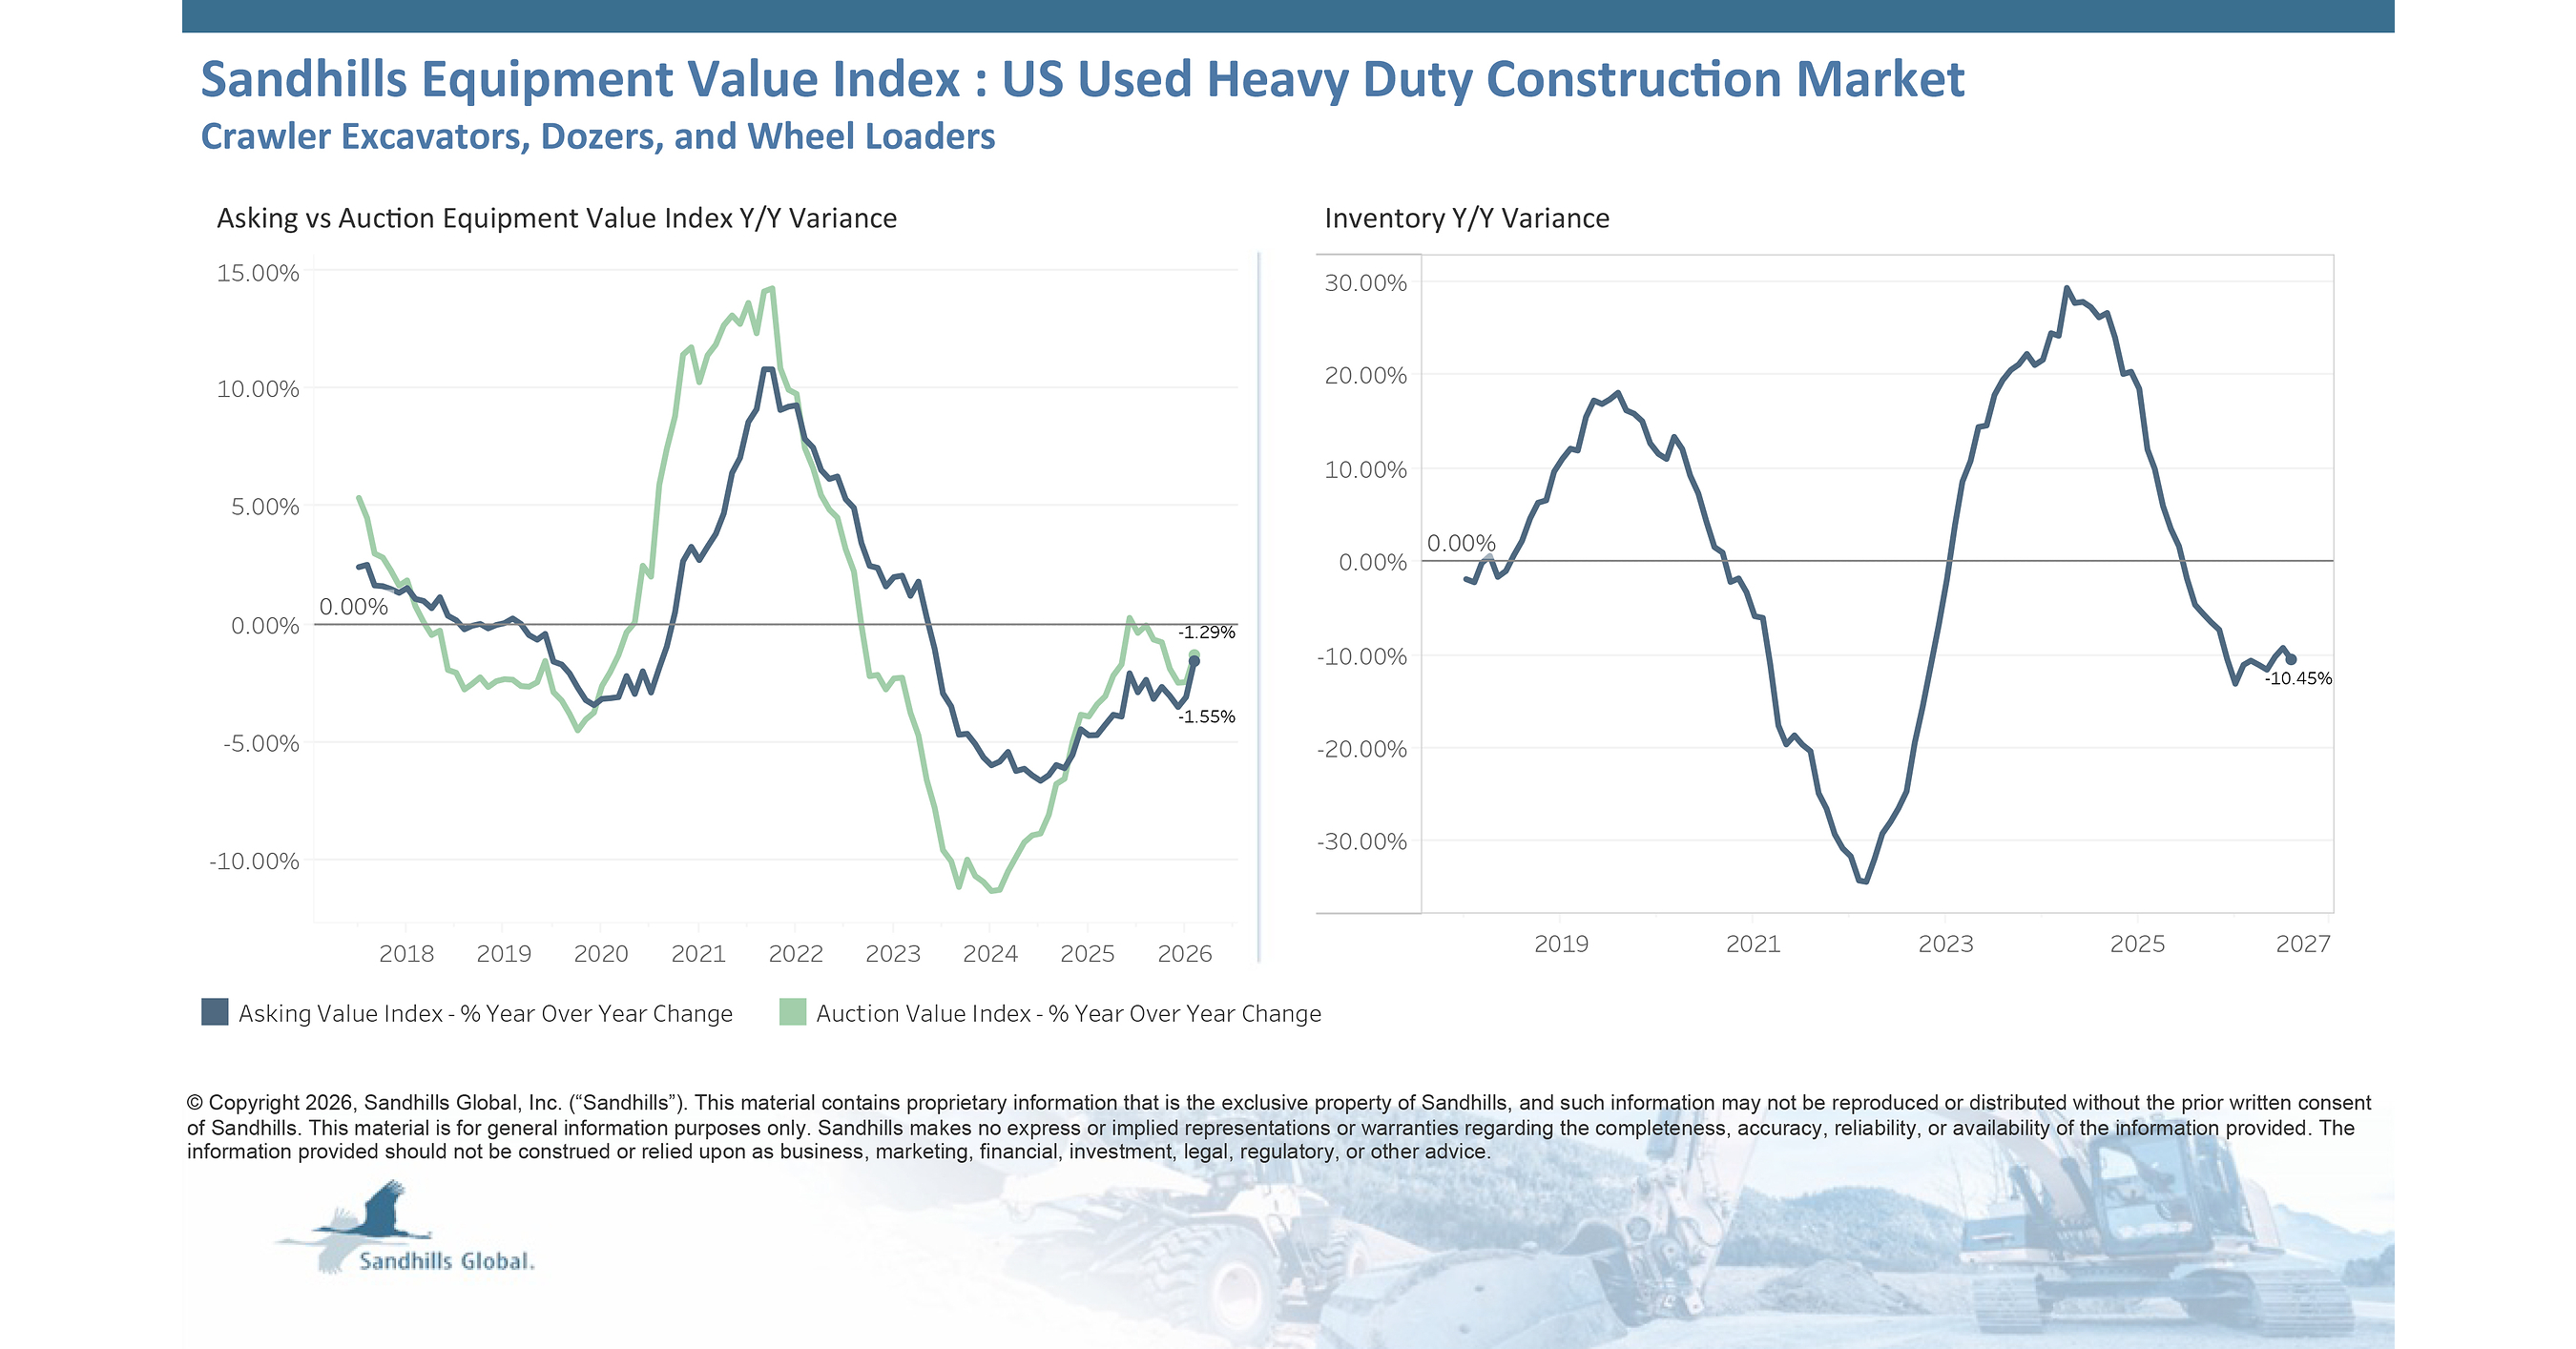
Sandhills’ Equipment Value Index (EVI) shows used equipment inventory tightening across multiple categories in August, led by declines like used heavy-duty construction equipment inventory down 2.56% M/M (-10.45% Y/Y) and used tractors (≥100hp) down 0.96% M/M (-15.49% Y/Y). Pricing is mixed: asking values were slightly up in some segments (e.g., heavy-duty construction asking +0.52% M/M) but auction values are generally flat to down on a yearly basis (e.g., heavy-duty construction auction +0.31% M/M, -1.29% Y/Y). Overall, the data suggest selective support for used-asset pricing but a broader trend of lower supply and continued YoY softness in several end markets.
Analysis
This is not a clean HPQ trade. The signal is really about residual values and dealer inventory discipline in capital goods, which matters most for OEMs, lenders, and fleet buyers; HPQ only gets a second-order read-through if tighter capex budgets spill into SMB purchasing broadly. For now, that channel looks too diffuse to justify positioning HPQ off this report alone.
The more interesting mechanism is that firmer used values alongside falling inventories typically improve trade-in economics and can support new-equipment pricing power over the next 1-3 months. That is constructive for names with direct exposure to replacement cycles and captive finance, but it can also be supply-driven: if availability is tight rather than end-demand is improving, the benefit to OEM bookings may fade quickly. Watch for any follow-through in dealer inventories and order commentary before extrapolating.
Contrarian view: consensus may be reading this as a broad cyclical green light, when the best-supported conclusion is narrower and less durable. If freight volumes, ag yields, or construction activity don’t improve, used values can stall and reverse despite lower inventory, which would unwind the bullish read-through within a quarter. For HPQ specifically, the falsifier is simple: if SMB spend and printer/PC channel checks stay soft, this macro data won’t matter.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.15
Key Decisions for Investors
- No direct trade in HPQ on this print; keep HPQ at neutral and wait for SMB demand evidence in the next earnings cycle rather than forcing a macro read-through.
- Use the report as a modestly constructive setup for CAT and PCAR on 1-3 month horizon; buy on pullbacks if dealer inventory commentary stays tight, with risk defined by any order backlog or pricing deterioration.
- Relative-value idea: long PCAR / short R for 4-8 weeks if you want to express tighter used truck supply versus a less asset-sensitive logistics name; exit if freight activity or used-truck auction values roll over.
- Set an alert on HPQ channel checks and North America SMB capex commentary; if those soften, treat this as confirmation to avoid adding to HPQ despite any broader industrial optimism.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Indonesia Said to Meet Monday With MSCI Over Shock Index Threat
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
- Daiichi Life Offers to Buy Remainder of Australia’s Challenger