
Equity Metals Announces a Significant Increase to the Mineral Resource Estimate at the Silver Queen Project, BC
Source: feeds.newsfilecorp.com
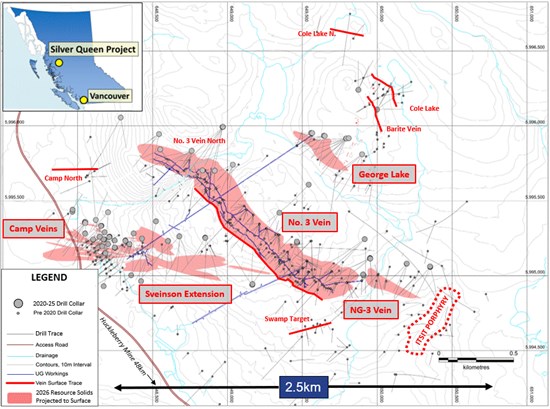
Equity Metals' updated NI 43-101 resource estimate for its Silver Queen project increased Inferred tonnage 169% to 5.16Mt, containing 35.0Moz AgEq (529koz AuEq), while Indicated resources rose 3% to 3.57Mt containing 48.7Moz AgEq (737koz AuEq). The estimate incorporates 87 additional drill holes and adds George Lake mineralization, with Indicated grades of 425g/t AgEq and Inferred grades of 211g/t AgEq at a C$122/t NSR cutoff. The substantial expansion improves the project's development potential, although the resources are not reserves and Inferred material remains speculative pending further drilling and economic studies.
Analysis
The valuation relevance is not the headline resource growth but the confidence mix: most incremental metal is lower-grade Inferred material, while the higher-grade Indicated inventory remains the only credible near-term foundation for a preliminary economic assessment. A meaningful rerating requires conversion drilling and a mine plan demonstrating that narrow-vein selectivity, dilution and development intensity do not consume the apparent grade advantage. The stated cut-off is also built on constructive long-term metal-price assumptions, leaving economic sensitivity especially acute to zinc and silver prices and underground operating-cost inflation.
Near term, EQTY may receive a liquidity-driven TSXV exploration-junior bid, but resource updates alone rarely sustain it beyond days without a funded work program, PEA timetable, and cash-burn disclosure. The technical report due within 45 days is the first diligence catalyst: watch for reconciliation between optimized shapes, recovery assumptions and mineable widths, plus any caveat around historical workings. A negative read-through would be lower recoveries, higher assumed mining cost, or evidence that the expanded inventory is too spatially fragmented for efficient sequencing.
The contrarian view is that infrastructure and no-royalty attributes may be more valuable than the headline equivalent-ounce figure, but only if the company can prove a compact initial mining area with manageable capex. Conversely, the polymetallic mix can reduce pure precious-metals beta: treatment charges, concentrate penalties and zinc/lead-cycle weakness may dilute upside even if gold and silver remain firm. This is a high-risk microcap optionality situation rather than a direct read-through for larger Canadian silver producers such as MAG or FRES.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- Do not chase an initial EQTY gap-up; place on watch for the NI 43-101 technical report within 45 days and initiate only if it confirms economics at conservative spot/forward assumptions and management provides a fully funded 12-month conversion-drilling plan.
- For a speculative position, limit EQTY to venture-basket sizing and use a 3-6 month horizon targeting a PEA commitment or Indicated-resource conversion catalyst; exit on a financing at a material discount, a delay to the technical report, or disclosure of materially higher underground mining costs than the resource-model assumption.
- Express the macro component separately through SIL or physical-silver exposure rather than treating EQTY as a clean silver proxy; EQTY's equity outcome is more sensitive to dilution, metallurgy, and underground execution than to a modest silver-price increase.
- Monitor zinc treatment charges and silver/zinc prices over the next 1-3 months. A sustained decline in zinc pricing or rising concentrate treatment charges would warrant reducing exposure because base-metal credits support project NSR and potential operating margins.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- US military claims Strait of Hormuz remains open amid ongoing blockade
- Oil prices extend losses as fears of Middle East supply disruptions ease
- Why is Weichai Power stock rallying today?
- Fed hikes again - an AI-Picked insurer is still cashing in
- Shares tick higher as Fed hikes rates, dollar jumps with short-term yields