
Owl Ventures Welcomes NBA Legend Chris Paul as Venture Partner
Source: PR Newswire
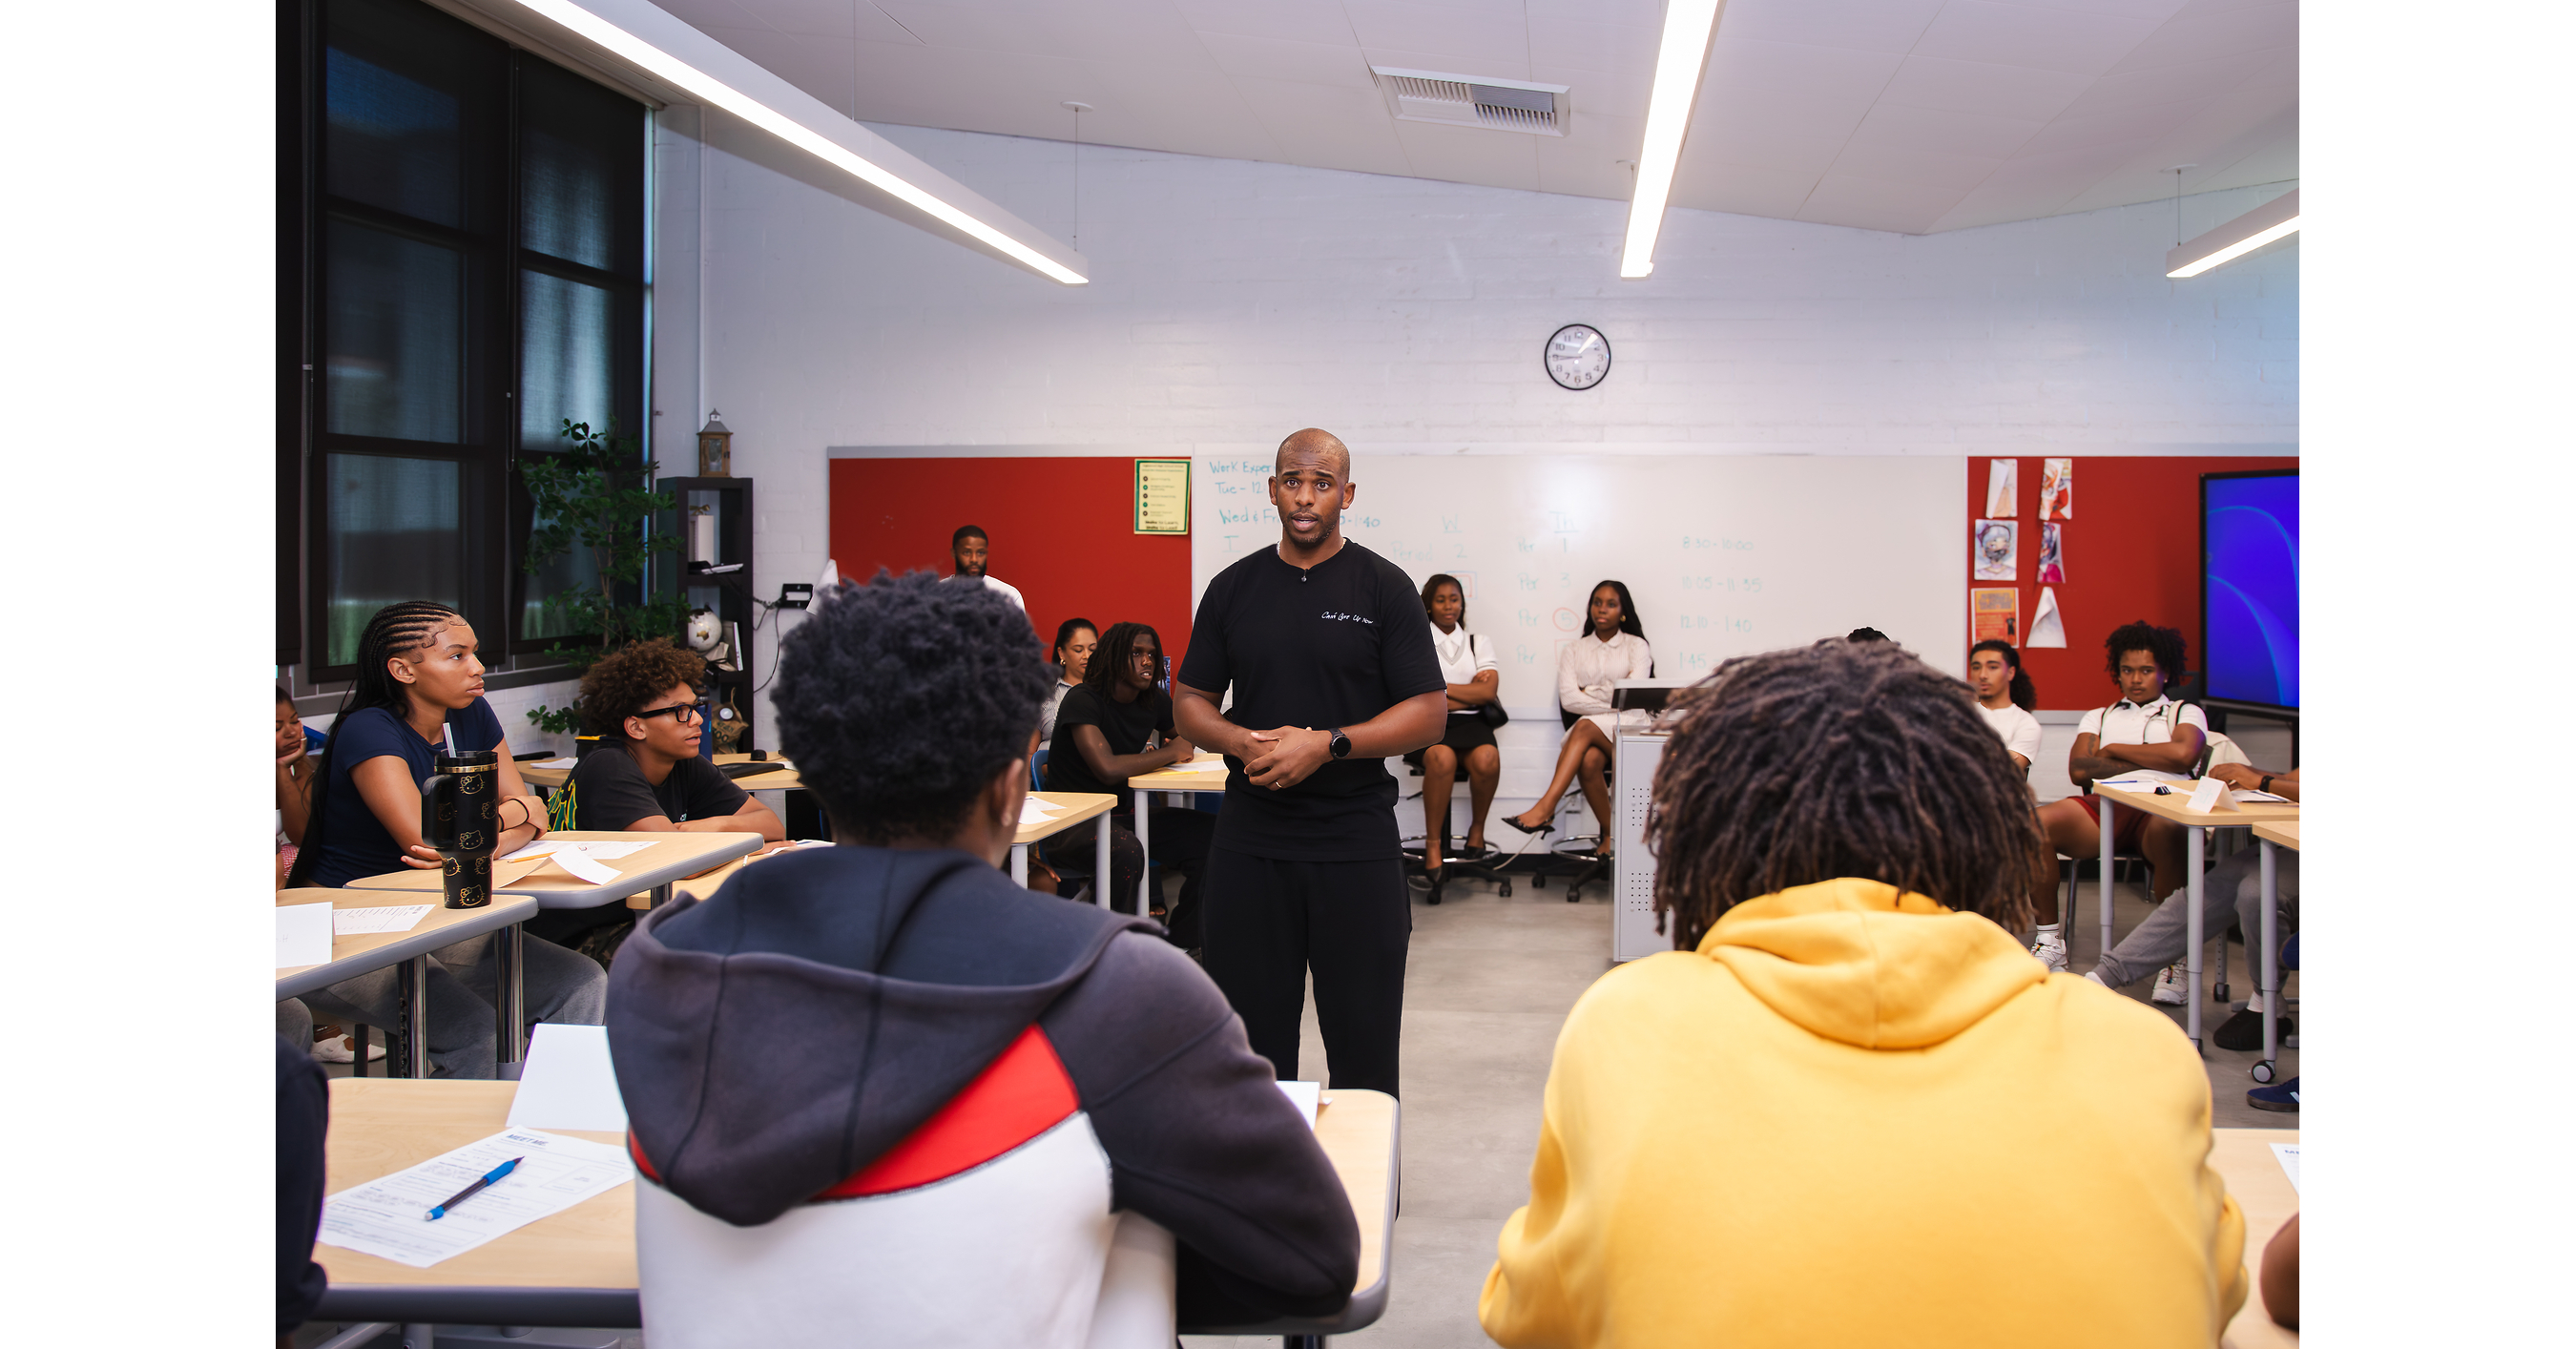
Owl Ventures appointed NBA legend and entrepreneur Chris Paul as a venture partner to support founders and expand strategic relationships across its education and workforce-technology portfolio. The firm manages more than $2.2 billion of committed capital, has made over 100 investments, and says its portfolio companies reach more than 700 million users globally. The appointment reinforces Owl's focus on lifelong learning and workforce innovation as AI reshapes skills development and careers, but it is not a material near-term market-moving event.
Analysis
This is a branding and sourcing signal for private edtech rather than a valuation-relevant event for public markets. A high-profile venture partner can improve access to athlete, HBCU, employer, and community distribution channels, but it does not establish incremental fund capacity, portfolio-company contracts, or monetization. The near-term implication is likely greater competition for early-stage workforce and AI-learning deals, particularly companies selling credentialing, financial-literacy, coaching, and career-navigation products to underserved populations.
The more investable second-order issue is whether celebrity-led distribution becomes a substitute for paid customer acquisition in a category where many AI-learning companies face weak retention and high enterprise sales friction. Public beneficiaries would only emerge if portfolio companies demonstrate that community-led channels convert into employer-paid recurring revenue; absent that proof, the announcement should not alter earnings assumptions for listed education or HR-software names. Watch private funding rounds and employer partnerships over the next 6-12 months for evidence of a bid-up in workforce-tech valuations or a differentiated go-to-market model.
Contrarian view: the market routinely overvalues audience access in education technology. Learner engagement may rise, but procurement, credential recognition, and measurable wage outcomes—not awareness—determine durable revenue and exit multiples. There is no actionable public-equity signal from this release alone; the relevant catalyst would be a disclosed strategic partnership, portfolio-company financing, or distribution agreement with measurable unit economics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No standalone public-market trade: treat this as a private-market monitoring item, not an earnings catalyst.
- Set an alert for disclosed Owl portfolio financings or enterprise partnerships in AI workforce training over the next 3-6 months; compare valuation step-ups against retention, employer renewal rates, and customer-acquisition costs before inferring a sector read-through.
- For private-market exposure, avoid paying a premium for celebrity-affiliated workforce-tech companies without evidence that partner-driven leads convert to contracted employer revenue; require cohort retention and placement/outcome data.
- Monitor public workforce-software proxies such as Coursera (COUR), Udemy (UDMY), and Strategic Education (STRA) only if AI credentialing or employer-channel announcements create a measurable competitive overlap; falsify any negative read-through if their enterprise bookings and net retention remain stable.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- How Kevin Warsh’s rate hike exposed a 2-speed U.S. economy, with AI and housing at the poles
- Xi-Trump Summit Agenda: AI, Tariffs, Critical Minerals, Iran War, Taiwan
- U.S. regulators rush to write crypto rulebook after Clarity Act stalls in Senate