
Niutech completa la reestructuración del grupo
Source: PR Newswire
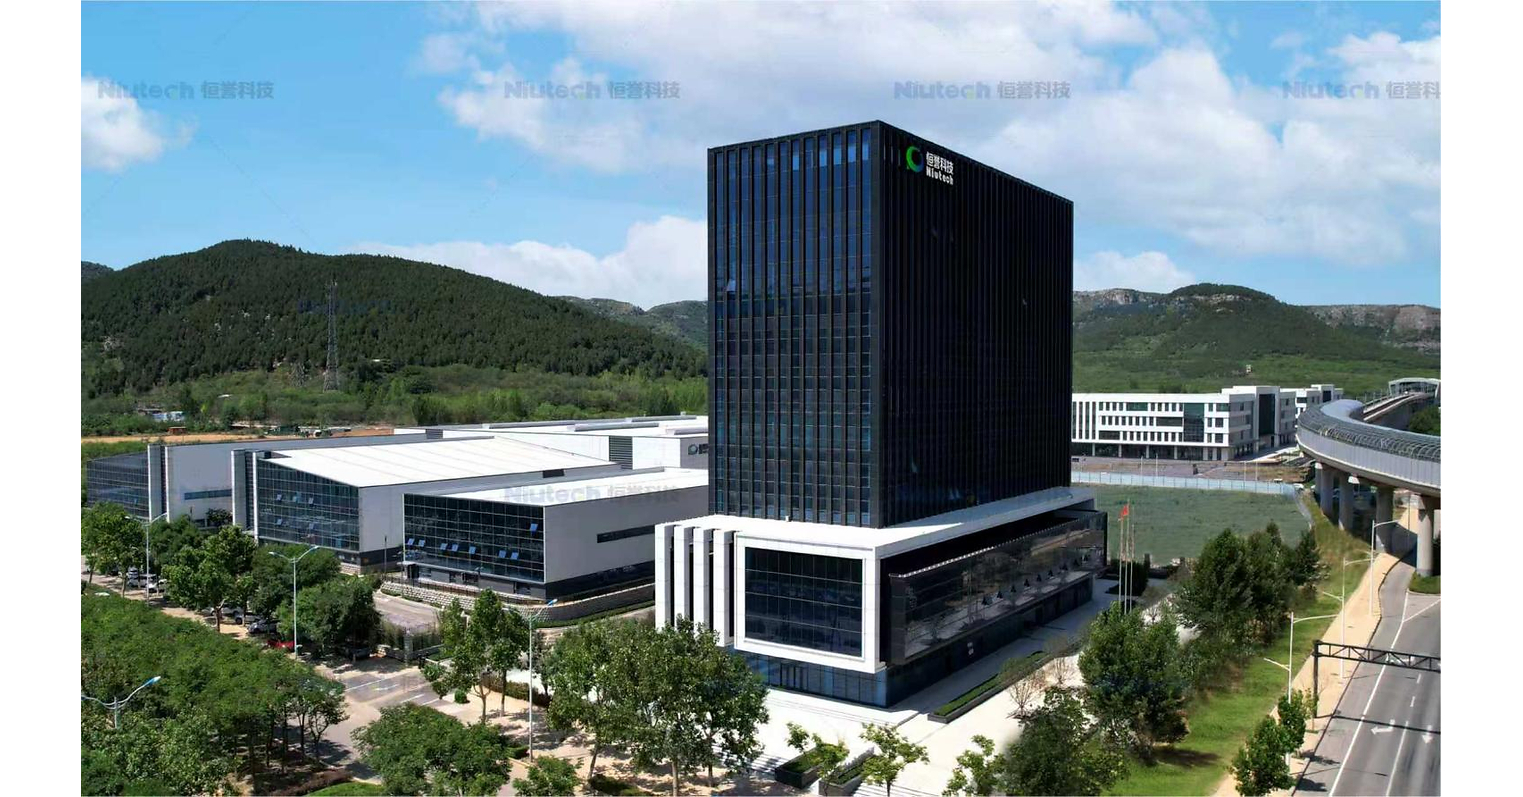
Niutech completed its group restructuring on August 26, 2026, expanding its registered scope into resource-recycling R&D, specialized equipment manufacturing and new materials. Its Phase II Hesheng Environmental Protection project is expected to lift annual capacity to 160,000 tonnes in 2026, including 100,000 tonnes from the new phase, while a UK customer placed a RMB198 million order after benchmarking Niutech against international competitors. The company is positioning its >100-tonnes-per-day continuous pyrolysis systems to benefit from EU recycled-content regulations and is developing tire-pyrolysis oil pathways toward sustainable aviation fuel.
Analysis
The investable read-through is less about Niutech's corporate reorganization than whether chemical-recycling capacity can secure bankable feedstock and offtake contracts under tightening European recycled-content rules. Equipment suppliers with demonstrated operating references can gain share as project developers and tire makers seek to de-risk permitting and throughput assumptions; European pure plays Pyrum Innovations (PYRUM.DE) and Scandinavian Enviro Systems (SEV.ST) face tougher competition if lower-cost Chinese systems meet EU product-quality, emissions, and traceability standards. Conversely, recovered-carbon-black producers could pressure virgin carbon-black pricing and create a modest raw-material-cost offset for tire manufacturers such as Michelin (ML.PA), Continental (CON.DE), and Pirelli (PIRC.MI), but only once qualified material is incorporated into production recipes.
Near term, this is not a broad listed-equity catalyst: a single overseas equipment order does not establish recurring revenue, project margins, or cash conversion for 688309. The key 1-3 month diligence item is independently disclosed order backlog, deposit/payment terms, and third-party verification that output qualifies for ISCC/European offtake specifications; without these, the announcement should not command a re-rating. Over 6-18 months, the bottleneck is likely not reactor capacity but economically collected waste feedstock, permitting, and whether pyrolysis oil can consistently clear refinery co-processing and mass-balance certification requirements. The contrarian risk is that policy favors recycled-content accounting, but customers may still choose mechanical recycling or imported certified feedstock when chemical-recycling oil trades at a premium to fossil naphtha.
For incumbent chemical players, BASF (BAS.DE) and Neste (NESTE.HE) are better positioned to monetize certified circular feedstocks through existing customer qualification and refining infrastructure, while smaller technology vendors retain disproportionate execution and financing risk. A sustained decline in fossil naphtha or weaker EU implementation of recycled-content mandates would compress the green premium and undermine the economics of incremental pyrolysis projects.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No immediate position in Niutech (688309) based solely on the release; place on watch for audited backlog, export gross margin, and operating-cash-flow disclosure at the next results. Consider a tactical long only if disclosed contracted backlog materially exceeds annual revenue and customer deposits support working capital.
- Monitor a 6-18 month relative-value basket: long BAS.DE or NESTE.HE versus PYRUM.DE, sized small, if certified pyrolysis-oil demand accelerates. Incumbents have downstream certification and offtake advantages; invalidate if Pyrum demonstrates sustained utilization, positive project-level cash generation, and comparable feedstock economics.
- Watch ML.PA and PIRC.MI for qualified recovered-carbon-black adoption rather than buying on equipment announcements. A verified increase in recycled-carbon-black content without tire-price concessions would be a margin-positive catalyst; failure to achieve performance qualification is the principal downside.
- Set alerts for EU PPWR/ELV implementation milestones and European naphtha prices. Delayed enforcement or a material naphtha-price decline would weaken circular-feedstock premiums and is a reason to avoid or reduce exposure to chemical-recycling developers.
More News
- Paramount Skydance prices $42 billion debt for Warner Bros deal
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- California Gov. Gavin Newsom bans AI 'robo bosses' in landmark state law, reversing his earlier veto
- The new and huger Paramount has a new co-CEO
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- US judge approves settlement allowing Paramount to acquire Warner Bros