
Civitas Reaches Key EB-5 Milestone With I-956F Filing for The Summit in Avon, Colorado
Source: PR Newswire
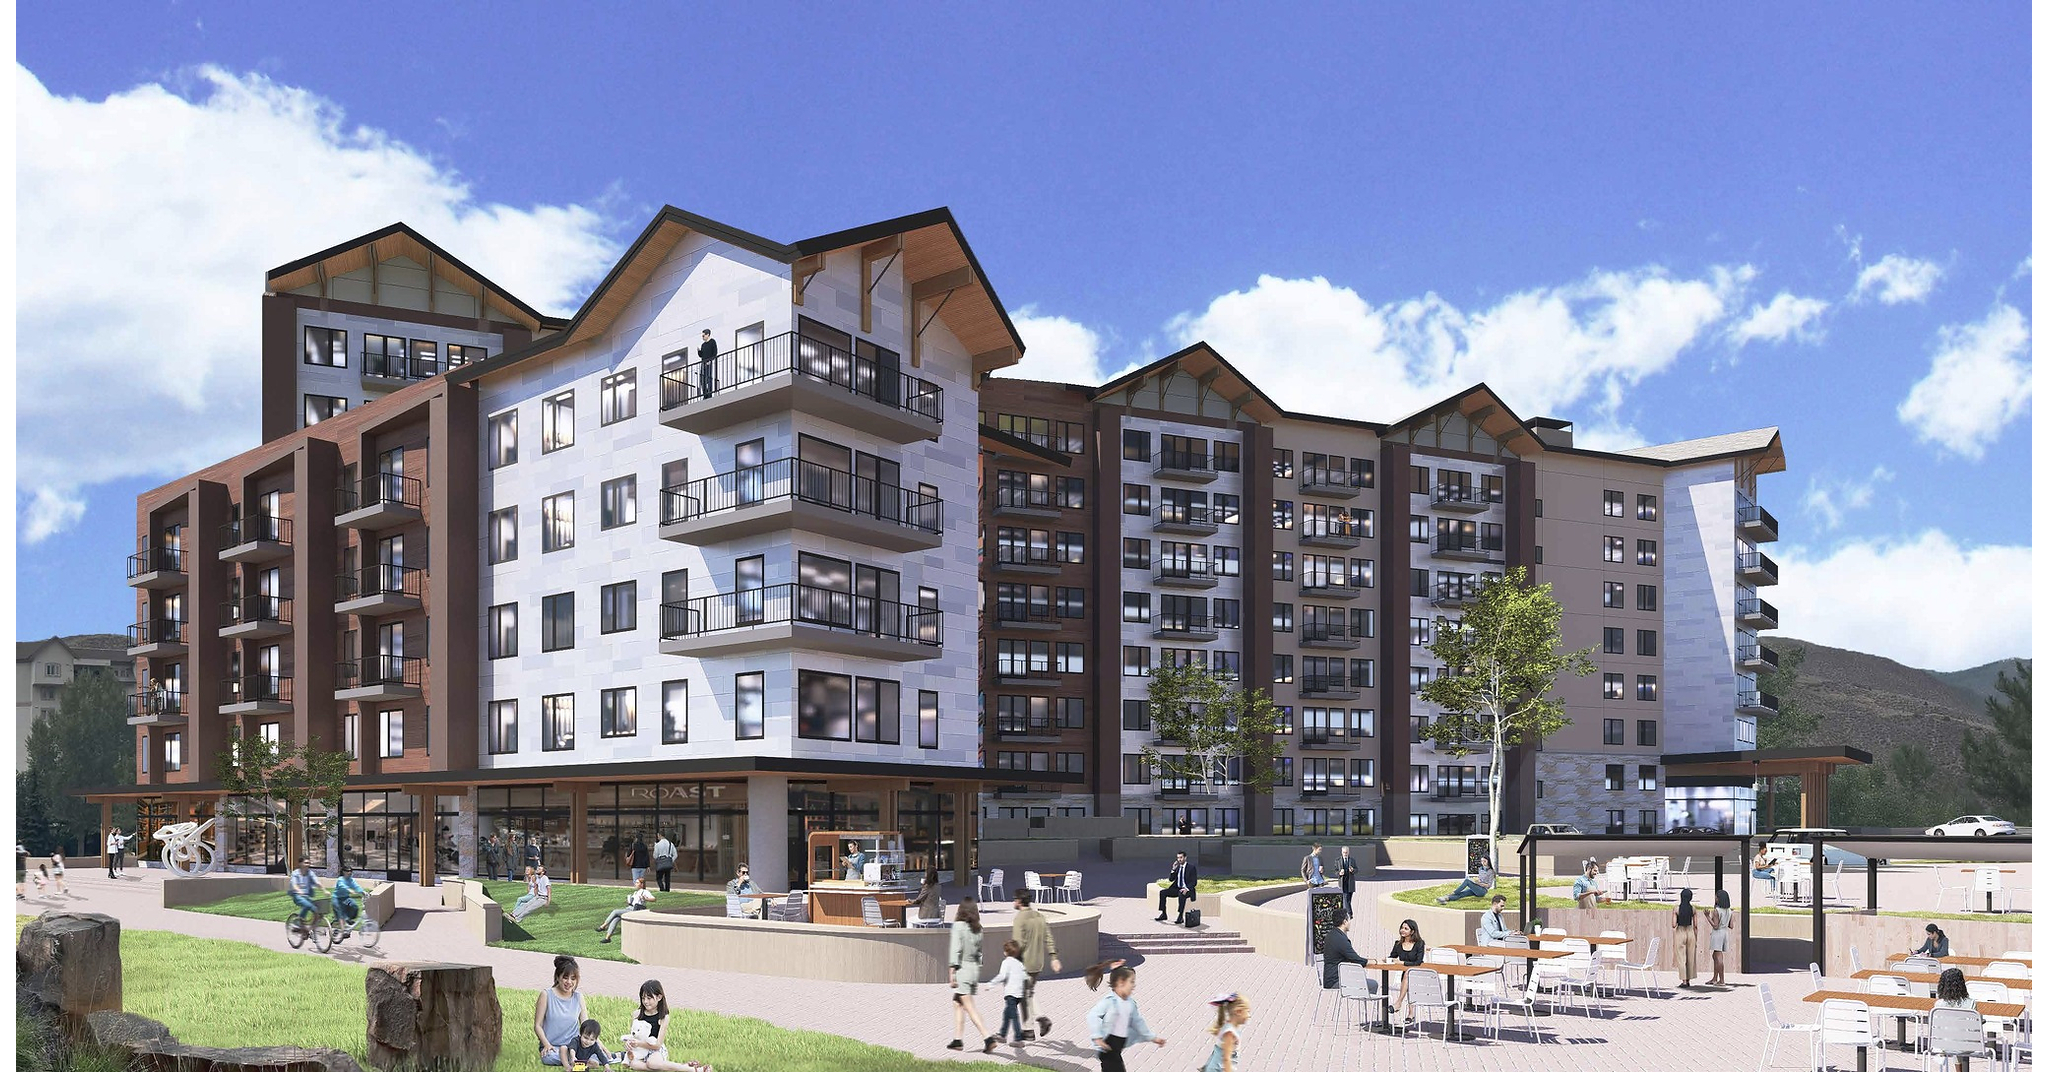
Civitas Capital Group filed Form I-956F with USCIS for The Summit, a 164-unit multifamily project in downtown Avon, Colorado, advancing it toward EB-5 availability. The project qualifies as a rural TEA, enabling the reduced $800,000 EB-5 investment level (vs. $1.05 million) and targeting expedited I-526E processing, with construction already funded via a $104 million senior construction loan. With Town of Avon public financing of up to $11.84 million and construction slated to begin in Q3 2026, management expects demand for ~100 EB-5 investor placements as filings accelerate into year-end.
Analysis
This is more a financing de-risk event than an operating inflection for public equities. The real winners are the project sponsor, local subcontractors, and the senior lender because the capital stack is now sufficiently assembled to move from paper asset to dirt-turning; that reduces the odds of a stalled site and improves takeout optionality. For public comps, the only plausible second-order beneficiary is MTN: in resort towns, workforce housing is a margin issue, not a philanthropy issue, so incremental supply can modestly ease wage inflation and turnover pressure over the next 12-24 months.
The market should not extrapolate this into a broad read-through for Colorado multifamily or hospitality. EB-5 is a niche, policy-dependent funding channel; the near-term catalyst is administrative filing velocity, while the structural catalyst is whether rural visa allocations keep absorbing demand without a change in immigration rules. If USCIS processing tightens, or if year-end filing demand proves more about timing arbitrage than durable capital formation, the financing narrative can unwind quickly even if construction still proceeds.
Contrarian takeaway: the embedded subsidy here may be signaling persistent labor scarcity, not a solved housing problem. If the project succeeds, it could slightly compress rent growth for nearby employer housing stock while improving resort staffing reliability — a subtle positive for operators and a negative for existing local landlords. But the public-market impact is too small for a directional trade unless MTN starts discussing measurable labor-cost relief or occupancy improvement tied to new workforce supply.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate standalone trade in AVNBF/CGHC/FCD.UN.TO/V/V-related names; treat this as a private-capital/local real estate financing story with limited public-equity transmission.
- Watch MTN over the next 1-3 quarters for commentary on employee housing availability, wage pressure, and seasonal staffing. If management cites improving labor retention or lower housing support costs, that would be a small fundamental positive.
- Use as an alert for Colorado resort-market multifamily/lodging comps rather than a trade signal. A broader short in local landlords only makes sense if multiple projects convert from financing announcements to actual delivered supply.
- Falsifier for the benign view: any USCIS policy change, rural TEA interpretation shift, or delayed construction start that blocks EB-5 closings would undermine the capital-stack de-risking thesis within 1-6 months.
More News
- Ramp reaches $60B valuation as it pushes deeper into AI
- Indonesia stocks suffer biggest daily slump since 1998 as MSCI weighs downgrade
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- UK's Healey Plans to Raise Bank Taxes
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- The IPO drought is driving private equity-owned companies to the debt market to pay investors