
Envision Energy lanza el aerogenerador terrestre Model T
Source: PR Newswire
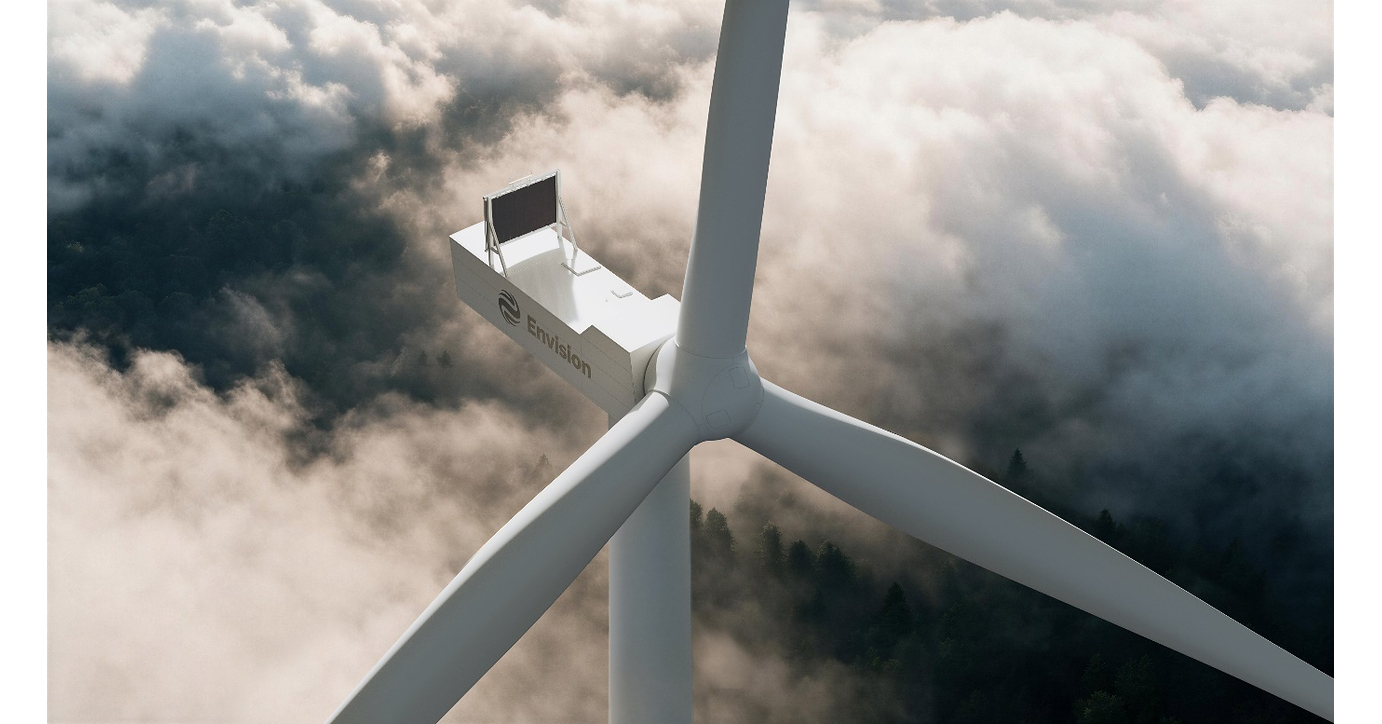
Envision Energy launched its Model T EN175/8.0 onshore wind turbine, featuring 8 MW of rated capacity and a 175-meter rotor for moderate-wind and complex operating sites. The company says the turbine can improve energy yield by 2%-12% versus existing models, while targeting 107 dB(A) acoustic power and offering optional low-noise and blade anti-icing configurations. Its AI-driven Galileo control system is designed to autonomously optimize operations and provide grid-forming support, extending optimization across wind, solar, storage and industrial loads.
Analysis
The commercial read-through is more negative for Western turbine OEMs than for renewable developers. An 8 MW low/medium-wind product with vertically controlled drivetrain inputs targets the segment where Vestas (VWS.CO), Siemens Energy’s Siemens Gamesa (ENR.DE), and GE Vernova (GE) need pricing discipline to restore service and equipment margins. If Envision can translate claimed plant-level optimization into lower availability risk and better realized generation, it raises the probability of competitive tender pricing in Europe and emerging markets during the next 6-18 months; the more immediate effect is likely procurement leverage for developers rather than a material shift in installed capacity.
The AI framing should not yet command a valuation premium: incremental output, maintenance savings, and grid-support revenues must be independently demonstrated in operating fleets across seasons. The more investable implication is that grid-forming capability becomes a gating requirement in weak-grid markets, potentially shifting value from turbine hardware toward project controls, storage, and power-electronics integration. This supports selective exposure to Fluence (FLNC) and Nextracker (NXT) only where renewable build-outs are paired with storage/grid upgrades, while pure turbine OEM margins remain exposed to warranty, logistics, and financing costs.
Contrarian view: the launch may be strategically important but is not itself evidence of near-term share loss for listed peers. Certification, bankability, local-content compliance, service-network depth, and financing availability typically determine awards more than nameplate specifications. The thesis turns materially more bearish for VWS.CO/ENR.DE only if European tender data over the next 1-3 quarters show Envision winning meaningful projects outside its existing core markets, or if peer order pricing and service-margin guidance weaken.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- Maintain a 6-12 month underweight bias on VWS.CO versus GE: use any product-launch-driven optimism in turbine OEMs to favor long GE / short VWS.CO, as GE’s grid and electrification mix offers better insulation from onshore equipment price competition. Exit if Vestas demonstrates sustained order-price improvement and service EBIT margin expansion in two consecutive reports.
- Do not initiate a directional trade solely on this launch. Set an alert for European or Middle Eastern awards to Envision above 1 GW over the next two quarters; confirmed wins would justify reassessing a short basket of VWS.CO and ENR.DE, particularly if accompanied by lower disclosed average selling prices.
- For renewable-infrastructure exposure over 6-18 months, prefer NXT or a selective FLNC position over standalone turbine OEMs, conditional on backlog conversion and gross-margin guidance. The risk is delayed interconnection, storage oversupply, or policy-driven project cancellations; invalidate on material backlog reductions or negative free-cash-flow guidance.
- Monitor grid-code and capacity-market rules in weak-grid jurisdictions over the next 3-12 months. Mandates for grid-forming operation would increase the strategic value of controls and storage integration, but absence of enforceable compensation mechanisms would limit monetization and leave the feature as an unrewarded capex burden.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Boom or bust? The case for and against panicking about 5% yields
- Bond market alarms are ringing on Wall Street. Here's what's ahead
- Houthi attack on Mecca, Medina would cross ‘red line’, Pakistan PM tells UN
- Shares of Akamai surge after deal with Anthropic. What Wall Street is saying
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market
- Investment Research Software Costs: A 2026 Budget Framework