
Bessent Takes Trump’s Economic Pitch to a Skeptical G20
Source: Bloomberg
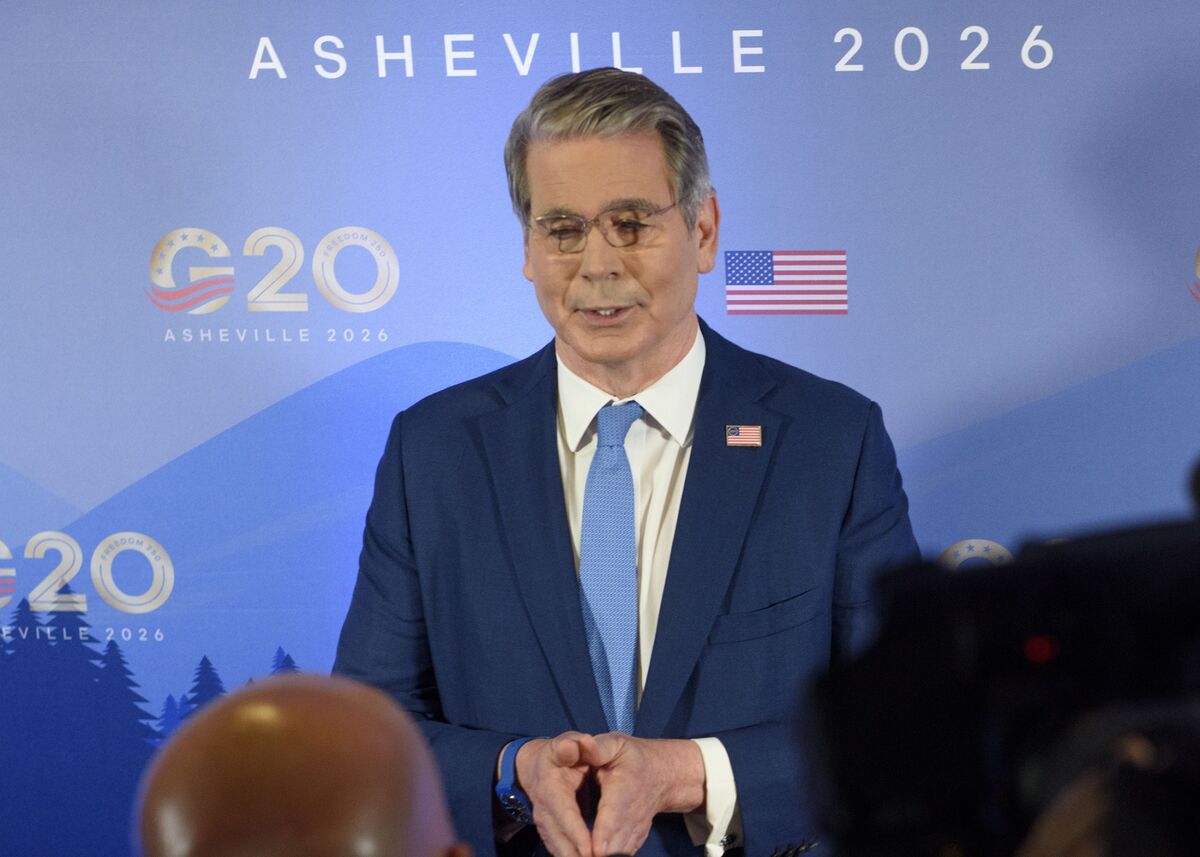
The article frames upcoming G20 finance-minister meetings as a difficult moment for President Trump’s economic agenda, highlighting skepticism among allies about the US growth prescription. No specific policy numbers, forecasts, or market-moving decisions are provided, so the immediate impact is likely limited.
Analysis
This kind of headline is only tradable if it changes expectations for policy follow-through. The market mechanism is less about diplomacy and more about whether investors infer a less credible growth mix, which would nudge the term premium higher and make long-duration assets more fragile over the next 1-3 months. In that setup, the first beneficiaries are domestic financials and value-heavy sectors that can absorb higher rates; the first losers are rate-sensitive cyclicals and import-dependent businesses that rely on stable global demand.
The second-order effect is a possible shift toward more confrontational trade language if the administration needs to reassert leverage after a weak reception abroad. That would be negative for semis, industrials, and retailers with global supply chains, and it would also compress multiples for politically exposed names like DJT because the stock trades more on narrative momentum than cash-flow durability. But absent a concrete policy escalation, this is still mostly headline beta, not a fundamental earnings event.
The contrarian view is that the consensus may overread elite skepticism: markets usually ignore these episodes unless they show up in Treasury auctions, dollar funding, or actual budget negotiations. Falsifiers are straightforward: softer inflation, strong auction demand, or a quick de-escalation in trade rhetoric would unwind any higher-yield/defensive rotation within days. Over 6-18 months, the real watch item is whether the fiscal message affects foreign capital willingness to fund the U.S. deficit; if not, this is just election noise.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No new outright long in DJT on this headline; use any intraday strength over the next 1-5 sessions to reduce or hedge existing exposure, since the tape is narrative-driven but the fundamental linkage is weak.
- If fiscal rhetoric hardens and Treasury auctions weaken, initiate a tactical long TLT / short IWM pair for 1-3 months; the trade works if higher term premium hits small caps and long-duration assets before any policy reversal.
- Relative-value long XLF vs XLI or XLY for the next 1-3 months if markets start pricing a higher-for-longer rate path and softer global demand; cut the trade if auction demand improves or Treasury yields back off.
- Watch item: if the 10Y yield moves higher on deficit or policy comments, consider adding downside hedges in rate-sensitive growth exposure rather than chasing DJT volatility.
More News
- Ukraine to resume strikes on Russian refineries, shattering hopes of an 'energy ceasefire'
- Chevron CEO warns oil buffers that cushioned the Iran war shock have been ‘drained’—and diesel relief may not come until 2027
- The Houthis’ Saudi attacks are ‘unprecedented.’ Trump wants to ‘ignore’ until the midterms, but the chaos may force U.S. to respond
- Iran’s deputy army chief warns ships not to attempt Hormuz crossings
- US-Iran stalemate: What are Trump’s next military options?
- France is ‘putting the house in order’ and can slash deficit to 3% in three years, central bank governor tells CNBC