
BlueSky At-Home Veterinary Care Launches In-Home Services For Pets In Nashville
Source: PR Newswire
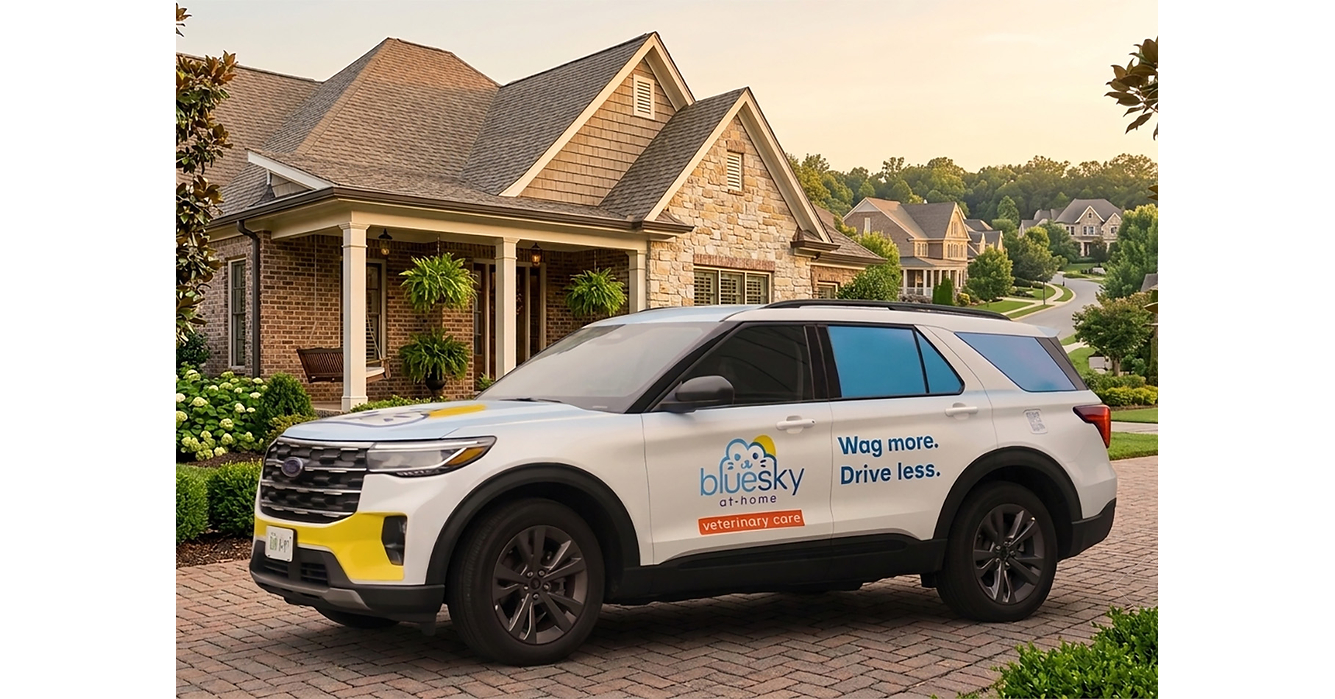
BlueSky At-Home Veterinary Care launches in-home veterinary services in Nashville on September 15, 2026, building on its earlier acquisition of ReadiVet. The company emphasizes low-stress, continuity-of-care visits (including transferring ReadiVet records) and positions preventive care—such as routine bloodwork—as more affordable, with bloodwork chosen by over half of clients in existing markets. Scheduling is available starting immediately via online, phone, or email, but the news is primarily an expansion/branding update with limited expected market-wide financial impact.
Analysis
This is a local competitive move, not a sector re-rating. The real economic question is whether home visits expand the addressable pool of preventive care or merely shift a small slice of high-margin routine visits away from clinics; the winner is the model that can convert convenience into repeat utilization without destroying clinician throughput. If attach rates on bloodwork and follow-ups stay high, third-party diagnostics and refill channels should see the cleanest incremental benefit, while the operator itself still carries the travel-time penalty that caps scalability.
The near-term losers are conventional clinics and retail-vet formats with heavy exposure to wellness exams in affluent ZIP codes, especially where pet owners value convenience over breadth of services. That said, this is likely a gradual share shift, not an overnight shock, because the addressable market is constrained by doctor capacity, scheduling density, and customer acquisition cost. If utilization slips or pricing has to come down to fill calendars, the bullish narrative about premium value breaks quickly.
For public proxies, there is no direct read-through to HSHL or MDCE absent disclosed operating exposure. The cleaner relative expression is that diagnostic and lab platforms are the structural beneficiaries if at-home care lifts preventive testing, while pet retail/vet service operators remain vulnerable if traffic is diverted. A falsifier is simple: if repeat rates and diagnostic attachment do not improve over the next earnings cycle, this becomes a branding story rather than an economic one.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No immediate trade in HSHL or MDCE; treat this as a watch item until there is disclosed revenue linkage, same-store demand data, or management commentary.
- Small relative-value long IDXX / short WOOF over 3-6 months if evidence emerges that at-home care is raising preventive testing mix faster than it is stealing clinic volume.
- If you want broader pet-services exposure, prefer IDXX over clinic-format operators: diagnostics have the better leverage to higher bloodwork attachment and recurring utilization.
- Set an alert for next quarter's vet-services commentary from WOOF/PETS; if home-care convenience is cited as a traffic headwind, use any rally to short the weakest operator on a 1-2 quarter horizon.
- Do not buy the growth story on the launch alone; wait for hard KPIs such as repeat visit rate, bloodwork attach rate, and clinician utilization before taking a directional position.
More News
- Palantir patient data tech rejected by many NHS trusts in England
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Apple’s $1,999 iPhone Duo puts the company's status-symbol power to the test
- Yields continue to rattle investors. These sectors are most at risk if rates stay elevated