
Commercial Bancgroup, Inc. Announces Results for the Third Quarter 2026
Source: Newswire
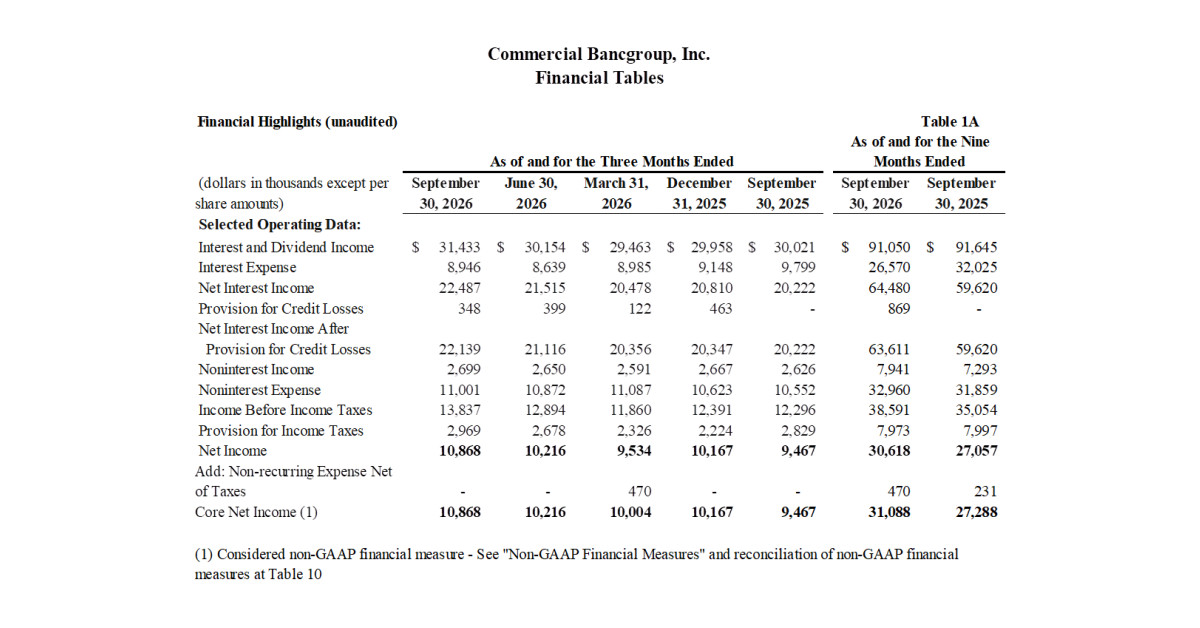
Commercial Bancgroup reported Q3 2026 net income of $10.9 million, up from $9.5 million a year earlier, while diluted EPS rose to $0.79 from $0.77. Net interest margin increased 8 basis points from Q2 to 4.14%, and loans grew 12.2% year over year to $2.0 billion; deposits rose 6.0% to $1.9 billion. Credit metrics remained contained, with net charge-offs at 0.00%, although nonperforming assets increased to 0.31% of assets from 0.27% a year earlier.
Analysis
The strongest signal is operating leverage rather than headline EPS: sequential margin expansion alongside loan growth and a lower efficiency ratio can support earnings if funding costs remain contained. But the per-share comparison is a poor read-through to organic growth: the prior-year quarter preceded the IPO, while the current share base includes it. Verify diluted weighted-average shares and IPO proceeds before interpreting the modest EPS increase as a slowdown in earnings power.
The key second-order risk is funding mix. Loan growth has outpaced deposit growth over the year, and noninterest-bearing deposits have grown more slowly than total deposits; if incremental lending is funded with higher-cost deposits or borrowings, the recent NIM improvement could reverse. Credit remains benign in absolute terms, but NPAs are edging up as the allowance ratio declines. That combination is not yet a stress signal, but it makes underwriting and reserve coverage more important than the low current charge-off rate.
Near term, the release supports a constructive reaction, but valuation and post-IPO trading context are unavailable, so avoid chasing an opening move. Over the next 1–3 months, deposit pricing, loan/deposit and borrowing trends, and credit migration are the decisive catalysts. Over 6–18 months, sustained efficiency and locally sourced deposit growth could distinguish CBK from smaller banks facing funding pressure. The bullish case is falsified by a reversal in NIM, renewed deterioration in NPAs/charge-offs, or funding costs rising faster than asset yields.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Do not trade the EPS headline in isolation. Check the 10-Q for diluted share count, IPO-related capital and proceeds, loan/deposit ratio, borrowings, deposit costs, and reserve composition before updating the earnings run-rate.
- Avoid chasing the initial reaction. If CBK holds its post-release level and subsequent disclosures confirm stable funding costs and credit, consider a modest relative-value long CBK / short KRE position over the next quarter; exit or stand aside if NIM contracts or NPAs and charge-offs worsen. No valuation-based outright buy is justified from this release alone.
- Monitor the next quarter’s deposit mix and pricing, loan growth versus funding growth, and criticized/classified loans. A rise in funding costs without matching asset-yield repricing, or continued reserve coverage reduction alongside credit migration, would invalidate the positive operating-leverage thesis.
More News
- From Wall Street to Silicon Valley, Anthropic IPO poised to have massive 'trickle-down effect'
- Microsoft offers buyouts to nearly 30% of workforce in ongoing AI shift
- Anthropic’s risk factors include the end of humanity, a feud with the Pentagon, and CEO Dario Amodei’s reputation
- Elon Musk warns more than 200 AI cloud companies face ‘guppy-level death’ as the AI boom runs into a debt crisis
- Why is PagSeguro Digital stock plummeting 30% today?
- China industrial profits post strongest growth in three months, rising 14.4%