
/C O R R E C T I O N -- King of Kentucky/
Source: PR Newswire
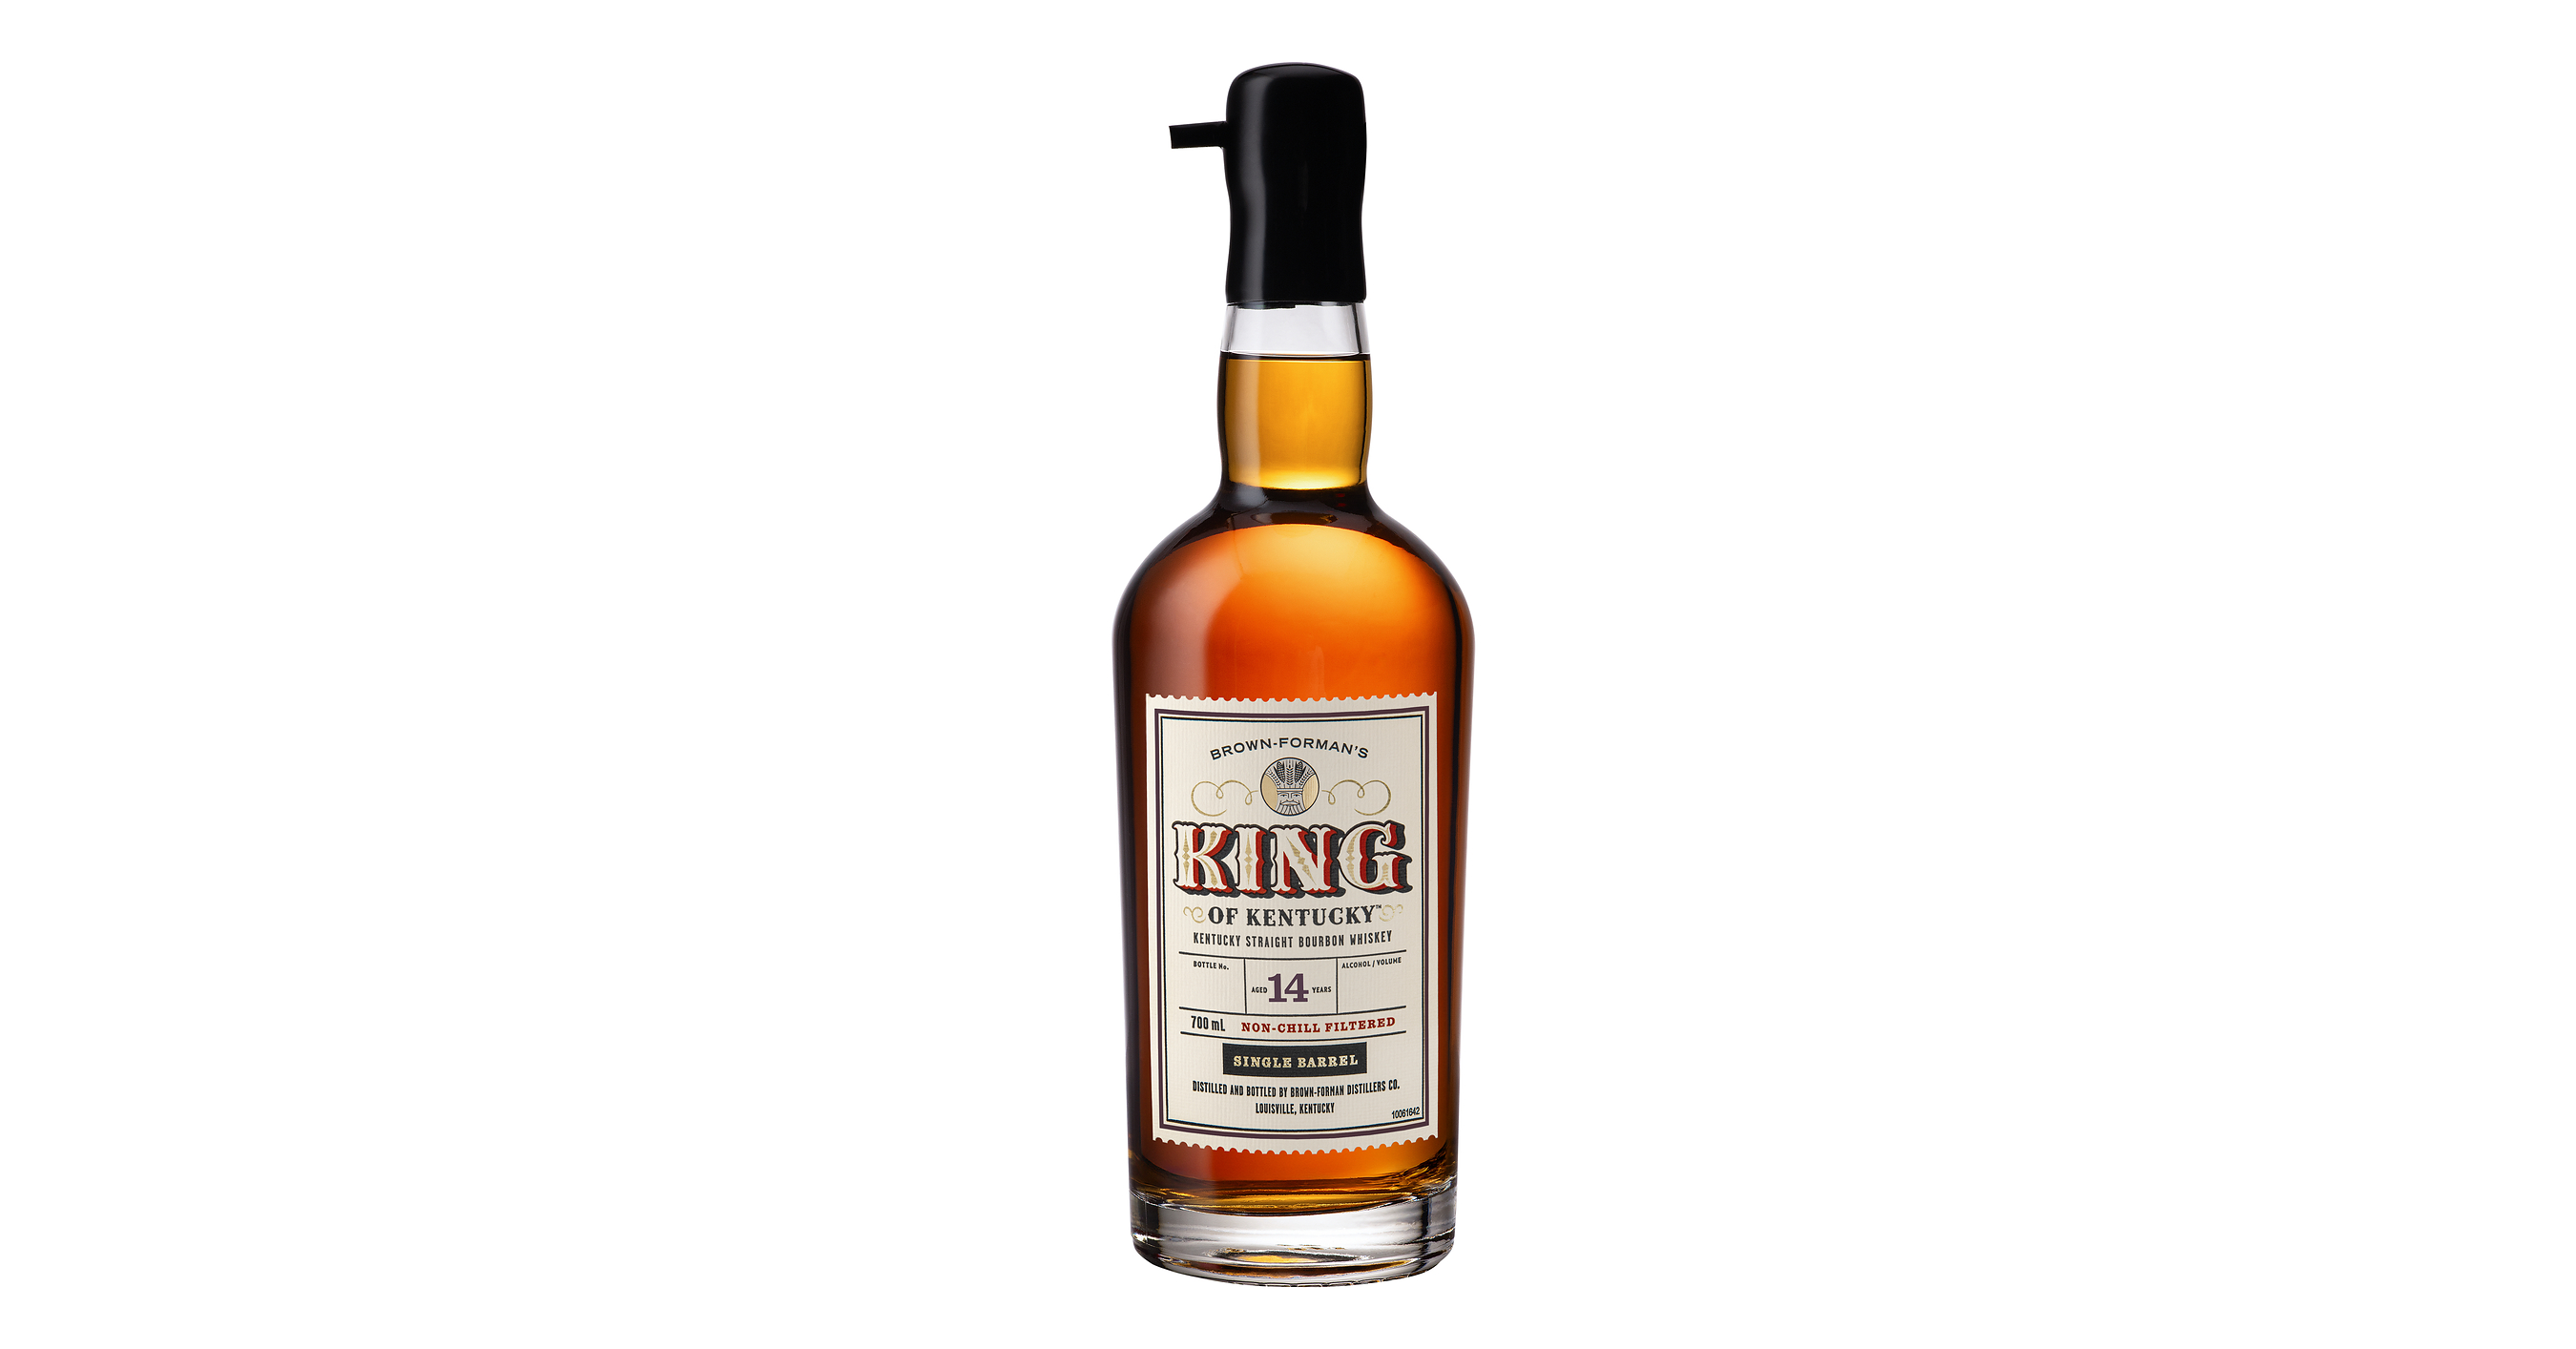
Brown-Forman's King of Kentucky will return in 2026 with a limited 14-year-old, high-proof single-barrel bourbon release drawn from 99 barrels. The hand-numbered bottles will be sold in select U.S. markets at a suggested retail price of $399, supporting the company's premium spirits portfolio but with limited expected financial impact due to the small production run.
Analysis
This is immaterial to Brown-Forman earnings: the release represents a micro-allocation of ultra-premium inventory, not a volume driver for BF.A. Its value is instead as a brand-equity signal—scarcity and high proof-point pricing can support the halo around Woodford Reserve and Old Forester, where distribution scale makes any premiumization measurable. The relevant operating question is whether management can translate collector demand into improved mix without relying on discounting in core American whiskey.
Near term, the announcement should not alter estimates or justify a directional position. Over the next 1-3 months, watch US depleted-volume trends, retailer inventory commentary, and gross-margin guidance: a sustained premium mix improvement would be more meaningful than sell-through of allocated releases. At a 6-18 month horizon, aged-stock availability is a potential constraint; stronger demand for aged expressions raises the opportunity cost of inventory held for future releases and can pressure working capital, while weakening whiskey demand would turn that aging inventory into a capital drag.
The contrarian read is that luxury-bottle visibility can obscure the broader category risk. Secondary-market enthusiasm does not establish broad consumer willingness to absorb higher shelf prices, particularly if household discretionary spending weakens. BF.A's rerating requires evidence that premium brand pricing and international growth offset normalization in US whiskey consumption, rather than isolated scarcity-led launches.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release; treat it as a qualitative premiumization datapoint rather than an earnings catalyst.
- Maintain BF.A as a watch-list long only if the next earnings report shows organic net-sales growth and gross-margin expansion alongside stable US distributor inventories; that combination would support a 6-12 month multiple recovery thesis.
- Use a relative-value framework rather than outright exposure: consider long BF.A versus short STZ only after confirming divergent US spirits versus beer demand trends in upcoming earnings, with position risk cut if BF.A lowers full-year organic-sales or margin guidance.
- Monitor US whiskey category scanner data and BF.A distributor inventory days over the next quarter. Evidence of rising inventories or increased promotional activity would falsify the premium-mix thesis and argues against adding exposure.
More News
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
- Markets slip on dollar pressure, but this IT stock is up 10% today