
DAMAC achieves handover of 50,000 homes, with 55,000+ in pipeline and USD 2.72 bn in H1 2026 construction awards
Source: PR Newswire
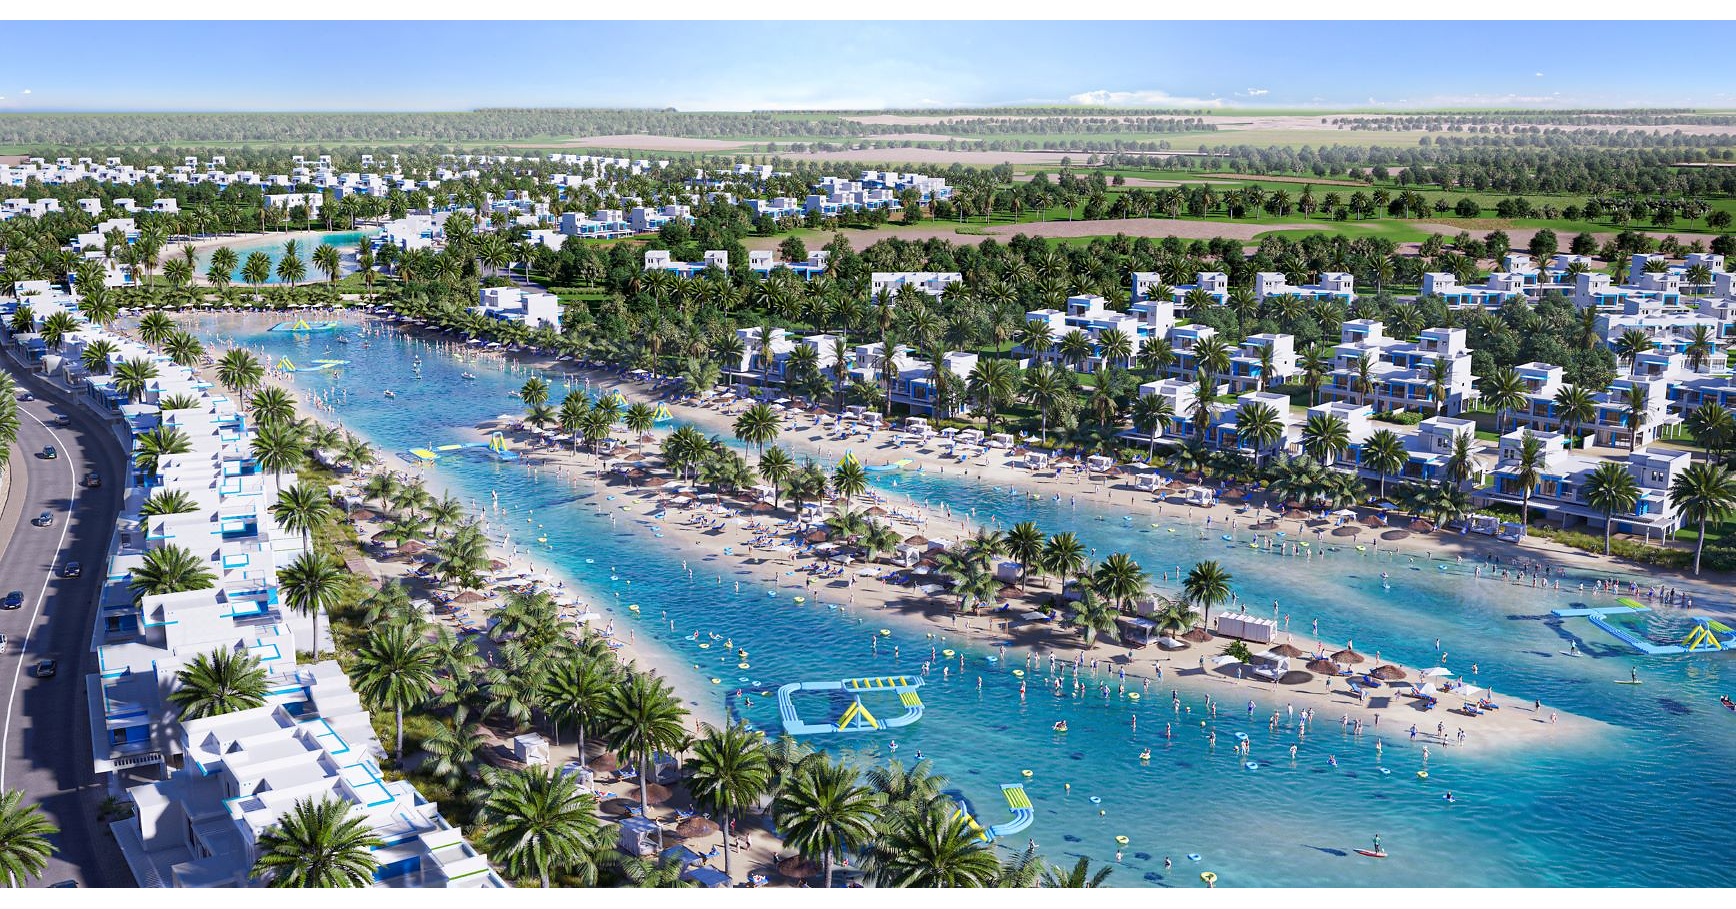
DAMAC said it has handed over 50,000+ homes, while awarding USD 2.72bn of construction contracts in H1 2026 and targeting 8,800+ residential unit deliveries in 2026. Handovers accelerated to nearly 25,000 new homes in H1 2026, up 36% y/y, with about 13,200+ units delivered in Q2 and ~32,000 additional units expected in 2H. The company attributes progress to stronger delivery/contractor management despite “geopolitical pressures” affecting global supply chains.
Analysis
This is more of a volume/velocity signal than a pure direction call. The main second-order effect is that a larger handover base in Dubai tends to lift brokerage, valuations, property management, and financing activity even if it also adds near-term supply pressure to rents. For CWK, the linkage is indirect and probably too small to justify a standalone earnings revision unless management discloses a meaningful Gulf contribution; the cleaner beneficiaries are local agents, valuation shops, and lenders with transaction-based fee income.
The key time horizon is 1-3 months: watch whether the new supply wave is absorbed without a vacancy spike or price cuts. If absorption holds, the market should reward execution-capable developers and service providers because completion converts paper pipeline into cash flow and repeat business. If absorption slips, the losers are landlords and developers trying to reset pricing higher; that would also narrow the multiple on any regional-exposed CRE names by raising fear of a late-cycle supply overhang.
Contrarian view: the consensus may be too focused on oversupply and missing that delivery execution is often bullish for the ecosystem because it unlocks closings, mortgages, fit-out spend, and ongoing community services. The real risk is not the headline handover count but whether buyers can take title smoothly and whether post-handover defects or financing stress slow resale liquidity. That would show up first in Dubai transaction volumes, mortgage originations, and rent growth; if those stay firm, the bearish supply thesis is likely overstated.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade in CWK on this release; treat it as a watchlist name only and wait for the next earnings call to see whether Middle East activity is translating into measurable fee revenue or backlog growth.
- Relative-value idea: long CWK / short JLL for 1-3 months only if upcoming Dubai transaction and leasing data confirm that completions are boosting cross-border advisory volumes while U.S. office leasing stays soft; stop the trade if CWK fails to outperform by ~5% into earnings.
- Set an alert on Dubai monthly rent and transaction prints over the next quarter: if rents fall and resale volumes stall, that would validate the oversupply risk and argue against owning any regional CRE-services beta.
- If you want a cleaner macro expression, avoid shorting broad real-estate services here unless local absorption weakens; the better trade is waiting for evidence of vacancy pressure before pressing a bearish view.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
- China’s Q3 GDP growth accelerates to 4.5%, beating forecast