
Hisense dévoile la nouvelle famille de projecteurs C3 pour le divertissement à domicile immersif
Source: PR Newswire
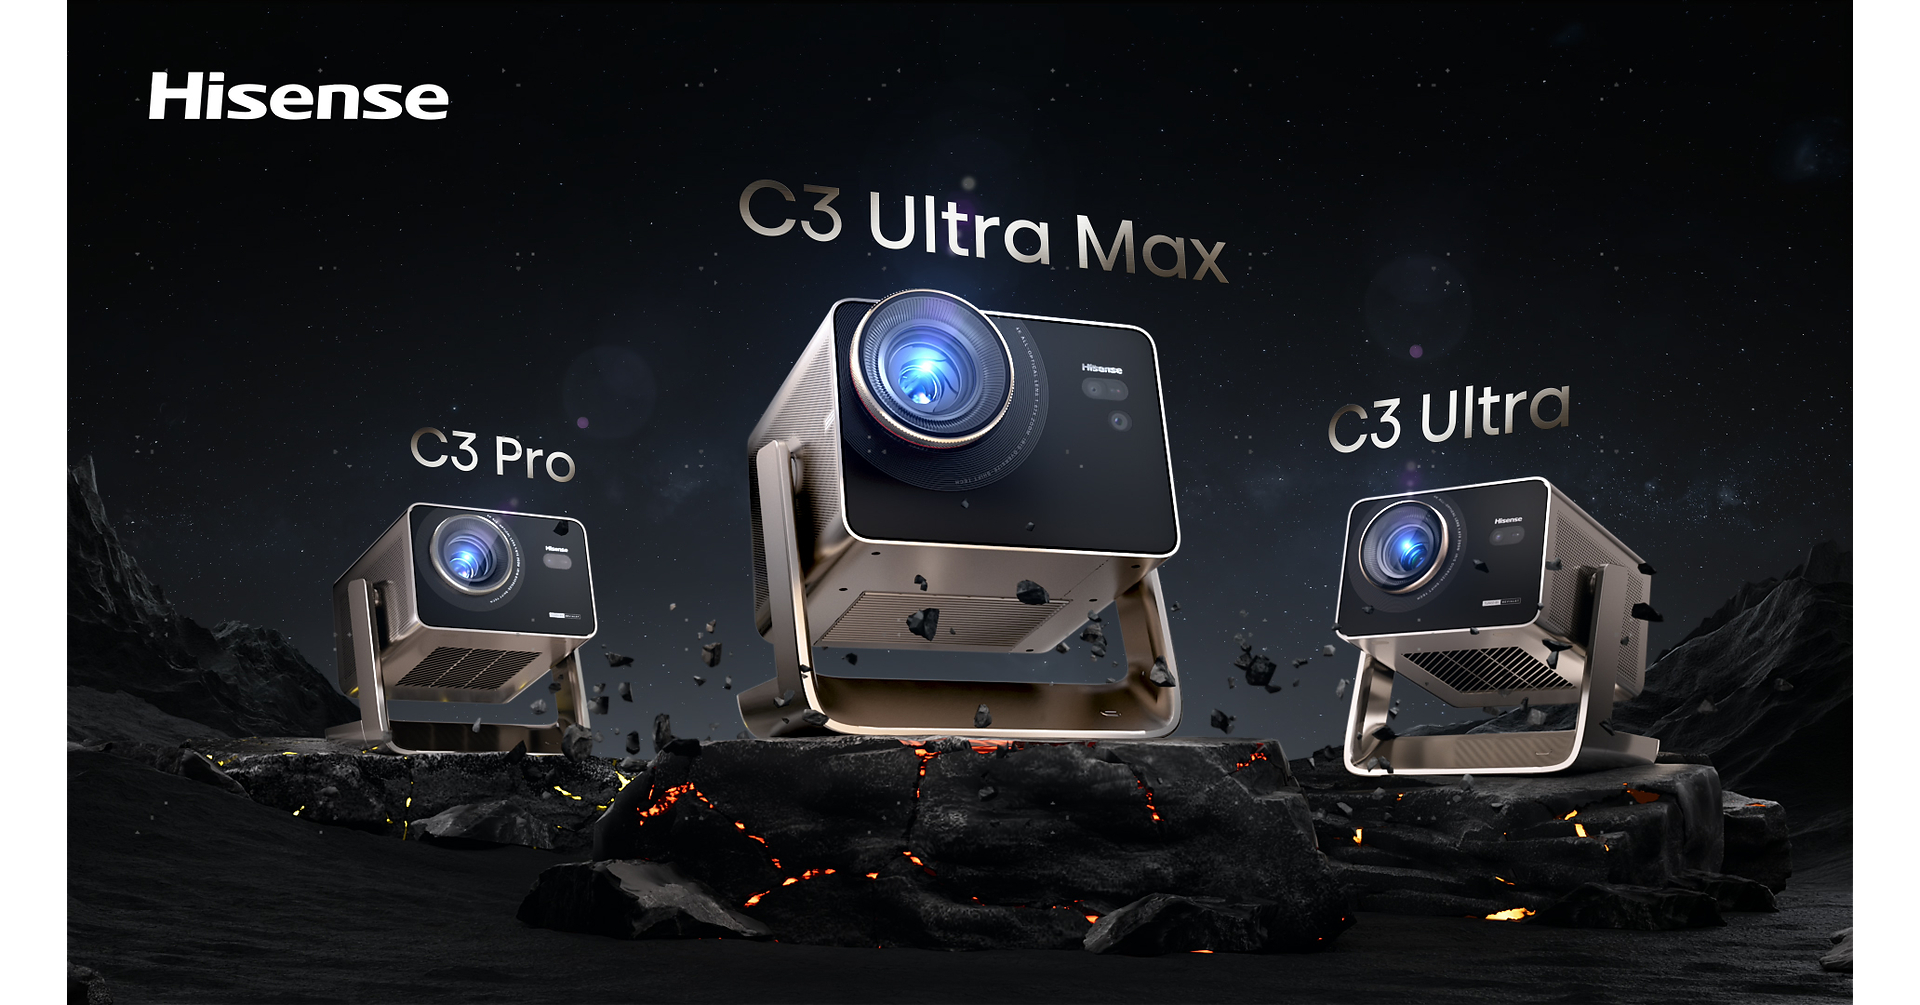
Hisense unveiled its C3 projector family at IFA 2026, with the C3 Ultra and Ultra Max scheduled for global launch in September and the C3 Pro to follow. The lineup offers up to 300-inch projection, 3,000-5,000 ANSI lumens, 5,000:1 contrast ratios and, for the C3 Ultra Max, 1 ms latency targeting gaming, sports and home cinema use. Hisense also cited SGS lifecycle and product-carbon-footprint assessments for the C3, supporting product-level environmental transparency.
Analysis
This is not a material earnings catalyst for SGSN: the company’s involvement appears limited to product-footprint verification, a low-ticket, non-recurring assurance engagement rather than evidence of scalable ESG-services revenue. The more relevant signal is that projector vendors are moving toward premium, integrated home-entertainment systems, raising the competitive bar for stand-alone display and audio suppliers. Hisense is privately held, limiting direct equity expression; the listed read-through is modestly negative for Epson (6724 JP) and Sony (6758 JP), whose premium projection franchises face further price/performance pressure from Chinese OEMs.
Near term, the product cycle is more likely a retail-share event than an industry demand expansion: large-screen projectors compete with 98–115 inch MiniLED/LCD televisions, where Hisense already has distribution leverage. A major global sports-marketing cycle could improve sell-through over the following 6–12 months, but only if retail pricing remains rational; aggressive bundling would likely transfer value to consumers and compress category margins. The claimed performance specifications and environmental credentials should not be capitalized into estimates without independent reviews, regional pricing, channel inventory data, and evidence that launch timing is firm.
The contrarian view is that higher-specification projector launches may cannibalize Hisense’s own ultra-large TV opportunity more than they disrupt incumbents. For component suppliers, the key question is whether the platform uses a meaningful incremental bill of materials for DLP/laser optics versus internally sourced display technologies; that disclosure is absent. No broad consumer-electronics trade is warranted on this announcement alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No action in SGSN: maintain neutral exposure. Reassess only if SGS identifies a multi-client product-carbon-verification program or discloses ESG-assurance bookings large enough to affect 2027 organic-growth expectations.
- Monitor Epson (6724 JP) and Sony (6758 JP) for a 1–3 month relative-short setup only if third-party retail data show projector price deflation or share loss in North America/Europe; use a long Consumer Discretionary ETF hedge rather than an outright sector short.
- Watch Texas Instruments (TXN) as a component read-through rather than a recommendation: initiate research on DLP exposure if teardown data confirm a DLP architecture and launch volumes exceed management/channel expectations. Falsifier: laser/LCoS architecture or low retail availability.
- For Hisense’s publicly traded suppliers and competitors, wait for post-launch pricing and inventory data. A sustained promotional discount greater than roughly 15–20% versus announced MSRP would signal margin-destructive competition, not incremental premium-category demand.
More News
- Two camps have emerged in the debate over AI safety and regulation
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
- Push for AI regulation mounts as talk of AI’s ‘existential’ risks go mainstream. But Trump resists calls for a slowdown
- Federal Reserve decision, retail sales, and oil inventories due Wednesday
- Urgent calls from OpenAI, Anthropic for an AI slowdown fall on deaf ears with Trump, Xi ahead of next week’s meeting
- Why Dave & Buster's Stock Tumbled Today