
XCMG dévoile la première grue à anneau au monde d'une capacité de 14 000 tonnes pour redéfinir le levage de charges ultralourdes
Source: PR Newswire
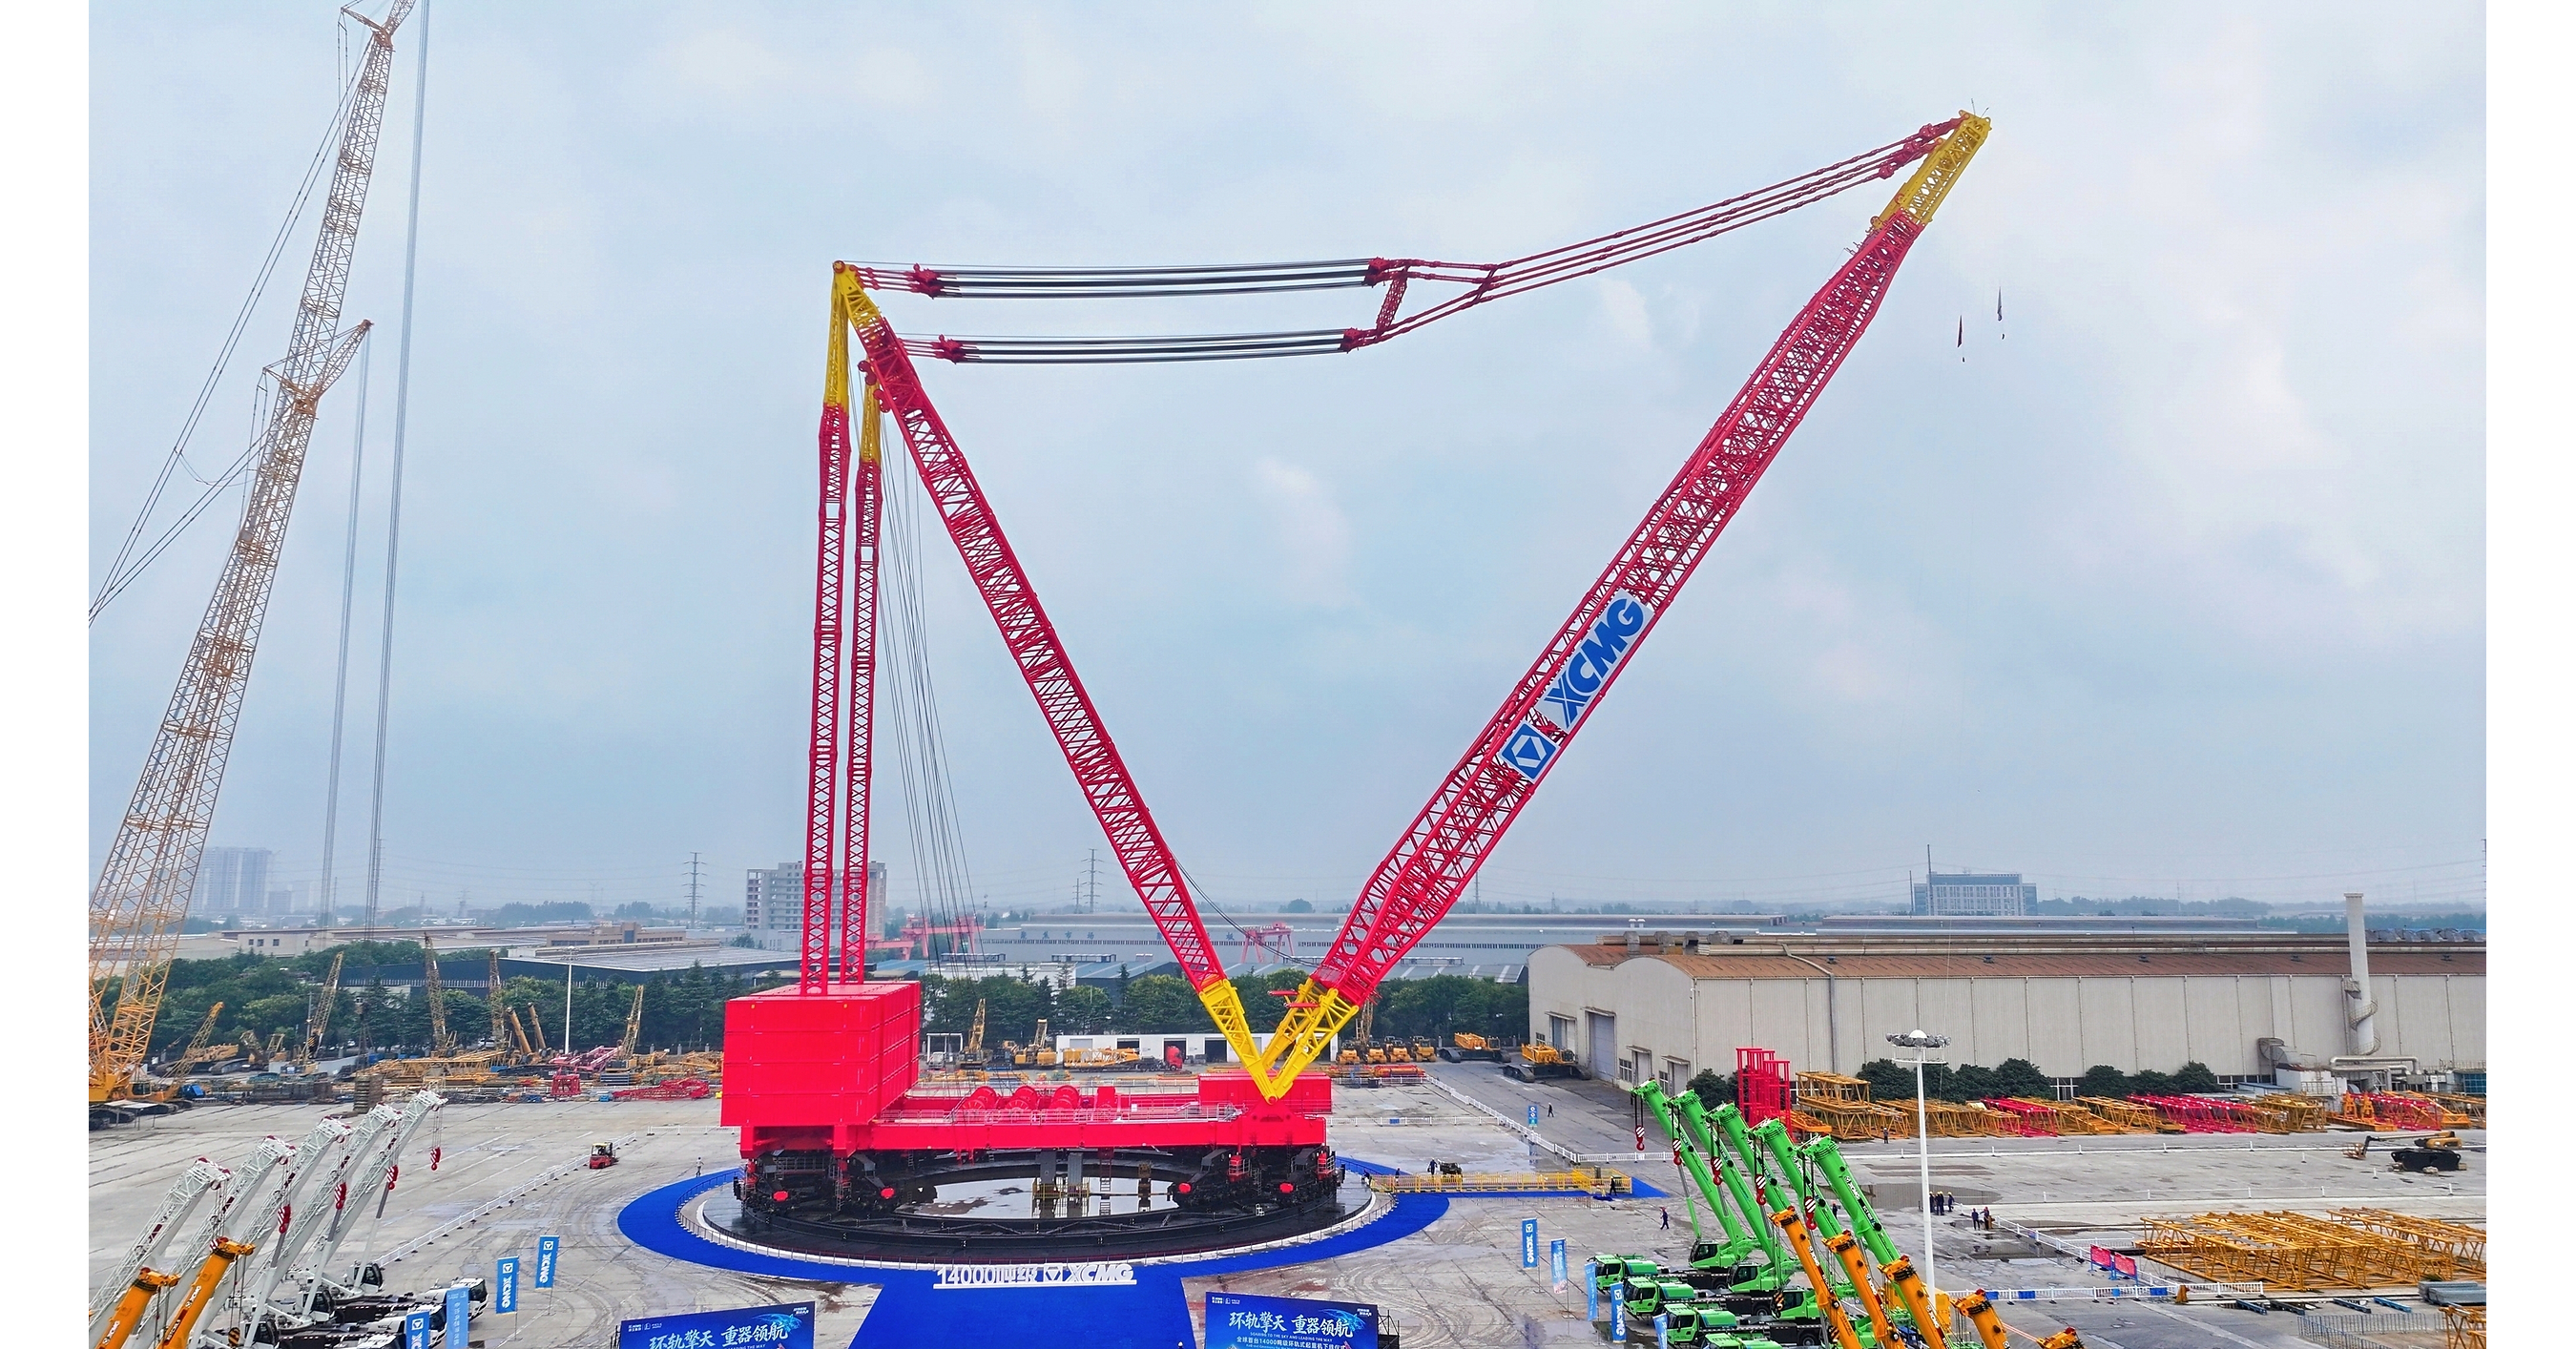
XCMG annonce la sortie de la première grue à anneau mondiale de 14 000 tonnes, avec un moment de levage maximal de 700 000 tonnes-mètres, dont l’assemblage final de l’unité principale est achevé et capable de levage autonome. La grue vise plus de 30% d’économies d’énergie, +20% de rendement de fonctionnement et une réduction des coûts carburant/émissions, via un entraînement électrique direct. Le partenariat avec Sinopec Heavy Lifting & Transportation positionne la grue pour des usages nucléaires (manutention de modules pour deux îlots) et éoliens offshore, ce qui soutient un signal positif pour l’innovation produit de XCMG.
Analysis
This is more a capability advertisement than a near-term earnings event. The investable read-through is that XCMG is trying to move up the value chain from commoditized machinery into a small set of mission-critical, high-specification lifts where qualification, reliability, and installed base matter more than sticker price. If that positioning holds, the economic benefit is less from unit volume and more from mix expansion, service content, and the ability to win politically sensitive projects where domestic sourcing is preferred.
The second-order beneficiaries are not just crane buyers but project owners and EPCs: modular nuclear, offshore wind, and large petrochemical complexes gain from shorter critical-path installation windows and lower assembly risk. That can improve project IRRs by reducing delay penalties and overtime costs, which matters more than the crane itself for contractors. The likely losers are niche Western heavy-lift suppliers and specialty rental providers that compete on ultra-heavy segments, but the practical impact is limited because this market is too small to move broad industrial indices on its own.
Time horizon matters. Over the next days, any share reaction should fade if there is no order pipeline or certification update. Over 1-3 months, watch for export wins, nuclear framework contracts, or offshore wind installation tenders that validate the platform; over 6-18 months, the real question is whether this becomes a repeatable commercial product or remains a flagship prototype. The main falsifier is simple: no incremental awards, no margin uplift, and no evidence the direct-drive efficiency claims translate into higher fleet utilization or pricing power.
The contrarian view is that the market may overrate the strategic significance of a technical first. In ultra-heavy lifting, the bottleneck is usually not peak capacity but project scheduling, field engineering, insurance, and permitting, so a world-record machine does not automatically create a durable moat. If investors start capitalizing this as a broad industrial upgrade, I would fade the enthusiasm unless order conversion is visible in the next two reporting cycles.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Key Decisions for Investors
- Long 000425.SZ (XCMG Machinery) only on pullbacks, 3-6 month horizon; thesis is mix/brand uplift into nuclear and offshore wind, but size modestly because revenue translation is likely delayed and event-driven.
- Pair trade: long 000425.SZ / short 000157.SZ (Zoomlion) for 1-3 months if the market prices this as a genuine technology leadership gap; stop if peer order intake or margin commentary narrows the perceived lead.
- Watchlist alert on 1816.HK (CGN Power) and 601611.SH/601669.SH domestic nuclear EPC proxies: if this crane is followed by module-handling orders or faster nuclear build schedules, the project-execution value accrues to the whole chain more than to the equipment maker.
- Avoid chasing Western crane OEMs like TEX or MTW on this headline alone; the competitive threat is mostly symbolic unless XCMG starts winning export tenders outside China, which is the key missing data point.
- Set a catalyst monitor for the next 1-2 quarterly updates from XCMG: if there is no disclosed order backlog uplift, margin expansion, or named project win, treat this as a sentiment event rather than a fundamental re-rating catalyst.
More News
- The IEA wants to empty its oil reserves faster. A federal watchdog says the US isn’t ready for what comes next
- Deadly Houthi Attacks on Saudi Arabia; EU Caps Chinese Hybrid Car Imports
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Saudi Arabia says 1 dead, 11 injured in latest attack on Riyadh airport
- Why is LG Innotek stock plunging today?
- RBI Tightens Rupee Defense as Pricey Crude, Foreign Outflows Bite: USD/INR