
Confitex Technology remporte le prix INDEX et le prix de l'innovation Hygienix pour ses produits d'hygiène absorbants en non-tissé lavables, une première mondiale
Source: PR Newswire
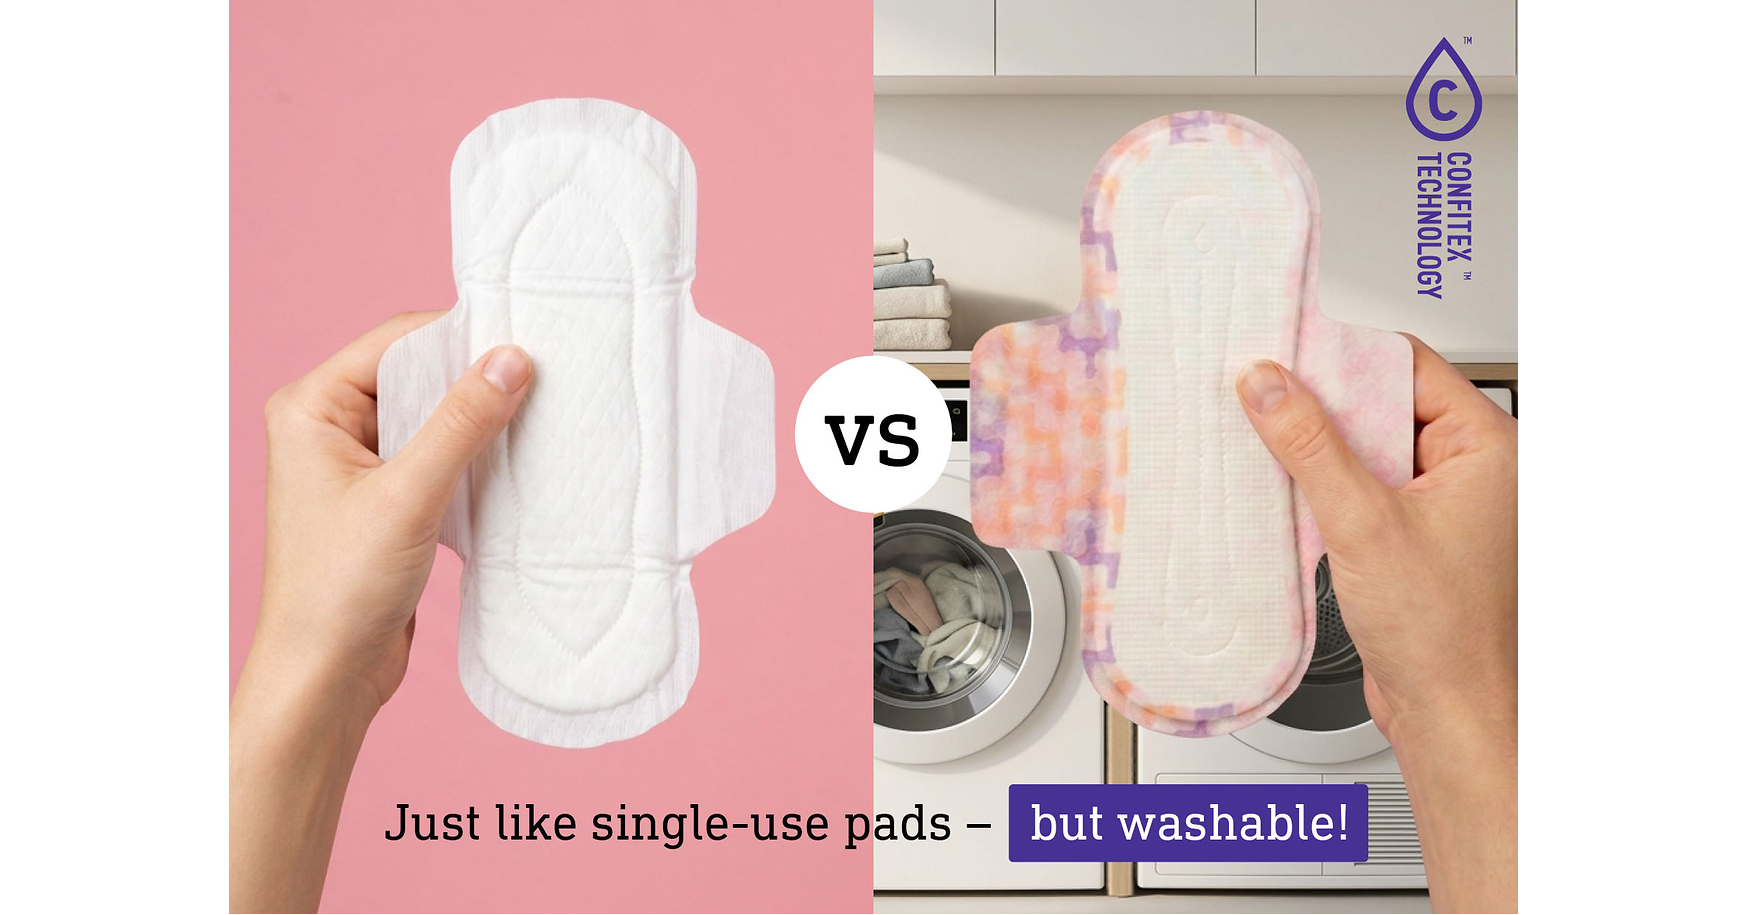
Confitex Technology became the first company to win both the INDEX Award and the Hygienix Innovation Award for washable nonwoven absorbent-hygiene products, validating a reusable alternative to disposable pads and incontinence products. Its products are 90% bio-based, contain no petroleum-derived superabsorbent polymers, and independently tested at absorption levels equal to or above comparable disposable products. The global absorbent-hygiene-products market is valued at approximately $123.5 billion, while reusables account for less than 15% but are growing at a 6.89% CAGR, supported by EU single-use-plastic pressure and French subsidies for reusable menstrual underwear.
Analysis
This is not an ITRK earnings catalyst: Intertek’s role is laboratory validation, and any incremental testing revenue from one emerging product format is immaterial relative to group sales. The more investable signal is that reusable absorbent products are moving from niche textile construction toward scalable nonwoven manufacturing, potentially lowering unit costs and enabling private-label penetration. If retail adoption broadens, category value may shift from branded disposable-product marketing toward material science, automated conversion capacity and retailer-owned brands.
The principal long-term losers are disposable AHP incumbents with high exposure to volume-led consumables economics—especially KMB, PG and Unicharm—if reusable products achieve repeat purchase through adjacent categories rather than merely substitute premium menstrual underwear. SAP suppliers such as Nippon Shokubai and Sumitomo Seika face a modest structural demand risk, but the relevant threshold is sustained private-label shelf allocation, not award recognition. Conversely, suppliers able to produce durable, washable nonwovens and natural-fiber inputs could gain mix and pricing power; this is a 6-18 month commercialization watch, not a near-term earnings revision.
Consensus is likely to overinterpret sustainability credentials while underestimating consumer friction: laundering convenience, hygiene perception, upfront price and retailer returns are the adoption constraints. European subsidy programs can accelerate trial but do not prove repeat usage or gross-margin viability; a subsidy-driven channel could also create abrupt demand reversals. The thesis is falsified if major retailers do not dedicate permanent shelf space by the next buying cycle, if private-label reorder rates lag disposable-category benchmarks, or if regulatory standards impose costly performance and wash-durability requirements.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No directional ITRK trade: retain only a monitoring alert for management commentary on consumer-product testing volume or a material contract win; the disclosed connection is reputational rather than financially meaningful.
- Establish a 6-12 month research watch on KMB and PG European feminine-care/incontinence category growth and gross margin. Consider a tactical underweight only if reusable private-label shelf resets coincide with downward volume guidance; absent that evidence, cannibalization risk is too small for a standalone short.
- Monitor Nippon Shokubai and Sumitomo Seika for SAP-volume guidance and European AHP customer commentary over the next two reporting cycles. A relative short versus a diversified chemicals long becomes actionable only if SAP shipment growth turns negative while raw-material costs remain benign, isolating mix loss from cyclical input effects.
- Track European retail procurement announcements and French reimbursement/subsidy implementation over 1-3 months. Treat confirmed multi-country private-label launches as the catalyst for reassessing disposable AHP revenue assumptions; awards and company claims alone do not justify a position.
More News
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- US Senate crypto bill collapses in blow to industry
- BlackRock’s Fink, Blackstone’s Gray Back Carney’s Canada Investment Push
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
- Chinese investors rush into US stocks as Beijing opens wider path overseas
- Factbox-How AI leaders and world governments react to ’AI doom’ fears
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI for Sell-Side Models, Estimates, and Internal Data
- How to Write an Investment Memo with AI: A Decision-Record Template