
PETL Nears $1 Million in Monthly Sales After a Year of 30% Monthly Growth
Source: PRWeb
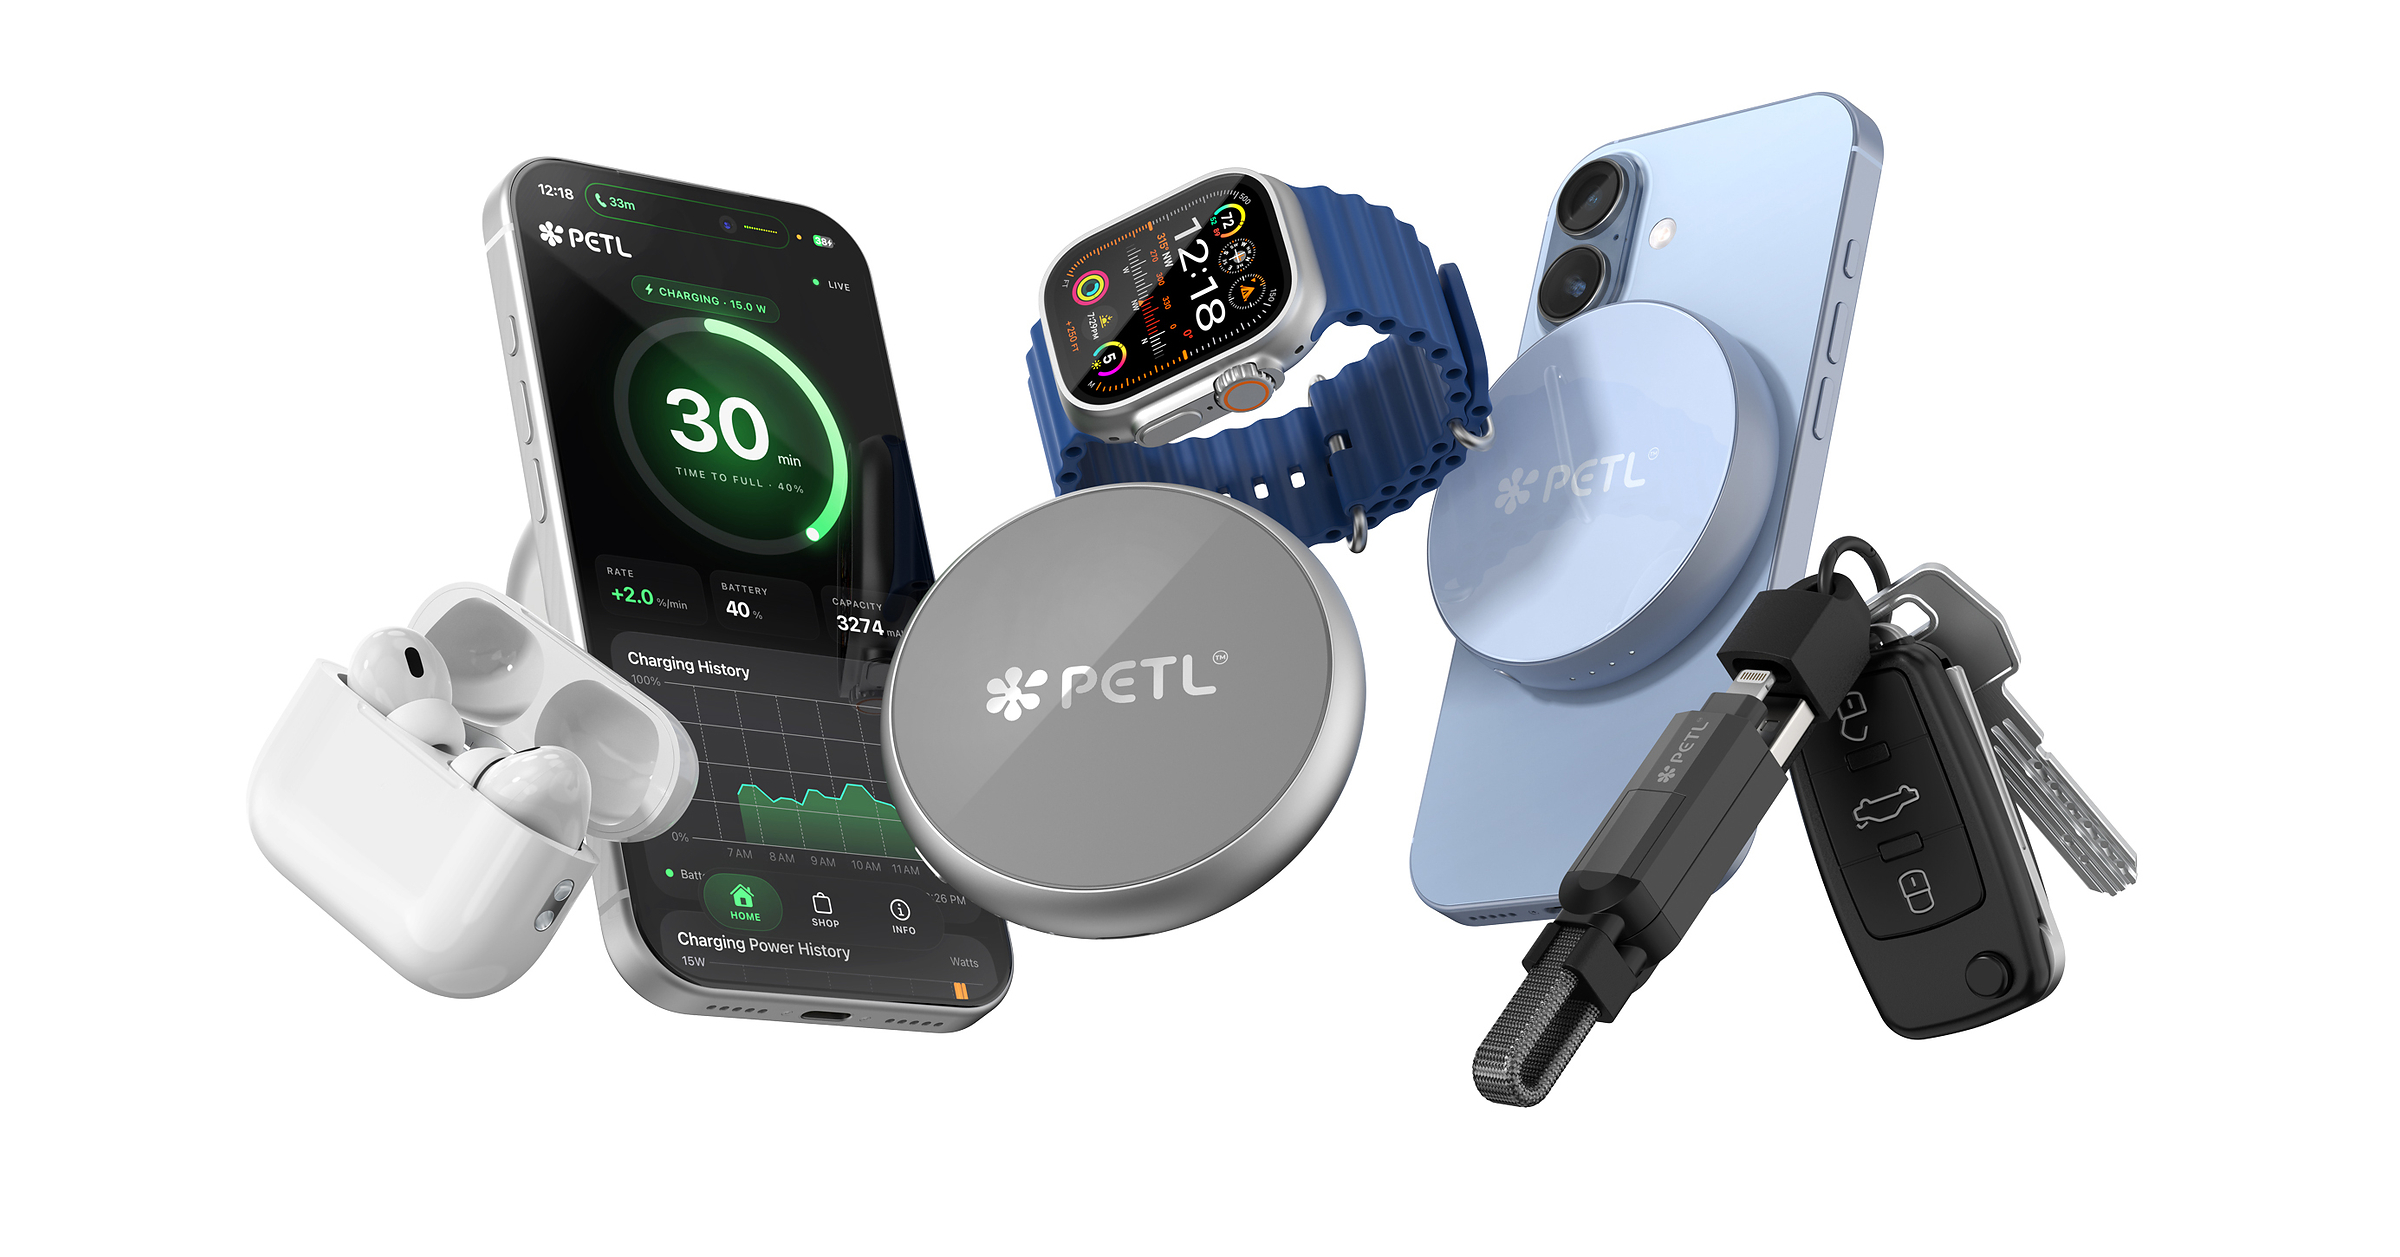
PETL reported August sales of $946,619, closing its first 12 months near $1M in profitable monthly revenue while sustaining ~30% month-over-month sales growth. The company says its customer ecosystem surpassed 80,000 users, targeting >100,000 by end-2026, alongside an expanding product pipeline of new charging products through 2026–2027.
Analysis
This is more interesting as a proof-of-concept for premiumization in a commoditized accessory category than as a standalone sales milestone. If a design-led DTC brand can hold pricing and still scale, the real asset is not the first product but the owned customer graph: a low-cost channel to launch successive SKUs with higher lifetime value. That said, at this scale the burden of proof is on repeat purchase and attach rates, not top-line momentum.
The key risk is that portable power is structurally easy to copy and expensive to defend. Larger accessory brands, marketplace sellers, and retailer private labels can imitate form factor quickly, so margin durability will likely hinge on paid-media efficiency and inventory discipline rather than patent protection. In the next 1-3 months, watch gross margin, return rates, and ad CAC; over 6-18 months, watch whether the product line expands into a true platform or stalls as a one-SKU novelty.
The contrarian view is that the market may be overvaluing 'users' as if it implied recurring demand. Most consumers buy a charger once and replace only when the form factor changes or the old one fails, so cohort monetization could flatten faster than management expects. The bull case remains intact only if new launches materially increase wallet share per user; falsifiers would be a slowdown below high-teens month-over-month growth, rising discounting, or evidence that the customer base is not reordering across launches.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.10
Key Decisions for Investors
- No immediate public-equity trade: the signal is too small and too company-specific to justify a listed long/short; keep this as a watch item rather than a recommendation.
- Add a monitoring trigger for DTC consumer hardware: if subsequent launches show >20% monthly growth with stable gross margin and sub-35% CAC as a % of revenue, consider a broader long on consumer discretionary quality names; otherwise stay flat.
- Watch for competitive response from retailer private labels and marketplace sellers over the next 1-2 quarters; if pricing compresses, the thesis shifts from brand premium to commodity churn, which is a sell signal for any future exposure.
- If a public accessory peer or retailer reports rising attachment sales in mobile accessories, use that as a read-through for holiday demand; absent that confirmation, do not extrapolate this niche data point into sector beta.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data
- Best AI Stock Research Tools for Professional Investors