
Farizon SV Model Year 2027 makes its French debut at Rungis, tested for real-world delivery
Source: PR Newswire
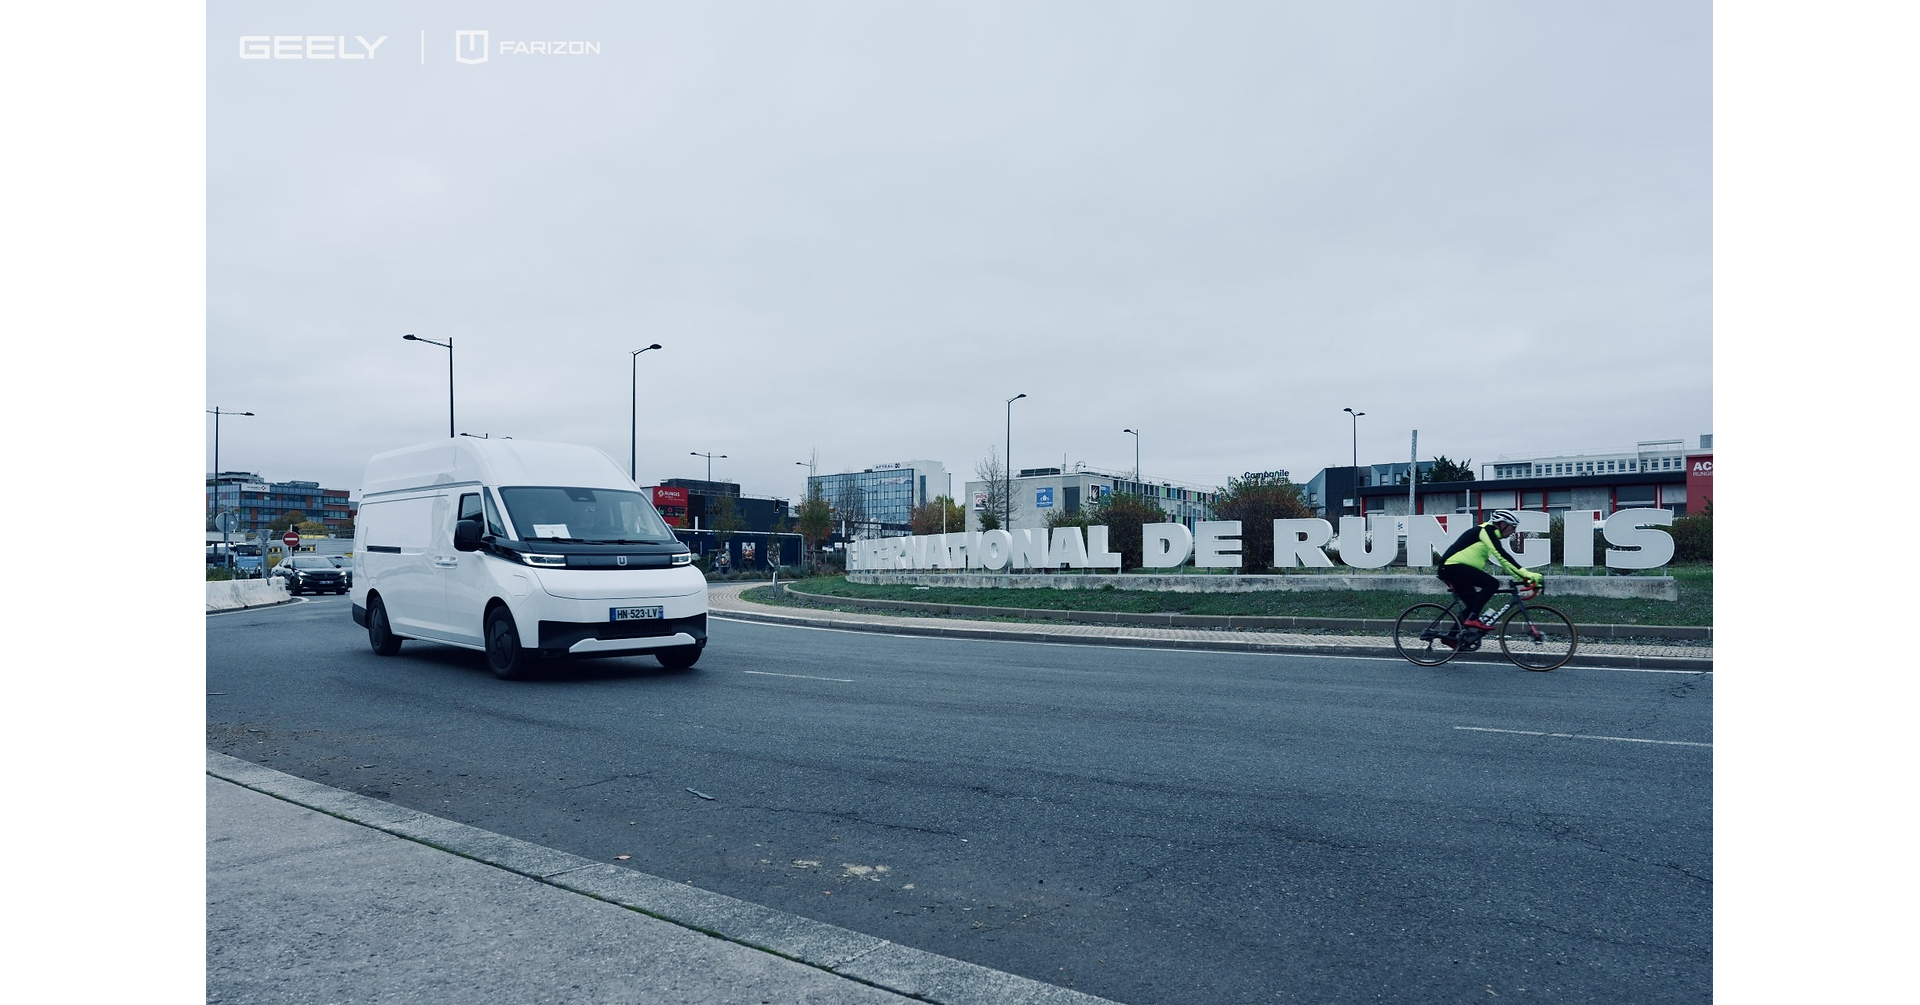
Geely Farizon introduced the Model Year 2027 Farizon SV electric light commercial vehicle in France, quoting 13 m³ of cargo volume and up to 384 km of WLTP combined range. Its new CATL battery supports 2C DC charging from 20% to 80% in 18 minutes, and a new all-wheel-drive variant targets improved traction. Local Rungis operators tested the vehicle on simulated delivery rounds; the lineup is also set to expand with Combi and Minibus variants.
Analysis
The investable question is whether faster mid-shift charging and a purpose-built cargo layout can lower fleet downtime enough to overcome the usual electric-van barriers: acquisition cost, charging access, payload trade-offs and service coverage. If independently validated across working fleets, that could strengthen Farizon’s bids against Renault, Stellantis, Ford and Mercedes in high-utilization urban routes, while creating demand for local upfitters and depot-charging providers. The Rungis demonstrations and operator quote are promotional evidence, not proof of fleet-level economics or repeat orders.
Near term, the announcement is unlikely to change earnings meaningfully without pricing, order volumes and delivery capacity. Over 1–3 months, watch for fleet orders, independent route tests, charging performance under load and warranty terms; the 18-minute claim matters only if charging curves, charger availability and battery durability support routine use. Over 6–18 months, Combi and Minibus variants could widen the addressable market, but also increase homologation, conversion and service complexity. AWD may improve suitability in some routes while bringing potential cost, weight and range penalties that need verification.
Contrarian angle: product specifications may attract attention, but fleet procurement is a total-cost-of-ownership decision. A weak residual-value outlook or thin European service network can outweigh productivity gains. No direct equity trade is justified from this launch alone; the thesis is falsified by poor independent uptime, limited fleet orders, materially weaker real-world range or pricing that fails to compete with established vans.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- Treat the launch as a watch item, not an earnings catalyst; seek confirmed fleet orders, delivery timing and pricing before changing exposure to Geely or European commercial-vehicle names.
- Track independent tests against Renault, Stellantis, Ford and Mercedes vans for loaded range, charging curve, payload, uptime and service coverage—not headline specifications alone.
- Monitor whether depot operators can reliably provide the required high-power charging. If charging access is constrained, the claimed productivity advantage may not translate into lower fleet costs.
- Reassess only if fleet economics are demonstrated through repeat orders and credible total-cost-of-ownership data; adverse evidence would include weak real-world range, poor residual values, or AWD-related payload and efficiency compromises.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- SK Hynix says the memory-chip shortage will last until 2030—and more than half its production is booked for the next two years
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off
- Microsoft’s strong quarter backs up its stock rebound. Here's our new price target
- Google struggling to make AI Mode searches pay
- As Waymo expands overseas, it remains a niche cash-burning business