
Hyundai Motor Company Charts Profit-Driven Growth Roadmap at 2026 CEO Investor Day
Source: PR Newswire
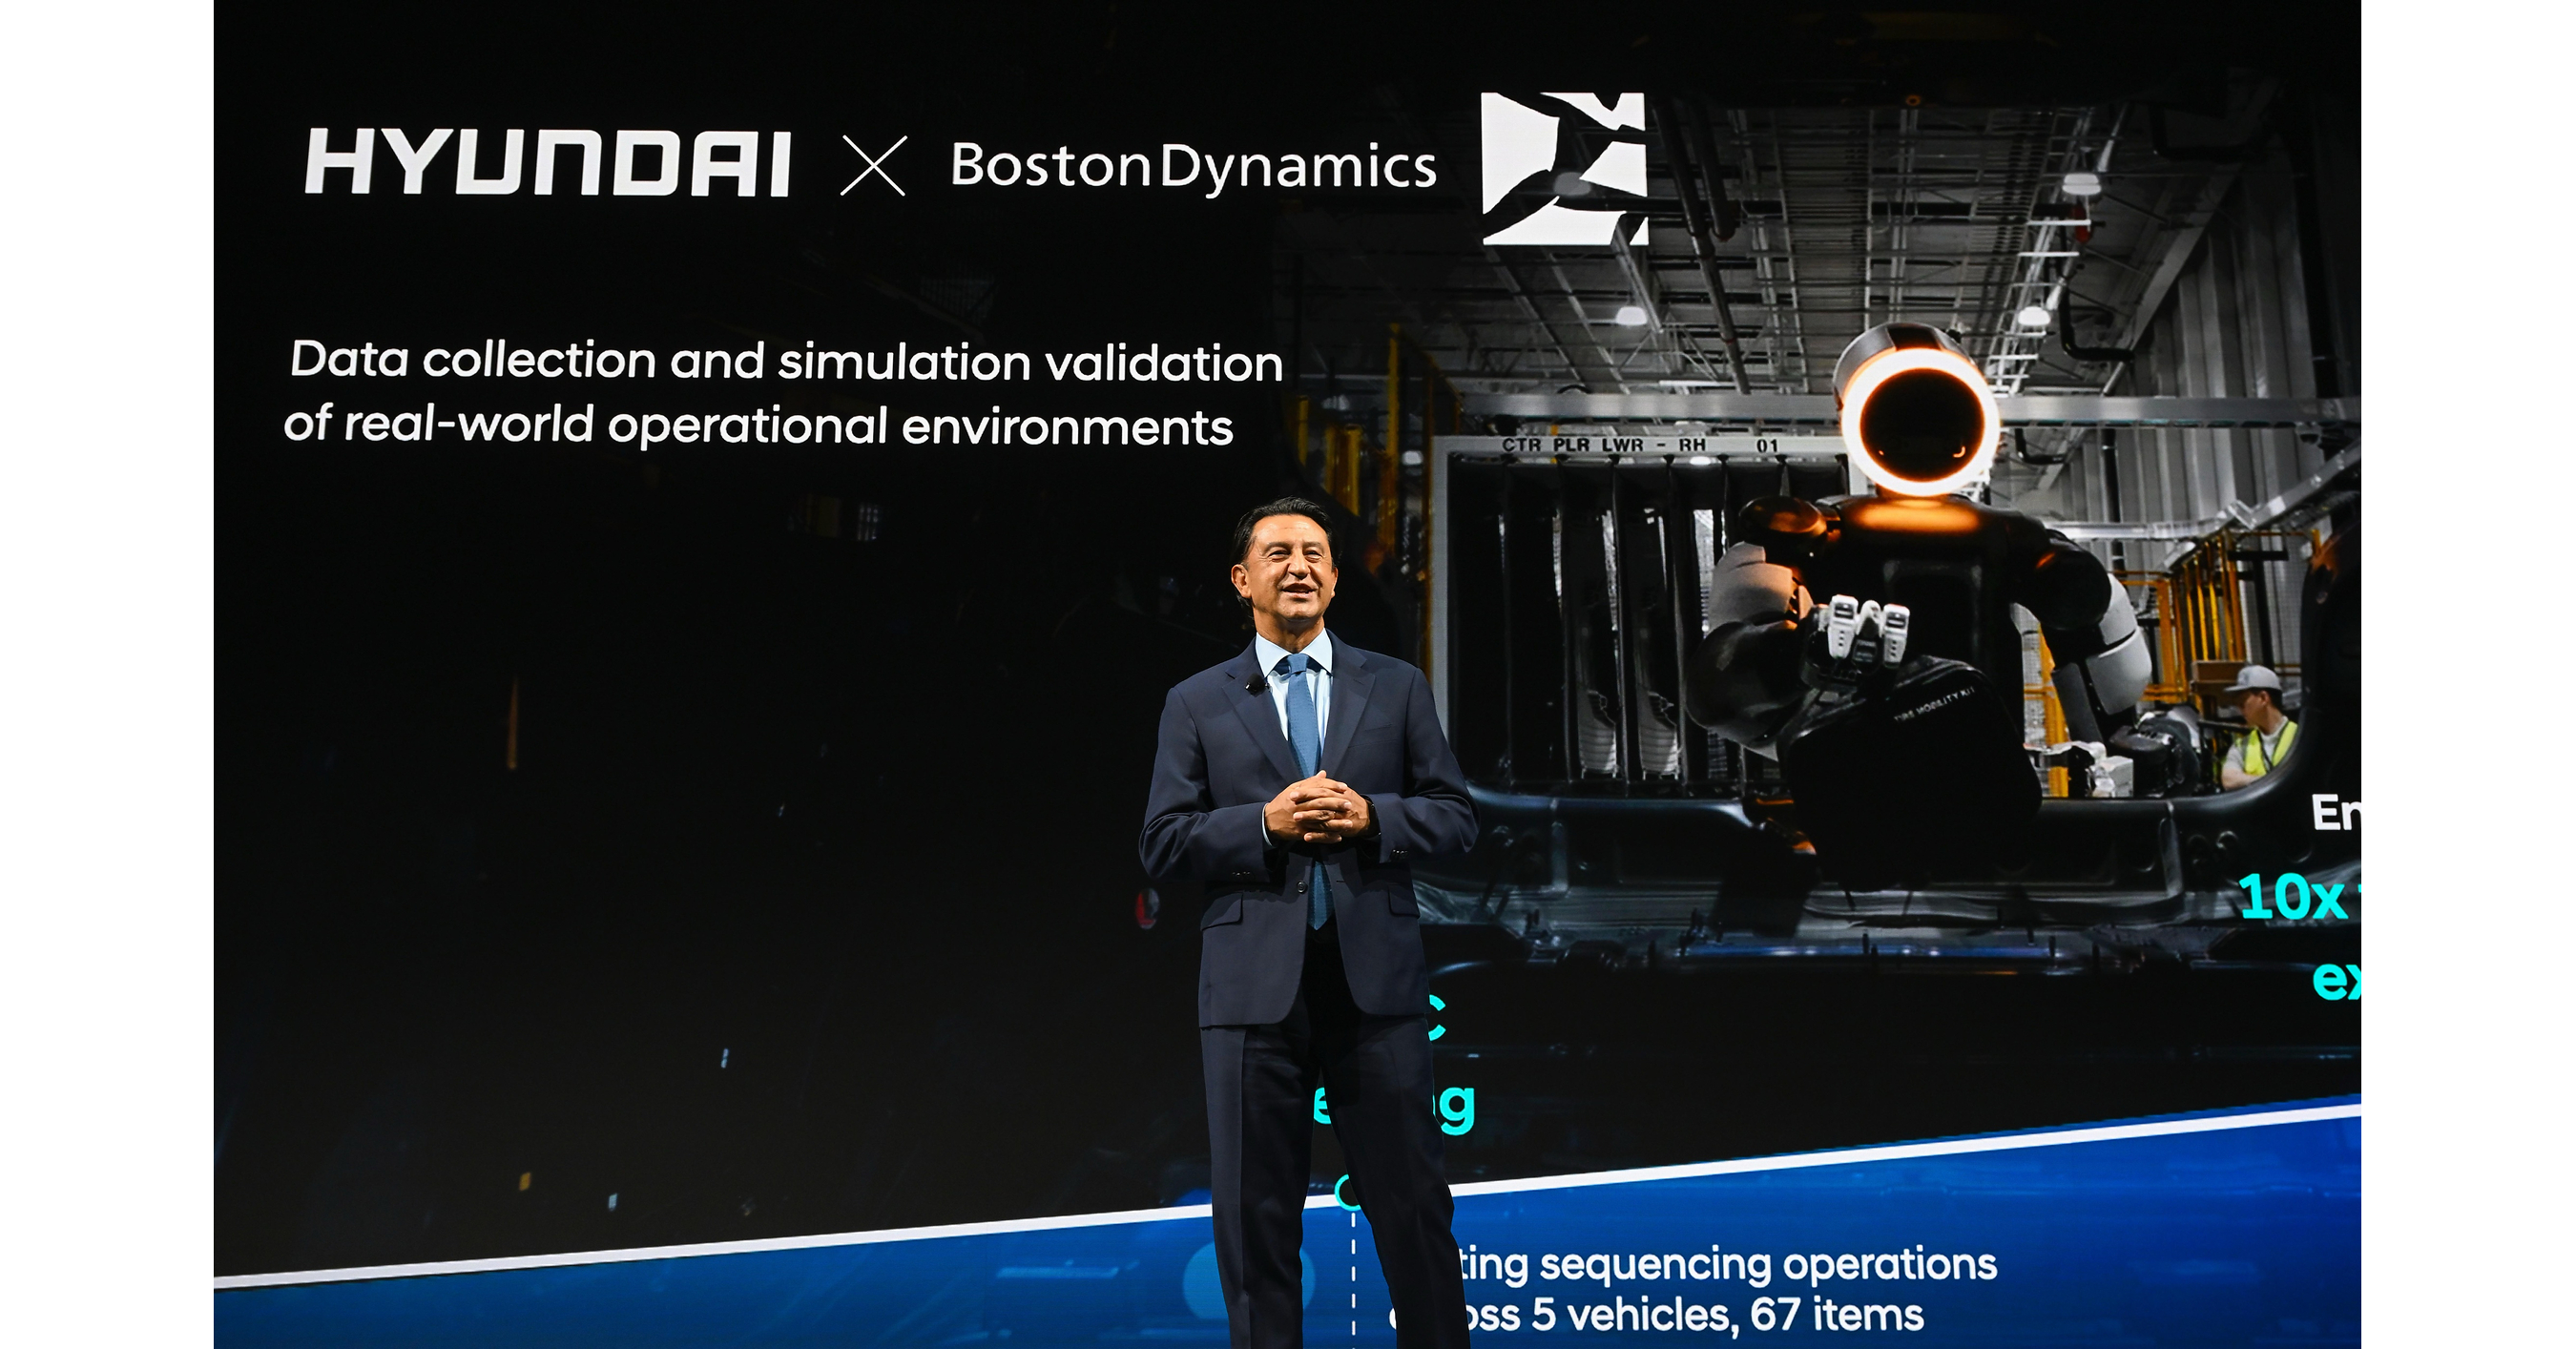
Hyundai set a profit-driven 2026 CEO Investor Day roadmap, raising its 2030 operating profit margin target to >9% from the prior 8–9%, supported by a 3 percentage point reduction in the cost of sales ratio. The plan targets 60% electrified mix by 2030 (from 23% in 2025), with EREV models launching in 1H 2027 targeting 600+ miles and additional U.S. capacity for the Santa Fe EREV plus end-part localization above 80%. First-half 2026 results showed 95.2T won revenue and a 5.6% operating margin, reinforcing the profitability track as Hyundai scales robotics/autonomy and expands global product launches.
Analysis
Hyundai is signaling a transition from “EV optionality” to a margin architecture story: more U.S. localization, more mix control, and less exposure to shipping/FX/tariff leakage. The second-order beneficiary is Hyundai’s own North American competitiveness versus import-heavy peers; the biggest loser is any OEM still relying on Asia-sourced volume growth to defend market share in the U.S. and Europe. If the operating margin target is credible, the multiple should migrate toward higher-quality industrial peers rather than remain trapped in a cyclical auto discount.
The more interesting competitive read is that Hyundai is hedging the EV transition rather than betting everything on battery-only adoption. That makes it a tougher rival for TSLA, RIVN, and Lucid in mainstream family vehicles, because range anxiety is being addressed without forcing a full charging-infrastructure commitment. It also modestly benefits the U.S. supply chain—tooling, assembly, logistics, and selected content suppliers—but the AI/autonomy angle is mostly long-dated option value; investors should not capitalise a 2028-2029 roadmap as near-term earnings.
Key risk is execution, not strategy: the near-term tell will be whether mix and gross margin actually improve as localization ramps, or whether capex and launch costs swamp the benefit for 2-4 quarters. The contrarian view is that the market may be underestimating how much the product cadence can re-rate Hyundai, but overestimating the incremental contribution from robotics, robotaxis, and NVIDIA-linked software. Falsifier: if next two earnings updates fail to show margin expansion or if North America ramp causes utilization drag, the thesis should be cut quickly.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.50
Ticker Sentiment
Key Decisions for Investors
- Long HMC (or HYMLF if liquidity is acceptable) vs short F, 1-3 month relative-value trade: Hyundai has a clearer margin-upgrade path; target 8-12% relative outperformance, stop if Hyundai guidance implies launch/capex slippage.
- Use any post-news strength in NVDA to fade the auto/robotaxi read-through: the revenue impact is too remote to move estimates; trade horizon 1-4 weeks, exit if automotive/industrial AI orders show an actual acceleration.
- Pair trade: long HMC vs short TSLA for a 3-6 month window if EREV/hybrid demand remains resilient; thesis is share shift in mainstream utility vehicles, with upside if Hyundai execution lowers its cost base faster than Tesla defends price.
- Watch-list only on GM/F/T suppliers with U.S. content exposure: if Hyundai’s North American ramp triggers order-share leakage in 2H, consider a short basket against HMC on a 6-12 month basis; invalidated if U.S. production ramps without margin dilution.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- Wall Street is pitching data centers as a major real estate bet. The risks are piling up
- AI predicts Palantir stock price for end of Q4 2026
- Nvidia-Backed Lumentum Says It Can't Keep Up With AI Demand. The Stock Is Surging
- From H-1B to CEO: How Satya Nadella traveled the path the U.S. just cut off for Microsoft workers
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect
- Fintool Alternatives After the Microsoft Acquisition