
Cohere and Aleph Alpha Sign Agreement to Become the First Transatlantic Sovereign AI Solution
Source: PR Newswire
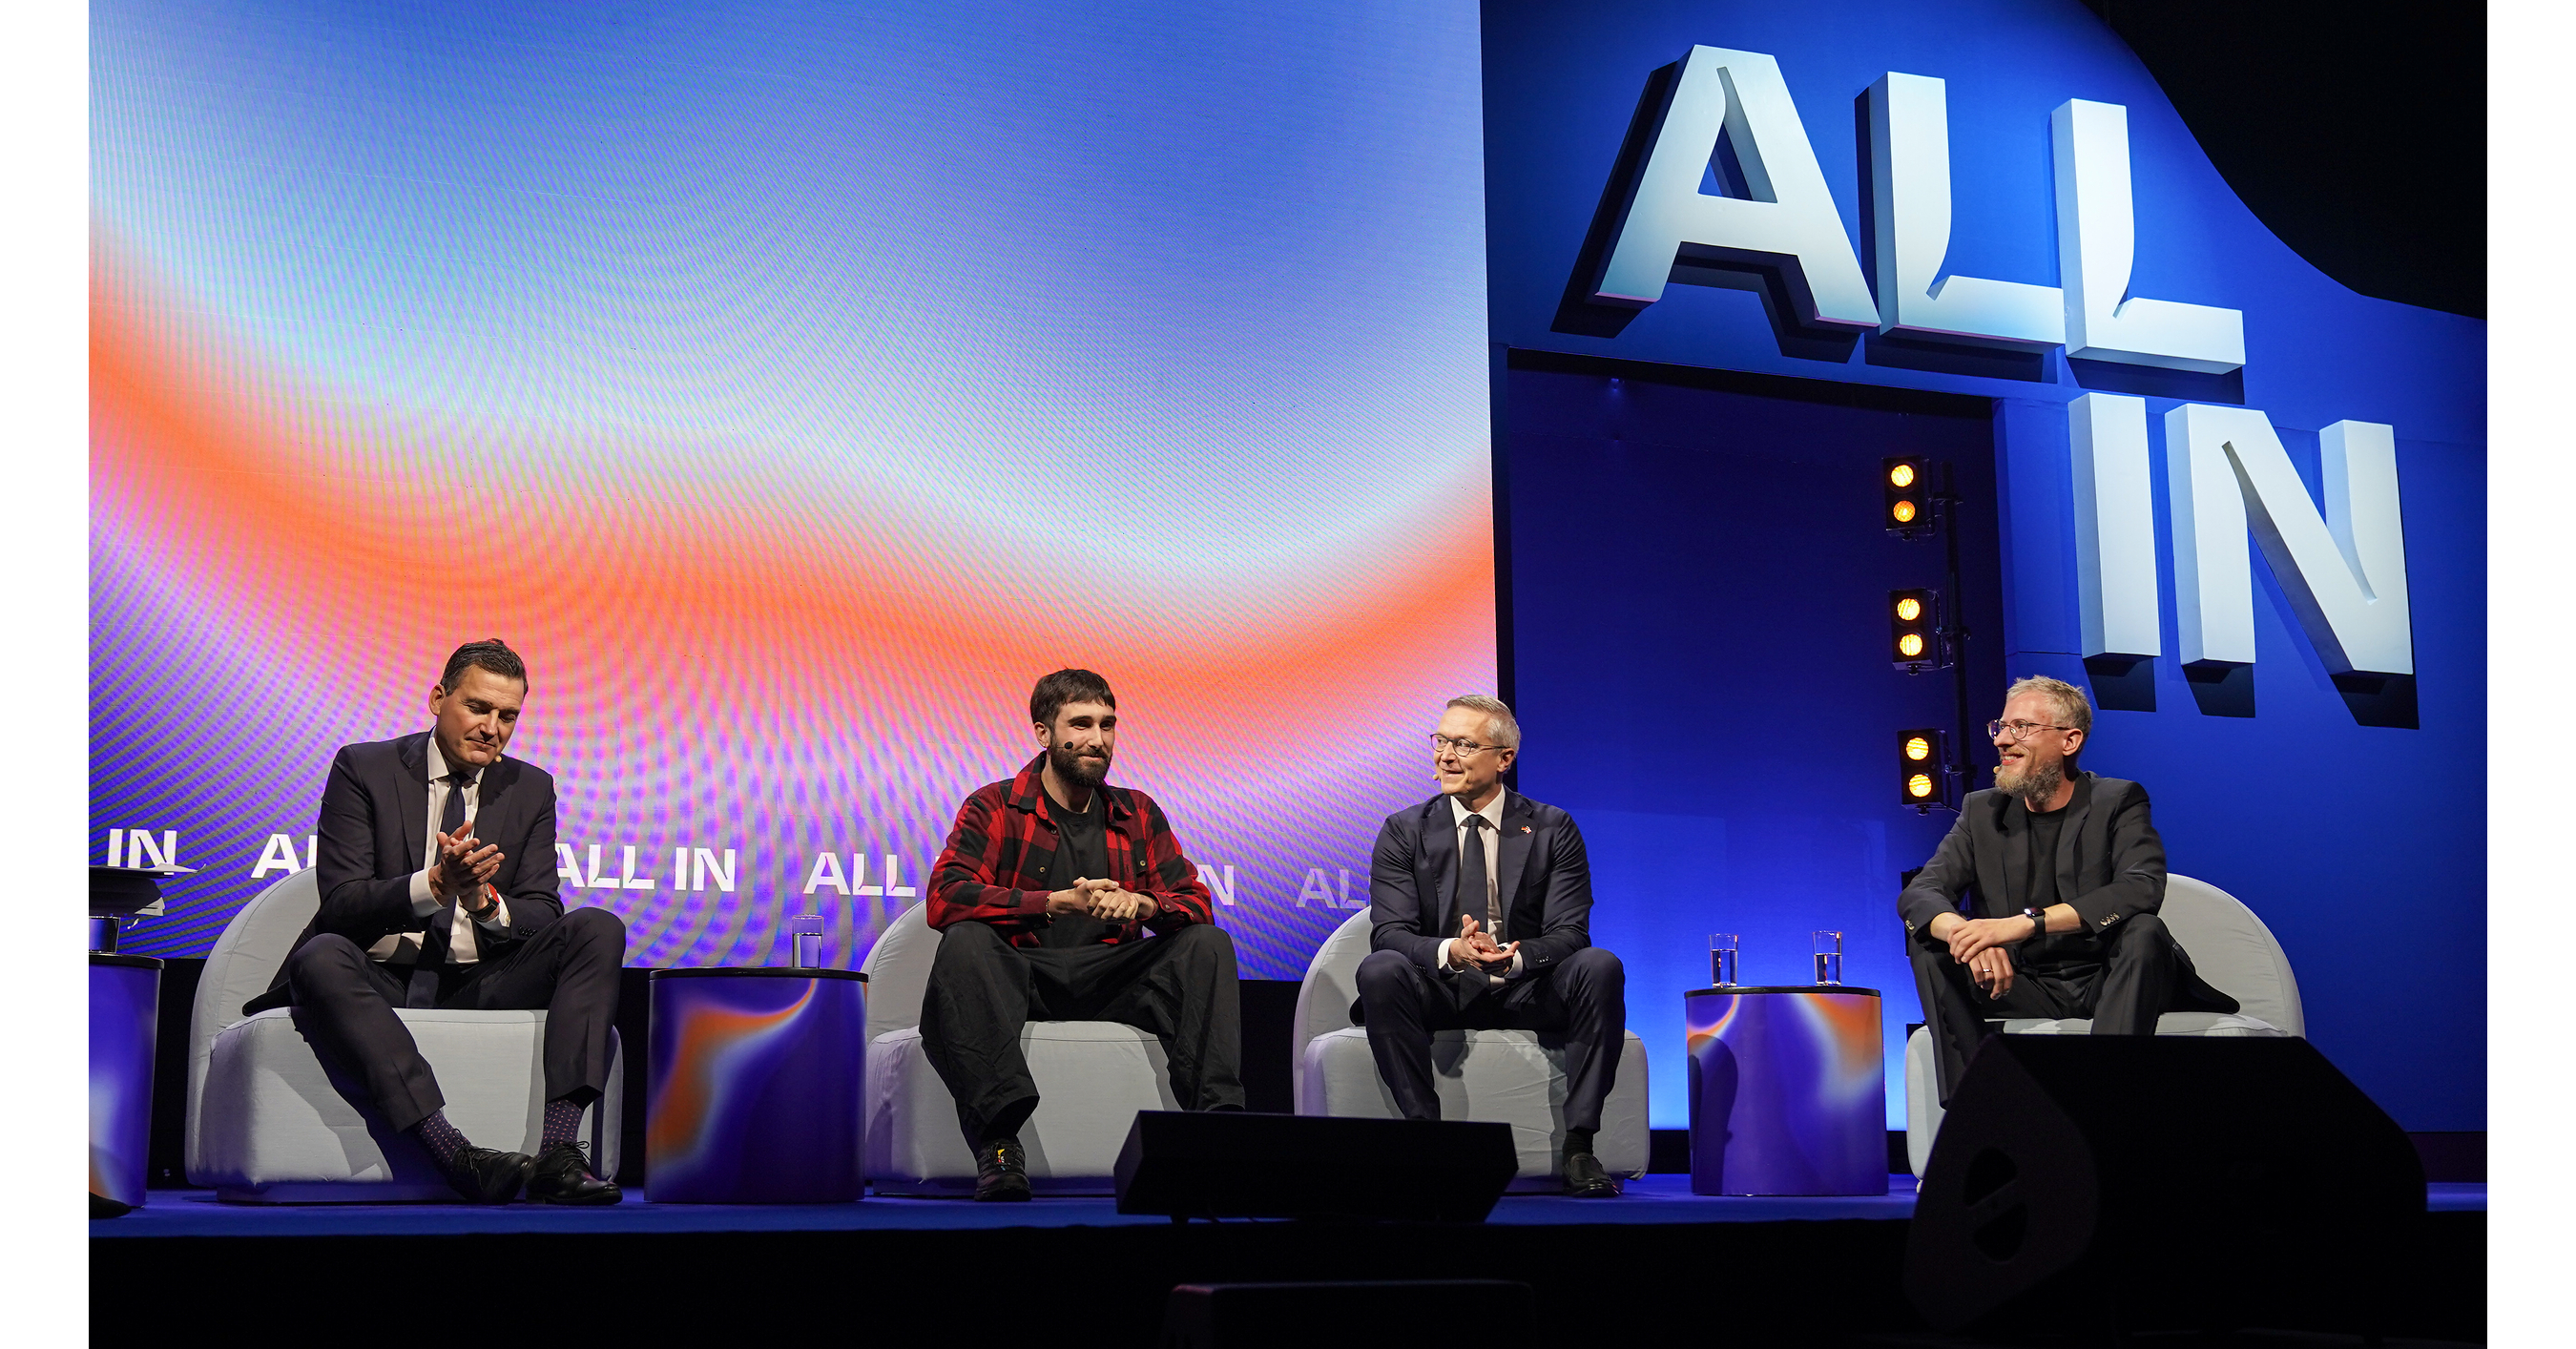
Cohere and Aleph Alpha signed a definitive business-combination agreement to create a transatlantic sovereign-AI provider, subject to final regulatory approvals and expected to close later in 2026. The combined company will operate as Cohere with dual headquarters in Toronto and Berlin, more than 1,000 employees across North America and Europe, and Aleph Alpha's Heidelberg office retained as a research center. The deal expands Cohere's government and regulated-industry AI capabilities, while advancing deployment on Schwarz Digits' STACKIT sovereign cloud platform.
Analysis
The investable implication is not a direct read-through to the private combined entity, but a potential acceleration of Europe-based, regulated AI deployments that require locally controlled compute, data residency, and auditable integration. ORCL is best positioned among listed names because sovereign-cloud demand raises the value of dedicated regional capacity and long-duration infrastructure commitments; CSCO benefits at the edge through zero-trust networking, segmentation, and air-gapped deployment architectures. NVDA captures incremental accelerator demand, but this is unlikely to alter near-term estimates unless sovereign procurement converts into multi-year capacity reservations rather than pilot programs.
The more important second-order effect is margin mix: regulated customers spend disproportionately on implementation, security, and integration relative to model inference. ACN could capture this services layer, while CRM faces modest competitive risk where public-sector customers prefer a locally hosted AI application stack over a hyperscaler-linked SaaS workflow. The partnership structure may also pressure European incumbents such as SAP and Deutsche Telekom/T-Systems to deepen sovereign-AI alliances, creating procurement competition that can constrain pricing for model vendors even as infrastructure spending grows.
Near term, this is a low-impact catalyst for public equities: closing, regulatory clearance, and evidence of funded government contracts matter more than stated strategic intent. Over 6-18 months, an EU preference for sovereign stacks could redirect workloads away from US public-cloud consumption toward dedicated regional infrastructure, benefiting ORCL and security/network suppliers but limiting the valuation premium attached to generic frontier-model access. Falsify the thesis if post-close disclosures show no committed cloud capacity, no material public-sector wins within two quarters, or if EU procurement standards permit equivalent compliance through existing hyperscaler regions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on the transaction announcement; Cohere and Aleph Alpha are private, and listed-ticker revenue sensitivity is presently unquantifiable. Set an alert for disclosed STACKIT capacity commitments, government framework awards, or named multi-year contracts.
- Use ORCL as the preferred 6-18 month sovereign-AI infrastructure exposure: accumulate on broad software/infrastructure pullbacks rather than chase news. Thesis requires accelerating OCI regional capacity bookings; exit or reduce if OCI growth decelerates for two consecutive reported quarters or management indicates capacity is being diverted from higher-return commercial demand.
- Maintain a modest long CSCO versus short CRM pair over 3-6 months only if European regulated-AI procurement broadens: CSCO has higher security/network content per private deployment, whereas CRM's AI monetization is more dependent on SaaS workflow adoption. Size tightly; close if CRM demonstrates sovereign-hosted product wins or CSCO's security-order growth fails to improve.
- Do not add NVDA solely on this development. Revisit only if European sovereign-cloud operators disclose accelerator orders or supply agreements; without that evidence, demand is too small relative to NVDA's global data-center base to support an incremental earnings thesis.
More News
- The Fed decision, Clarity Act fails in Senate, Ford's truck prices and more in Morning Squawk
- Snap tries to bring AR glasses to enterprise market, partnering with Nvidia, AWS and Salesforce
- Why Forgent Power Stock Keeps Going Up
- Fed decision looms large; Zuckerberg on AI safety fears - what’s moving markets
- Why is Snap stock climbing after-hours today?
- Micron vs. Sandisk: Which AI Memory Stock Benefits More From Nvidia's $279 Billion Warning?