
Intel: I Warned Before The 40% Crash, Now I'm Bullish (Rating Upgrade)
Source: seekingalpha.com
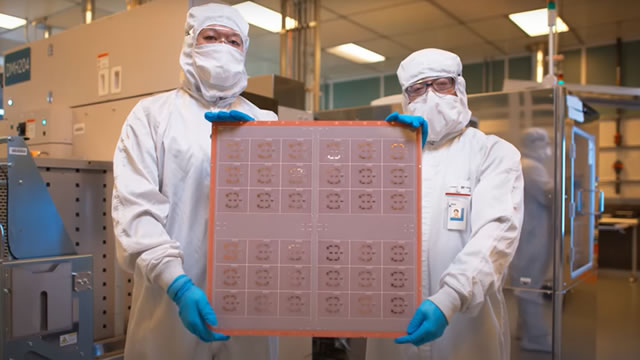
Intel was upgraded to Buy after a 40% share-price correction, despite substantial investment requirements through 2027. DCAI operating profit increased $565 million sequentially to $3 billion, with incremental operating margins of roughly 53%; Intel 18A manufacturing costs fell 40% since Q1. Foundry losses narrowed by $236 million sequentially while investment continued.
Analysis
Intel: execution proof matters more than the re-rating. The bullish mechanism is operating leverage: if DCAI profit gains persist, they can help fund product and foundry investment and reduce the market’s perceived need to value Intel chiefly as a capital-intensive turnaround. But sequential improvement is not yet evidence of durable share gains or self-funding economics. Falling 18A costs could reflect better yields or utilization; the key test is whether those gains translate into competitive products and credible external-foundry demand, not merely smaller losses.
Near term, the upgrade may support sentiment, but the 1–3 month catalyst is confirmation in reported results and guidance. Watch DCAI profit conversion, gross-margin trajectory, foundry cash use, and capex funding. A miss on any of these could unwind the valuation reset. Over 6–18 months, successful execution could improve Intel’s bargaining position against AMD in CPUs and make it a more credible alternative to TSMC for customers seeking manufacturing options. Conversely, delays or weak customer commitments leave Intel carrying investment while competitors capture demand. Nvidia and other AI-platform suppliers are not automatically displaced by better DCAI economics.
Contrarian point: a 40% drawdown does not itself establish cheapness; the market may be discounting execution and cash-flow risk rather than extrapolating current losses. Treat the cited operating improvements as claims to verify against filings and subsequent guidance.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Do not chase the upgrade on the article alone. Consider a small, staged INTC position only if the next results confirm DCAI operating improvement and show that cash use is not deteriorating; add after evidence, not before.
- Set a thesis-failure check: reduce or exit if guidance weakens, DCAI profit reverses, or foundry losses/cash requirements worsen despite the reported cost progress. Verify segment definitions and cash-flow impact in filings.
- Over the next 1–3 months, monitor 18A yield and product milestones, external-customer commitments, capex and free-cash-flow guidance. Without independent confirmation, keep the position at watch-list or starter size rather than making a high-conviction relative-value trade.
More News
- AI stocks plunge after election, driving down US markets
- Why is SPDR S&P 500 ETF Trust sliding today?
- Why is Direxion Daily Semiconductor Bull 3X Shares plummeting today?
- Nasdaq 100 futures slide 1% amid post-midterms rotation out of chip stocks
- AI, data-center stocks slip as Democratic sweep clouds expansion plans
- Nasdaq futures slip on chip weakness; S&P 500 holds gains