
PuroClean Identifies Salt Lake City as a Strategic Market for Franchise Expansion
Source: PR Newswire
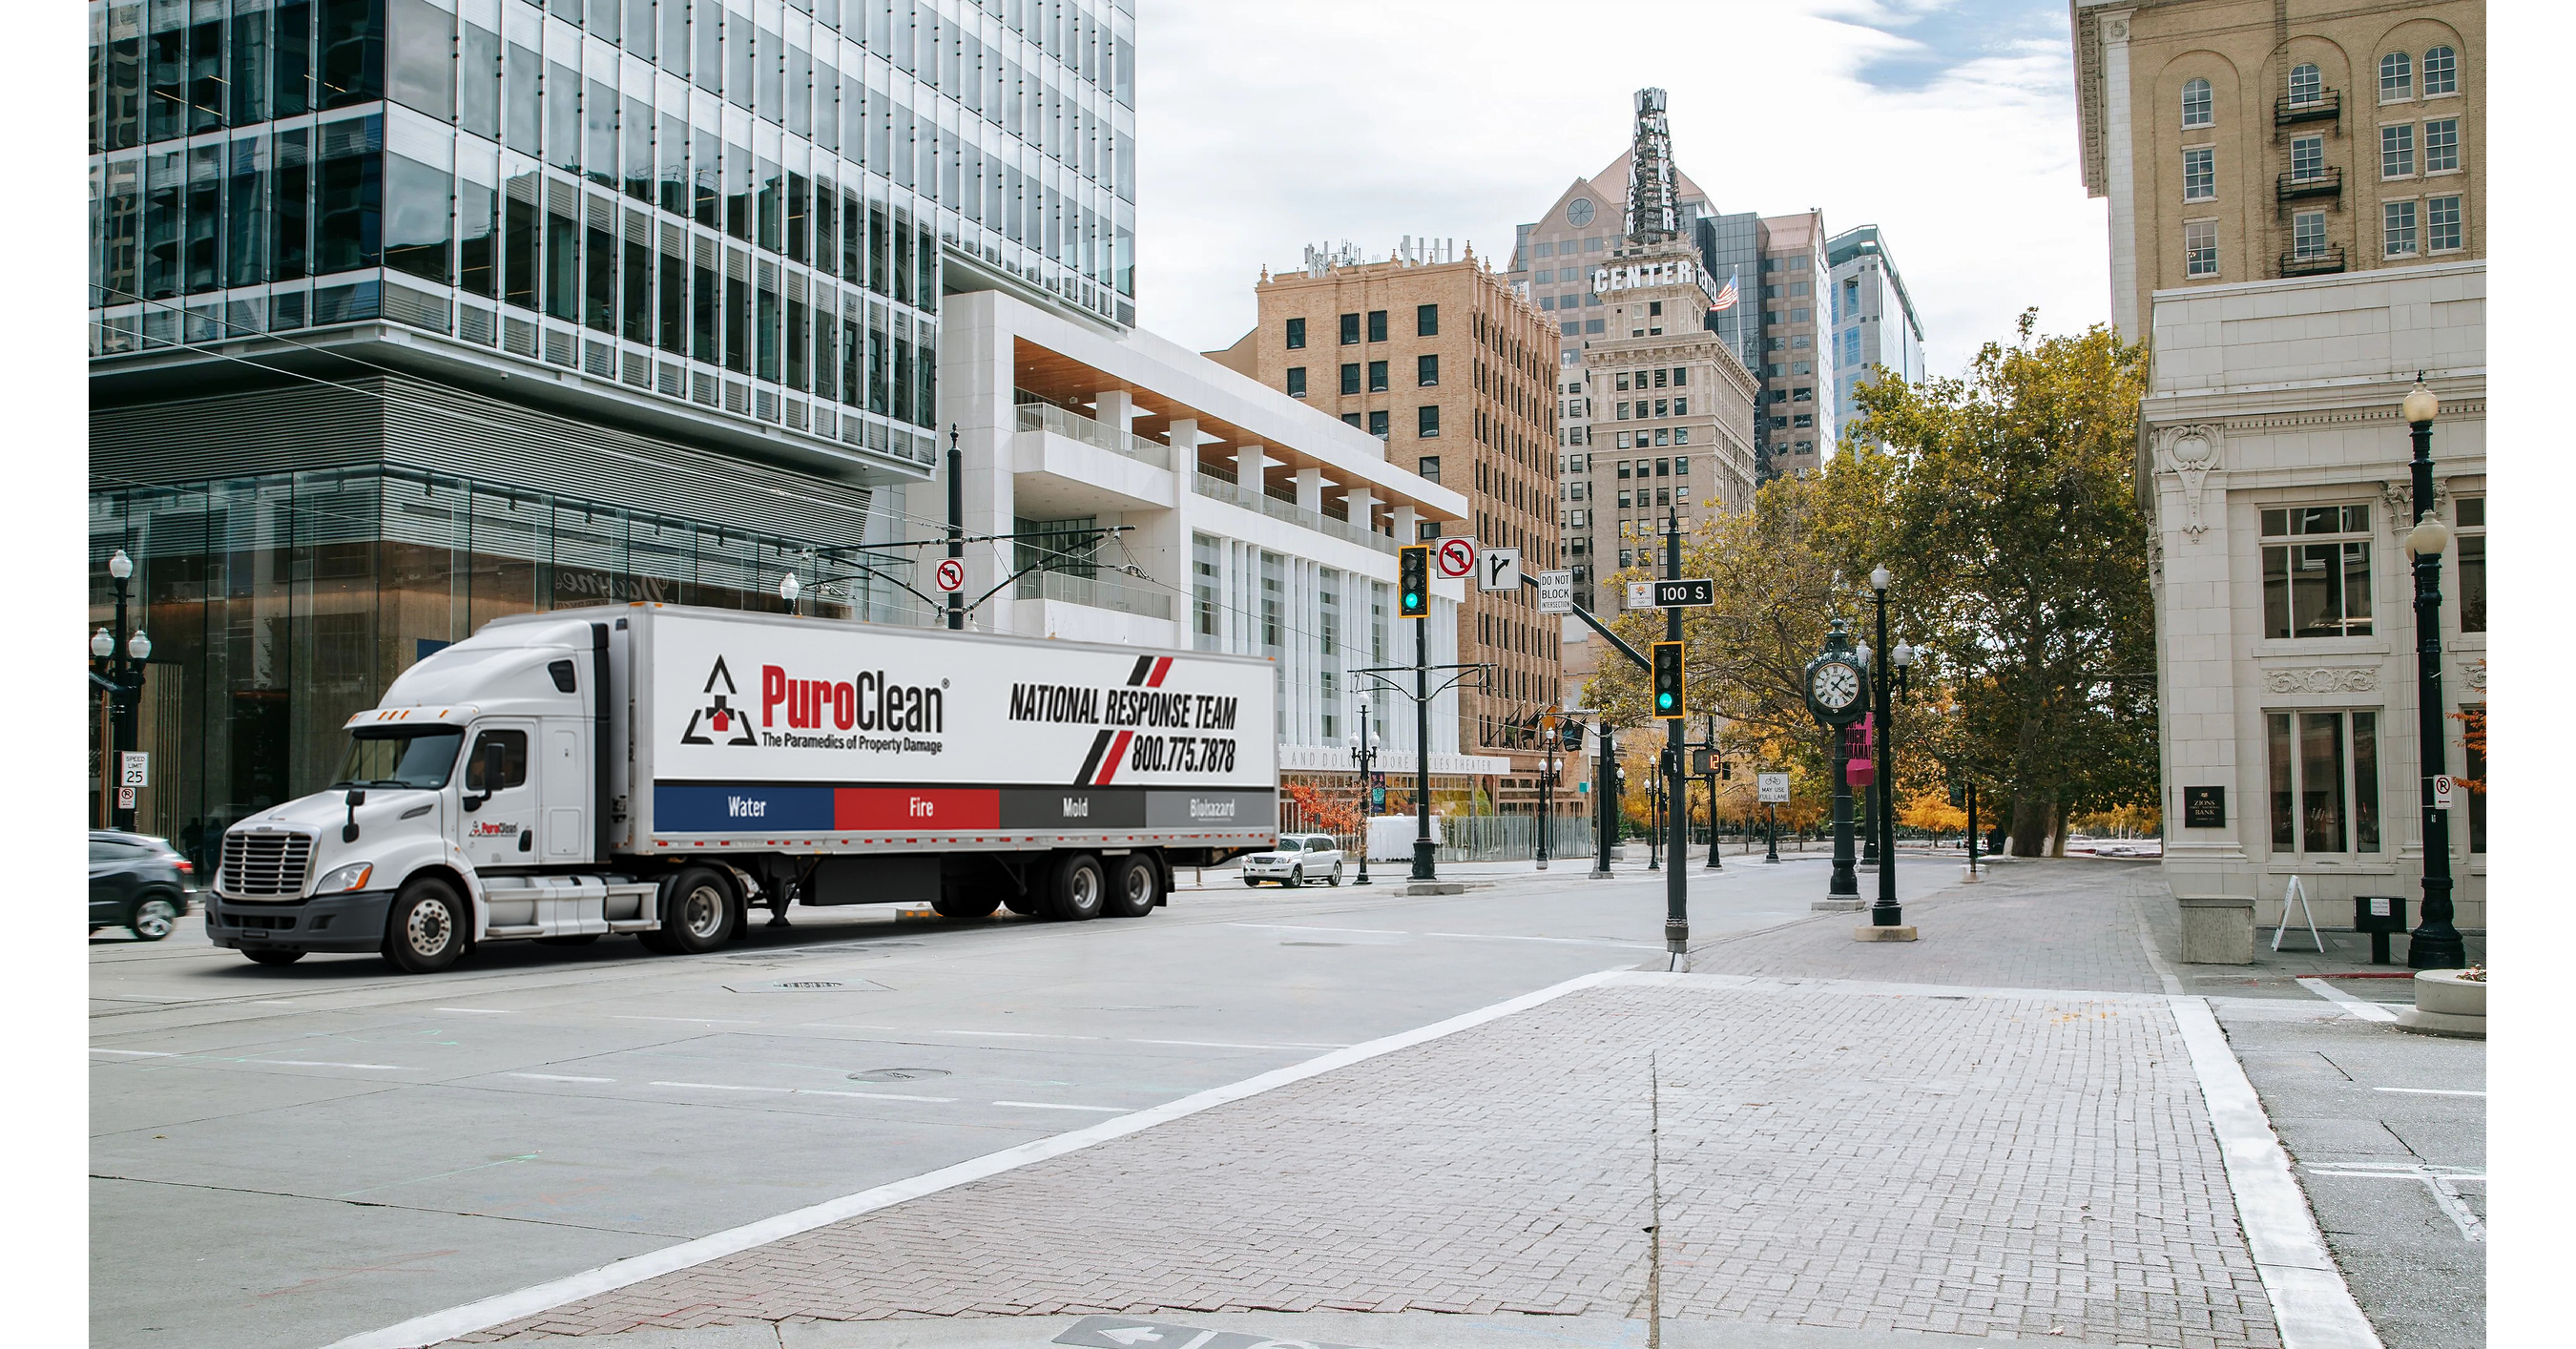
PuroClean is targeting five available Salt Lake City territories, citing recurring restoration demand from weather events and residential and commercial property damage. Nearly 25% of city buildings face significant flood risk and roughly 31% face wildfire risk, supporting the franchise's needs-based service opportunity. The company, which has more than 500 North American offices, is seeking operators to expand its local B2B and B2C restoration footprint.
Analysis
This is not a public-markets catalyst: the announcement is franchise-development marketing rather than evidence of incremental system sales, unit economics, insurer referral wins, or a change in loss frequency. The relevant investable read-through is modestly supportive for restoration demand density along the Wasatch Front, but five potential territories are immaterial to national public restoration and services platforms.
If regional catastrophe losses rise, the near-term economic beneficiaries are typically restoration contractors with insurer-program access and equipment availability, while carriers face loss-ratio pressure and higher reinsurance costs. Public proxies include BELFOR's private competitors rather than a direct listed PuroClean analogue; SERVPRO is also private. The cleaner listed second-order exposure is ROL and CTAS only at the margin through commercial remediation/service demand, while home-improvement retailers HD and LOW may see localized repair-product demand but no material earnings impact.
The more consequential 6-18 month variable is insurance affordability and underwriting retrenchment, not remediation volume. Higher deductibles, non-renewals, or tighter flood coverage can reduce discretionary mold and non-covered repair spend even as insured emergency work grows. A sustained regional claims cycle could also increase labor, dehumidifier, and subcontractor costs, limiting franchisee margins before pricing catches up.
Consensus should avoid treating climate-risk statistics as a linear revenue signal. Restoration demand is episodic, constrained by insurer dispatch relationships and technician capacity, and franchise openings can initially dilute local operator economics through competition for referrals and labor. No trade is warranted absent independently verifiable Utah loss data, carrier claim-severity trends, or disclosed unit-level revenue and margin evidence.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Key Decisions for Investors
- No position on this release; treat it as a watch item rather than a catalyst because neither PuroClean nor its primary national franchise competitors offer a direct listed equity exposure.
- Monitor Utah Department of Insurance filings, FEMA loss declarations, and major carrier commentary over the next 1-3 months. Escalate only if claim severity or non-renewal activity broadens beyond a localized weather event.
- For a broader insured-loss event, consider a tactical long RNR or RE versus short KIE only after catastrophe-loss estimates are established: RNR's alternative-capital platform can benefit from repricing, while primary insurers carry more immediate loss-ratio risk. Falsifier: benign loss estimates and no hardening in renewal rates.
- Avoid extrapolating any localized restoration-demand narrative into HD or LOW estimates; require evidence of regional same-store-sales acceleration or management commentary before assigning an earnings impact.
More News
- Australia’s central bank chief warns inflation risks materialising
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal
- Crusoe raises $3.9B to build massive data centers and small modular “AI factories”
- Jensen Huang says Nvidia will sell twice as many chips next year
- Generac shares surge on big Amazon deal. Wall Street thinks the generator stock has more to go
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market
- Investment Research Software Costs: A 2026 Budget Framework